

Turn economic complexity into clear insights & visuals. Research, data visualization & content for businesses, media & institutions. 🌐 https://nitter.cf/t.co/LBV0Esyo0E
Global
Joined June 2023
- Tweets4.1K
- Following669
- Followers11.2K
- Likes8.6K




Pinned Tweet
The Global Money Supply Monitor (#GMSM) aims to track, analyze, and monitor global money supply trends across economies, elucidating their relationship with the broader economy and financial markets.
Comprehensive coverage spanning 169 countries.
👇👇👇
econovis.net/global-money-su…

📈 Asian Markets Bear the Brunt as Global Stocks Fall 2.6% in October
📊 Full analysis and 5 charts from Econovis ↓
econovis.substack.com/p/glob…
Global stock market capitalization fell 2.6% in October 2026 from September, measured in U.S. dollars. Only six of the 21 markets shown recorded gains. Switzerland led with a 7.8% increase, while South Korea suffered the steepest decline at 14.9%—a gap of nearly 23 percentage points between the two extremes.
A mid-month sell-off in technology stocks contributed to the sharp losses across Asia, particularly in semiconductor-heavy markets. South Korea’s KOSPI fell more than 6% on October 13 as concerns over the scale and returns of AI investment weighed on chipmakers SK hynix and Samsung Electronics. It dropped another 7.6% on October 15, following a decline in U.S. stocks amid hotter-than-expected inflation data. Taiwan’s TAIEX fell 3.4% that day, while Japan’s technology-sensitive Nikkei 225 lost 2.5% on October 13. China also weakened, with its market down 8.4%. The Shanghai Composite had fallen to a more than two-month low on October 8 and slipped to around 3,690 by October 15. The Netherlands, down 8.0%, was also exposed to the semiconductor sell-off, given the significant weight of chip-equipment maker ASML in its stock market.
The U.S. market proved relatively resilient, declining 1.0%, less than the global average. However, technology stocks came under pressure during the month. The Nasdaq fell 1.9% on October 14, while late-month losses included an 11.8% drop in Alphabet on October 29 and a 4.2% decline in Nvidia the following day.
Markets with less exposure to semiconductors generally held up better. Switzerland gained 7.8%, supported by health-care stocks. The SMI rose for a fourth consecutive session to 14,130 on October 14, led by companies including Lonza, Roche, Sandoz and Novartis. Sweden also advanced, with Ericsson jumping around 9% after its third-quarter results on October 15 and the broader market rising on October 26. Gains were partly offset by a 2.5% decline in the OMXS30 on October 22, when Atlas Copco fell 7.7% following its results.
Currency movements also influenced the dollar-denominated comparison. The Brazilian real weakened sharply in the final week of October, losing roughly 8% against the U.S. dollar between October 23 and 30, amplifying Brazil’s 13.0% decline in dollar terms. The Mexican peso also weakened, meaning Mexico’s 4.0% gain would have been larger when measured in local currency. Japan’s 3.9% decline similarly reflects both movements in share prices and the yen’s depreciation against the dollar.
#equity #stocks #SP500 #Nasdaq #finance #investing #crypto #gold #AI #tech #semiconductor #chip

📈 Global Equity Market Cap Reaches $161 Trillion Despite October Pullback
📊 Full analysis and 5 charts from Econovis ↓
econovis.substack.com/p/glob…
Global stock market capitalization stood at $161 trillion on October 30, 2026, down 2.6% from September. A mid-October technology sell-off, fueled by concerns over AI spending and hotter-than-expected U.S. inflation data, hit Asian markets hardest. South Korea fell 14.9%, while Taiwan and China each declined 8.4%. Only six of the 21 major markets recorded gains.
The monthly decline is modest against the longer-term expansion of global equity markets. Since 2016, market capitalization has grown at an annualized rate of 9.4%, increasing roughly 2.5-fold in a decade. It is now about five times its level at the peak of the dot-com boom in 2000 and 5.8 times the approximately $28 trillion low reached during the 2008–2009 global financial crisis.
Earlier market shocks were considerably more severe. The global financial crisis erased roughly half of total market value, while the pandemic crash in 2020 and the 2022 market sell-off each wiped out 20% or more. In all three cases, markets eventually recovered and went on to reach new highs.
#equity #stocks #SP500 #Nasdaq #finance #investing #crypto #gold #AI #tech #semiconductor #chip

Econovis retweeted
📈 U.S. M2 Money Supply Hits Record $23.4 Trillion in September 2026
U.S. M2 money supply rose to a record seasonally adjusted $23.4 trillion in September 2026, up 0.48% monthly and 5.7% year-over-year—an increase of $1.26 trillion. Although M2 growth has rebounded, it remains below its long-term average annual growth rate of 6.2% over 2000–2026.
#USA #FED #USDollar #economy #liquidity #money #BroadMoney #MoneySupply #stocks #SPX #gold #bitcoin #investing

📈 Alphabet Loses $1.4 Trillion as Record-Breaking Rally Unravels
Alphabet’s market capitalization fell to $3.42 trillion on October 29, 2026, after an earnings miss triggered a 12.3% one-day plunge. The decline leaves the company’s value 29% below its May 13 record of $4.83 trillion, wiping out approximately $1.4 trillion in less than six months.
The sell-off reverses one of the largest corporate value gains in history. After bottoming at $1.78 trillion on April 8, 2025, Alphabet’s market value surged 2.7-fold to its May 2026 peak. Several catalysts fueled the rally: a September 2025 antitrust ruling that eased breakup concerns, strong third-quarter earnings in October, and the November launch of Gemini 3. Momentum was further supported by the general availability of its TPU v7 Ironwood chip and the disclosure of Berkshire Hathaway’s $4.9 billion stake. A 10% jump following Alphabet’s Q1 2026 earnings beat on April 30 carried shares to a new high.
After reaching its peak, Alphabet traded largely within a $3.9 trillion–$4.6 trillion range. Its market value fell to $3.89 trillion on July 23 before rebounding to $4.59 trillion on August 4. The October sell-off then broke decisively below that range.
Despite the sharp reversal, Alphabet remains worth nearly 1.9 times its April 2025 low and about 45% more than at the start of 2025.
#Alphabet $GOOG #equity #stocks #Nasdaq #SPX #AI #data

📈 U.S. Corporate Profits Hit Record as Corporate Tax Share Remains Low
📊 Full analysis and 7 charts from Econovis ↓
econovis.substack.com/p/us-c…
U.S. corporate profits and corporate taxes have followed markedly different long-term trends relative to GDP. Corporate profits have climbed to a record 14.9% of GDP in Q2 2026, surpassing the elevated levels reached around the 2000 dot-com bubble and the post-2008–09 Financial Crisis recovery. Corporate taxes as a share of GDP tell a contrasting story: from more than 5% in the early 1950s, the ratio declined over subsequent decades, falling below 2% for extended periods since the 1980s and remaining around 2% in recent years despite record profits. The widening gap between the two measures highlights a long-term divergence between corporate profitability and the federal tax burden relative to the size of the U.S. economy, with the gap becoming particularly pronounced during the latest profit expansion.
#USA #economy #corporate #profit #equity #finance #stocks #SPX #investing

📈 U.S. Profits-to-Market-Cap Ratio Near Historic Lows Despite Record Profits
📊 Full analysis and 7 charts from Econovis ↓
econovis.substack.com/p/us-c…
Even as U.S. corporate profits have reached record highs relative to GDP, they have become historically small relative to the value of the U.S. stock market. The profits-to-market-cap ratio has declined substantially since 1950, when U.S. corporate profits were equivalent to more than 30% of total market capitalization. By 2024–2026, the ratio had fallen to roughly 6%, among the lowest levels in the historical series and comparable to readings during the dot-com bubble and the 2020 pandemic. The divergence reflects the much faster growth of U.S. equity market capitalization than corporate profits over the long term. It also highlights how much higher current market valuations are relative to the earnings base than they were in earlier decades, with future profit growth and other factors such as buybacks and investor expectations playing a larger role in supporting market values.
#USA #economy #corporate #profit #equity #finance #stocks #SPX #investing

📈 U.S. M2 Money Supply Hits Record $23.4 Trillion in September 2026
U.S. M2 money supply rose to a record seasonally adjusted $23.4 trillion in September 2026, up 0.48% monthly and 5.7% year-over-year—an increase of $1.26 trillion. Although M2 growth has rebounded, it remains below its long-term average annual growth rate of 6.2% over 2000–2026.
#USA #FED #USDollar #economy #liquidity #money #BroadMoney #MoneySupply #stocks #SPX #gold #bitcoin #investing
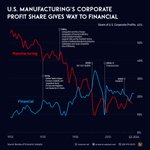
📈 U.S. Manufacturing’s Corporate Profit Share Gives Way to Financial
📊 Full analysis and 7 charts from Econovis ↓
econovis.substack.com/p/us-c…
Manufacturing dominated U.S. corporate profits for much of the postwar era, accounting for more than 55% of total profits in 1950. Its share declined steadily through the stagflation of the 1970s and fell more sharply in the 1980s, as deregulation, financial innovation, globalization, and the shift away from traditional manufacturing reshaped the U.S. economy. Meanwhile, the Financial sector’s share rose from less than 10% in 1950 and overtook Manufacturing in the early 2000s. Since then, the two sectors have alternated in their relative shares through the dot-com bust, the 2008–09 Global Financial Crisis, and the 2020 pandemic, with each episode affecting their profitability differently. By 2026, Financial accounted for roughly 22% of U.S. corporate profits, compared with 16% for Manufacturing—a much narrower gap than the one that characterized the mid-20th-century economy, reflecting a long-term convergence between the two sectors.
#USA #economy #corporate #profit #equity #finance #stocks #SPX #investing

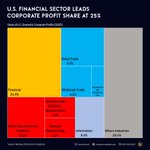
📈 U.S. Financial Sector Leads Corporate Profit Share at 25%
📊 Full analysis and 7 charts from Econovis ↓
econovis.substack.com/p/us-c…
The Financial sector captures the largest individual share of U.S. domestic corporate profits, accounting for 25% in 2025. Two broad groups are not far behind: Trade and Transportation—comprising Wholesale Trade (6.3%), Retail Trade (11.1%), and Transportation and Warehousing (2.6%)—account for a combined 20.1%, while Manufacturing contributes 18.6%, including Computer and Electronic Products (4.3%), Chemical Products (4.3%), and Other Manufacturing (10.2%). Within Manufacturing, Computer and Electronic Products—the segment most closely tied to the AI and semiconductor boom—account for 4.3% of domestic profits. This figure reflects profits from U.S.-based operations and does not capture the substantial overseas profits earned by many U.S. technology and semiconductor companies. Information accounts for another 8%, with smaller industries making up the remaining 28%.
#USA #economy #corporate #profit #equity #finance #stocks #SPX #investing

📈 U.S. Corporate Profit Growth Accelerates to 22.8% in Q2 2026
📊 Full analysis and 7 charts from Econovis ↓
econovis.substack.com/p/us-c…
U.S. corporate profit growth has historically been volatile, swinging between double-digit gains and sharp declines during downturns such as the dot-com bust, the 2008–09 Financial Crisis, and the 2020 pandemic. The current cycle stands out: after slowing in 2024 and the first half of 2025, profit growth accelerated to 22.8% in Q2 2026, among the strongest readings of the past two decades outside immediate post-recession rebounds. Unlike the sharp increases in 2009 and 2020, which followed steep profit collapses and were amplified by low-base effects, the latest acceleration is occurring at a record profit level. This suggests that the current surge is more than a mechanical rebound from a depressed base.
#USA #economy #corporate #profit #equity #finance #stocks #SPX #investing

📈 Real U.S. Corporate Profits Enter a New Growth Phase Amid the AI Boom
📊 Full analysis and 7 charts from Econovis ↓
econovis.substack.com/p/us-c…
Adjusted for inflation, U.S. corporate profits have grown at a 3.0% CAGR since 1950, but the long-term trend is marked by distinct periods of expansion and stagnation. A strong 1950–1966 expansion, with profits growing 4.4% annually, gave way to nearly two decades of stagnation from 1966–1992, when growth averaged just 0.6% amid the oil shocks, high inflation, and the Volcker-era recession. Profits then re-accelerated from 1992–2007, growing at a 5.5% CAGR, before the Financial Crisis ushered in another slower-growth period from 2007–2019, when profits grew 1.9% annually. Since 2019, growth has again averaged 5.5% annually, matching the 1992–2007 expansion but following a different path: an initial COVID-era surge of 8.8% CAGR from 2019–2021 was followed by renewed acceleration from 2024, with real profits growing 7.3% annually through Q2 2026 and reaching a record $4.8 trillion. The latest expansion has unfolded amid the technology and AI boom, alongside strong corporate investment and productivity gains, putting real U.S. corporate profits into another period of unusually strong growth.
#USA #economy #corporate #profit #equity #finance #stocks #SPX #investing

📈 U.S. Corporate Profits: A New Era of Record Growth
📊 Full analysis and 7 charts from Econovis ↓
econovis.substack.com/p/us-c…
U.S. corporate profits have entered a period of unusually strong growth, reaching a record $4.8 trillion in Q2 2026. The latest expansion stands out not only for its scale, but also for the breadth of the shift: profits are rising rapidly in real terms, reaching a record share of GDP, while the balance among major sectors continues to evolve. At the same time, profits remain relatively small compared with the value of the U.S. equity market, highlighting the widening gap between corporate earnings and market capitalization. Together, these trends provide a long-term view of how U.S. corporate profitability has evolved—from the manufacturing-led postwar economy to today’s more diversified, financially and technologically driven corporate landscape.
#USA #economy #corporate #profit #equity #finance #stocks #SPX #investing

📈 S&P 500 Market Capitalization Reaches $68.3 Trillion
The total market capitalization of the S&P 500 stood at $68.3 trillion on October 23, 2026, fluctuating around an average of $69 trillion since August. Since the start of the year, the index’s total market value has increased by $7.2 trillion, or 11.8%.
#equity #stocks #StockMarket #SPX #finance #investing #trading

📈 Silver’s Boom-Bust Year: Down 54% From Its January Peak
Silver spot prices have fallen to $53.9 per ounce as of October 23, 2026, down 54% from the record $116.6 reached on January 28. Prices more than doubled in the 12 months to that peak, rising 138% from $48.9 on October 23, 2025, and nearly quadrupled from about $30 at the start of 2025.
The unwind has been choppy rather than a straight line, with rallies in February and May failing to reclaim the highs. The July 17 low of $56.0 has now been broken, taking silver to its lowest level since late 2025. Even so, the metal remains 10% above its price a year ago and roughly 80% above its January 2025 level.
#silver #gold #PreciousMetals #XAG #investing

📈 Gold Falls Back Below $4,000, Down 26% From Its January Peak
Gold spot prices have dropped to $3,996 per ounce as of October 23, 2026, down 26% from the record $5,396 reached on January 29. The metal had climbed 31% in the three months to that peak, from $4,126 on October 23, 2025, and roughly 2.6x since the start of 2024.
The pullback has come in stages. A rebound to $4,601 on August 27 failed to hold, and prices have since slid 13% from that level back to the $4,000 mark. Gold is now 3% below its price a year ago, but remains nearly double its January 2024 level of about $2,050.
#gold #GoldPrices #PreciousMetals #bullion #XAUUSD #investing

📈 China’s Iran-Linked Oil Imports Plunge Amid War and Hormuz Disruption
📊 Full analysis and 6 charts from Econovis ↓
econovis.substack.com/p/pers…
China’s crude oil imports recorded as originating from Malaysia and Indonesia—widely believed to include substantial volumes of Iranian crude whose origin is obscured to circumvent sanctions—have risen sharply since 2015. Flows accelerated from 2022 onward, averaging 1.55 million barrels per day (mb/d) in 2025 before reaching a record 2.5 mb/d in March 2026.
The surge proved short-lived. Following the outbreak of war and disruptions around the Strait of Hormuz, imports fell to just 0.92 mb/d in June, recovered partially to 1.33 mb/d in August, then dropped to 0.69 mb/d in September. These sharp swings contrast with the more sustained buildup from 2022 to 2025, highlighting the growing volatility of Iran-linked oil flows amid regional conflict, sanctions enforcement, and shipping disruptions.
#China #Russia #SaudiArabia #energy #fuels #oil #crude #CrudeOil #OOTT #Iran #sanctions #HormuzStrait #Hormuz

📈 China’s Crude Oil Imports Plunge, Then Partially Recover
📊 Full analysis and 6 charts from Econovis ↓
econovis.substack.com/p/pers…
China’s crude oil imports peaked at 13.1 million barrels per day (mb/d) in December 2025, the highest level in the 18-month period, and averaged 11.4 mb/d for the year. Imports then fell for six consecutive months, hitting a low of 7.1 mb/d in June 2026—a 38% decline from 2025—before partially recovering to 8.5 mb/d in July and 8.9 mb/d in both August and September. September imports were up 26% from June but remained 22% below the 2025 average.
The decline was concentrated overwhelmingly in shipments from the Persian Gulf region. Imports from the region fell from 6.4 mb/d in February to just 2.1 mb/d in June, while flows from the rest of the world remained comparatively stable at around 4.6–5.2 mb/d, broadly in line with 2025 levels. This divergence suggests that disruptions to Persian Gulf supplies and sourcing played a major role in the spring decline, rather than a broad-based reduction in China’s oil imports. Potential contributing factors include war-related disruptions, sanctions, pricing conditions, and shifts in shipment schedules or contract timing.
#China #energy #fuels #oil #crude #CrudeOil #OOTT #Iran #sanctions #HormuzStrait #Hormuz

📈 China’s Crude Oil Imports Fall Below the 2020–2025 Range
📊 Full analysis and 6 charts from Econovis ↓
econovis.substack.com/p/pers…
China’s crude oil imports have remained well below their 2020–2025 historical range since April 2026. After starting the year at around 11–12 million barrels per day (mb/d), imports fell sharply from March, hitting a low of 7.1 mb/d in June—below the historical range. Volumes recovered modestly to 8.9 mb/d in both August and September but remained far below the 2025 average of 11.4 mb/d.
The sustained decline points to a significant shift in China’s crude oil import flows. Weaker demand may be one factor, but the scale of the shortfall could also reflect changes in supply availability, sourcing patterns, inventory management, and other market conditions. The weakness is particularly notable given the seasonal tendency for Chinese crude oil imports to strengthen in the second half of the year.
#China #energy #fuels #oil #crude #CrudeOil #OOTT #Iran #sanctions #HormuzStrait #Hormuz

📈 Persian Gulf Oil Shut-Ins Fall From 20% to 6% of Global Crude Exports
📊 Full analysis and 6 charts from Econovis ↓
econovis.substack.com/p/pers…
At their May 2026 peak, Persian Gulf crude oil production shut-ins were equivalent to 19.9% of global crude oil exports and 11.9% of world production—an extraordinary concentration of supply disruptions in a single region. By September, these shares had fallen to 6.2% of global exports and 3.7% of global production, declines of roughly 69% from their peaks.
Throughout the period, shut-ins accounted for a larger share of global exports than of production, reflecting the Persian Gulf’s outsized role in international oil trade. As a result, disruptions in the region can have a disproportionate impact on global oil markets. Although the decline in shut-ins points to a partial recovery in regional supply, the remaining disruptions in September still represented a significant share of global crude oil exports and production.
#Oil #Energy #CrudeOil #Crude #PersianGulf #HormuzStrait #Iran #SaudiArabia #UAE #USA #China #Geopolitics

📈 Persian Gulf Oil Shut-Ins Fall 69% as Iran Diverges From Regional Recovery
📊 Full analysis and 6 charts from Econovis ↓
econovis.substack.com/p/pers…
Persian Gulf crude oil production shut-ins relative to the 2025 average peaked at 8.9 million barrels per day (mb/d) in May 2026 before declining 69% to 2.7 mb/d in September. The recovery varied significantly across producers: combined shut-ins in Iraq, Kuwait, Oman, and Bahrain fell 83% from their May peak, while those in Saudi Arabia and the UAE declined 80%. Iran moved in the opposite direction, with shut-ins increasing 33% as the U.S. blockade effectively halted Iranian crude exports.
The divergence mirrors the broader recovery in Persian Gulf oil production. While most regional producers have restored output, Iran’s supply constraints have intensified, reflecting the disruption to its crude exports.
#Oil #Energy #CrudeOil #Crude #PersianGulf #HormuzStrait #Iran #SaudiArabia #UAE #USA #China #Geopolitics
