






Financial products that are gambling by another name are bad. Most people have no business trading interest rate derivatives, especially with their HOME on the line, and that's what ARMs are.

Tens of thousands of homeowners face a payment shock as their adjustable-rate mortgages reset, per the WSJ.
About 186,000 ARMs are set to reset next year, according to data from ICE. The typical borrower’s payment will rise about $645 a month at the first reset.
The hardest hit are people who took out seven-year ARMs in 2020, when rates were near record lows. Their median monthly payment is set to jump 43%, or $1,269, with some going from rates below 3% to closer to 8%.
ARMs make up only about 5% of active mortgages, and today’s versions have more safeguards than those that fueled the 2008 crash.
5
40
3,241
I think a lot of people struggle to come up with good use cases for personal AI agents because they're only considering tasks they already do today.
But as with many technologies, most of the value of personal agents will come from vastly expanding the "addressable market" of tasks worth doing.
Here are 3 real examples of how I used @bot this week.
“I’m hosting a party. Create a temporary gate code and email it to the guests.”
“Review my spending. For each merchant account, switch the default payment card to the one that earns the most rewards for that category.”
“My friends and I share season tickets. Transfer the tickets for each game to the right person according to the following logic…”
Each task required remembering which portals to use, navigating several bad UIs and completing a bunch of steps. The benefits in each case wouldn't be worth the friction of doing it manually.
AI compresses all of that into one step with a consistent interface: chat.
And that suddenly makes earning an extra $100/month in rewards or keeping my real gate code private worth it. And there are a thousand more small wins just like these...


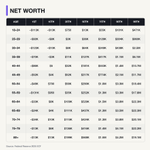
The Fed just published the 2025 Survey of Consumer Finances. A few quick observations on wealth in America:
- Net worth increases a LOT with age. 80 year-olds have 10x what 30 year-olds have.
- 18% are worth less than $10k. 27% when not including their primary home
- In middle age, median is ~$250k. 90th percentile is $2-3 million and 99th is $10+ million!


Another insidious cost of inflation and the rate hikes used to fight it.
People shouldn't have to treat old debt as their "biggest asset". The point of a mortgage is to live in a home, not bet on interest rates.
But rates are up almost 5% in 5 years. Now your old 3% mortgage dictates where you live and the timeless advice to pay off debt when you can is "wrong".
Most people do best when their financial lives are simple and in service of their real lives, and we've just flipped that upside down.

Paying off a 3% mortgage when rates are 5% might be one of the worst financial moves you could make in your entire life. Dave Ramsey has destroyed a generation of people. Debt is your biggest asset in an inflationary environment. Sheesh.
10
51
7,828
This. Lots of people would rather take their chances with the AI.
If Dario and co want people to take AI safety seriously as an existential risk, they’d do well to keep it very very separate from both our normal left-right politics and the extremely alien ethics and norms that pervade Effective Altruism.
Otherwise this is gonna be as convincing to many, especially conservatives, as “if you want to Save Democracy you’d better also vote for the Green New Deal”.

i think its reasonable to oppose ai safety because you believe the people who are declaring themselves in charge of ai safety are misaligned and the last thing in the world you want is for them to be the architects of your future
2
25
5,608
My friend Dan drove me around in his 911 for 1.5 hours and recorded. You'll never catch me rambling this long again.

New on Cars and Capitalists:
Paul Gu (@paulxgu), CEO and Co-Founder of @Upstart.
@Upstart is an AI lender worth $2.5B today. They did $1B in revenue in 2025, up 64%, grew originations 86%, and were profitable. Paul took over as CEO from co-founder Dave Girouard (@davegirouard) in May.
Before that, Paul was Upstart's CTO and built its first credit models. He's a Thiel Fellow and Yale dropout who came out of quant finance.
In this episode of Cars and Capitalists, we discuss:
0:00 - "The model's gonna suck": why you can't copy Upstart
2:02 - Three sheep, two breeds, one A/B test
8:13 - The core business: 50 million Americans the prime market won't serve
21:20 - Inflating away the debt vs. the hard choices nobody will make
29:58 - Cartoon math: $100 of loans, $5 of contribution, a 20% fund
41:33 - The real moat: Jane Street techniques pointed at consumer credit
58:03 - The golf trip problem, and paying dealers to pick you
1:06:03 - "No one wants to fund a new product. It's like nuclear waste"
1:16:51 - Killing auto refi, the product they were best at
1:24:42 - 2040: relevant to economic history, and unambiguously pro-human
Thanks to our sponsor @rootvc.
I disagree with AI doomerism. But it is not some conspiracy to make money through regulatory capture.
We've collectively developed an unhealthy obsession with 4d-chess explanations when the simplest one is usually right. Many people at Anthropic and OpenAI say AI could cause human extinction because they actually think so.
I've had spirited debates with friends in and around the AI safety / Effective Altruism worlds. I think they're wrong about many, many important questions and I think they live in quite the bubble. But I have no doubt about their sincerity of their beliefs.
Many of them worked in the field long before there was money or status in it. Many still routinely make choices that are obviously not income-maximizing.
Their argument is pretty simple: exponential acceleration + unclear destination = high chance of catastrophic accident.
We need more discourse on whether that's wrong, and less on their secret motivations.
Paul Gu retweeted

Todd Beamer was the passenger on United Airlines Flight 93 who rallied fellow passengers to fight back against the 9/11 hijackers with the phrase "Let's roll" and stopped it from reaching Washington, DC.
This is his daughter, Morgan, who was born 4 months after his death and went on to play women's soccer at his alma mater, Wheaton College.
Imagine how proud he would be. 🇺🇸 #neverforget

ALT #911remembrance #september11 #911 #america
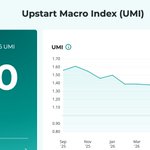
Upstart's macro index shows a corresponding 9% increase in default risk since April.
Everyone likes to ask about consumption, but it's actually consumer credit where the impact of macro shocks is seen most clearly. We saw it in dramatic fashion with the start and end of the COVID-era stimulus, followed by the '22-'23 inflation.
Now, just as things were starting to return to normal, Americans are getting squeezed again, resulting in higher credit utilization, and fewer or delayed repayments on debt - visible both in Upstart and industry data.
Looking at the mostly-always-going-up level of consumption undersells how destructive financial volatility, especially in prices, is for everyday Americans.
People don't need one-time or erratic government handouts, they need stable, predictable taxes, benefits, and prices they can plan their lives around.


Americans are getting financially squeezed. Inflation has wiped out wage gains since April.
Wage growth in the past year: 3.1%
Inflation in the past year: 3.4%
Many American households have to belt tighten and make difficult choices on what to cut back on. This is why consumption appears to be slowing (and will likely cool more, especially for middle-class brands).

Most public companies publish both guidance and results quarterly. @Upstart we publish origination volumes and UMI monthly, but offer guidance only annually. Why?
The principle is simple: we'll tell investors something if and only if we're prepared to stand behind it.
On guidance, that means only setting expectations I actually intend to manage the business toward. And in our business, managing to quarterly volumes often means delaying or compromising on the precision of credit. We won't do that.
Yes, the market will still make its own estimates, but there is an enormous difference between 3rd-party expectations and ones we set ourselves.
Volume and UMI, on the other hand, are things that already happened. When the facts are straightforward, knowledge beats ignorance, or guessing from third-party proxies.
Now, while the facts are simple, their interpretation is not. By default, quarterly earnings is when we'll be ready to do that right.
Over time, I believe the market will come to value knowing that when we say something, we mean it - we've examined it rigorously, and intend to do everything in our power to make it true.

Got asked at an all-hands how I balance time with my 3 young kids and running a high-growth public company.
Everything that came to mind was an uninteresting grind answer like “sleep less”. And of course that’s part of the math.
But since sitting with it, I think the more interesting answers reject the premise of the question. “Balance” sounds like picking a point on a curve of zero-sum tradeoffs. What you actually want are opportunities to be positive-sum and integrate kids into the flow of your life.
A few examples -
1) This summer my family came with me on two work trips as makeshift vacations. Instead of losing the travel time and bedtimes and breakfasts, I got to keep those disproportionately precious hours and also share a bit of what I do with my kids.
2) Outside work, I try to keep only hobbies I can do with my kids. Golf, biking, guy trips, latest TV show - no. Raising chickens, pool time, easy hikes, family friends - yes. Exercise is whatever fits in 30 minutes in my combo gym + kids playroom.
3) I’ve done a fair amount of co-sleeping. You have to sleep anyways! And it feels like surprisingly meaningful time when they’re young.
Don’t balance, integrate!
I oscillate between thinking we'll all be rich because of AI and we'll all be poor because of the federal debt.
CBO projects that by 2036 the % of all taxes going to interest will be 25-30% and growing fast. Social Security and Medicare are both running out of money, and also politically untouchable. That almost certainly will require significantly higher inflation or taxes to pay for, both of which can trigger vicious second-order effects (higher interest rates, slowing growth).
But CBO assumes just 1.8% real GDP growth per year. If AI-related productivity gains can get us to 5% instead, the federal budget problems are solved. That's an extraordinary bar - no decade has come close since the Great Depression recovery / WW2 mobilization. But AI is also the most important technology of our lifetime.
IMO the race between these two, technological abundance and government dysfunction, will be the economic story of the decade.
I’ve fretted for 14 years that @Upstart’s models would get stuck in a local minimum.
In lending, standard models only reduce the total error in predicting repayment outcomes (we use RMSE) compared to random by ~5%, and ours by ~13%, so there is an extremely long runway.
But in theory, it’s possible to get to a spot where every next model candidate could look worse than the incumbent so we stop innovating, while we’re still far from the best possible model.
Fortunately, it’s never happened, and this explanation does a beautiful job visualizing why!
