

Market insights from the desk... real-time analysis, economic debate, current affairs and a touch of humour! Try a 7 day trial & hear our serious voice.
London
Joined May 2009
- Tweets133K
- Following645
- Followers139K
- Likes20.2K





Pinned Tweet
Following the US Midterms? Try out the Newsquawk Midterm Dashboard. Every race, every price & every call live for subscribers.
Available at app.newsquawk.com/midterms
Not a subscriber? Get one week of Newsquawk Pro for free, and then 50% off your first three months with code MIDTERMS26, available until the end of the midterms only.

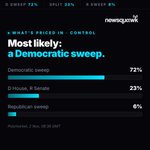
Quick snapshot of the focus points ahead of the US Midterms available below.
Full preview here > newsquawk.com/daily/us-midte…

Morning all!
- US President Trump said it was "largely true" that Republicans lost the midterms because of the Iran war, while he said he is not replacing War Secretary Hegseth.
- APAC stocks were mixed after the rally on Wall Street, with a rotation out of chip names; US equity futures are mixed, with the NQ lagging, while European equity futures point to a positive open.
- DXY remained subdued post-Midterms alongside lower yields; USTs and Bunds extend gains as lower oil eases inflation concerns.
- Crude remained pressured after Wednesday's slump, while spot gold returned to levels above USD 4,100/oz.
- Looking ahead, highlights include Swedish CPIF Prelim. (Oct), German Factory Orders (Sep), EZ PPI (Sep), US Initial Jobless Claims (Oct/31), Norges Bank, BoE, CNB & Banxico Policy Announcements, Canadian Federal Budget. Speakers include BoE's Bailey, ECB's Cipollone, Schnabel, Lane & Lagarde, BoC's Macklem, Fed's Hammack & Barkin. Supply from Spain & France. Earnings from ConocoPhillips & Deutsche Telekom.
Newsquawk retweeted
Before the market move, Newsquawk clients received the latest on Ferrari's strong Q1 2023 results: Revenue of 1.43bln (exp. 1.38bln), Net profit of 297mln (exp. 267mln), and Adj. EBITDA of 537mln (exp. 508mln).
Stay ahead of financial news with us. 🧢
newsquawk.com/sign_up.html

ALT Market move
🇺🇸US pre-market movers🇺🇸
ES +1.1% NQ +0.4% RTY +1.7%
Following US midterms:
Renewables gain $FSLR +7.5% $PLUG +7% $ENPH +4.5% w/ clean energy ETF $ICLN +4.8%
Neoclouds pressured $CRWV -6.2% $IREN -5.4% $NBIS -3.2% w/ neocloud ETF $NCLD -7%
Hyperscalers strengthen $AMZN +3.8% $MSFT +2.7% $GOOG +1.2%
$NVDA -1.5% $VRT -6.5% $ORCL -3.5% weighed on by less buildout
$SPCX -5.8% $TSLA -4.5% given where they operate AI supercomputer infra. from
Elsewhere:
$ORCL -5%: Cancelled $7bln 5yr AI chip leasing agreement w/ Tencent following pressure from Trump admin
$AMD +0.4% $SMCI +0.6%: Reversed a lot of strength post-strong earnings
$ANET +4.5%: EPS & rev. beat w/ strong next Q outlook
$SWKS -11.5%: Poor next Q guidance
$DOX -36%: Dismal outlook driven by significant T-Mobile headwinds incl. ongoing legal dispute
$DDOG -11.5%: Q3 beat but flat sequential growth
$BKNG +4.2%: Profit surpassed Wall St. exp.
$AMGN +5.5%: Strong Q metrics alongside lifting FY view
$XYZ +10%: Top, bottom surpassed Wall St. exp. & raised FY profit view
However, this unwound somewhat into the European morning, potentially on a fade of the Dem. trade, Trump's comments around possibly working with the Dems, local results (particularly Louisiana) and as attention returned to the Middle East.
Next up, a busy docket of events (details here newsquawk.com/daily/eu-marke…) while we await a few more local-level results stateside, but otherwise attention now firmly on the Middle East and the prospect for US kinetic action against Iran into/during the weekend.
Morning all!
- Democrats are seeing a very strong midterm result, flipping key Senate races in Ohio, Texas, South Carolina and Kansas, with DDHQ giving them a 99% chance of winning the House and a 100% chance of winning the Senate.
- US President Trump said he will accept the election result and is prepared to work with Democrats, while stating that veto power is one of the strongest powers he has.
- US equity futures were sold on prospects of a blue wave; APAC stocks were mixed, and European equity futures indicate a lower open.
- DXY was pressured and 10yr UST futures were underpinned early before paring much of the move, while spot gold saw a haven bid.
- Trump said the US has no immediate plan to strike Iran, although CENTCOM reportedly has a plan to strike as early as Wednesday.
- Looking ahead, highlights include Global Services/Composite PMI Final (Oct), EU HICP (Oct), US ADP Employment Change (Oct), Trade Balance (Sep), ISM Services PMI (Oct), Atlanta Fed GDP (Q4), Riksbank Policy Announcement, US Treasury Quarterly Refunding Announcement, NBP Policy Announcement, BCB Policy Announcement, BoJ Minutes, South African Municipal Elections. Speakers include Riksbank's Bunge & ECB's Lane. Supply from Germany. Earnings from Qualcomm & Novo Nordisk.
Newsquawk retweeted
Keep your financial knowledge up-to-date with Newsquawk.
🧢 Benefit from real-time news affecting forex, equities, and more.
Discover why professionals trust us during a 7-day free trial: newsquawk.com/sign_up.html #Investing
🇺🇸US pre-market movers🇺🇸
ES -0.1% NQ +0.3% RTY -0.1%
Memory ETF $DRAM +3% Semiconductor ETF $SOXX +2.8% Neocloud ETF $NCLD +2.2%
$AAPL -4%: Surging memory chip prices & rising AI-related costs weighed profit margin outlook
$PLTR -6.5%: Elevated investor exp. & sharp slowdown in US commercial contract growth, offset strong results, robust AI demand & accelerating FCF generation
$ON +3%: EPS & rev. topped Wall St. exp.
$FN +8.5%: Headline metrics beat w/ stellar next Q view
$LSCC +11%: Strong Q report & Q4 outlook
$SHOP -16.5%: Growth disappointment sees pressure & results struggle to justify lofty valuation
$KDP -5.5%: Rev. light as was FY top line outlook
$FISV +7.8%: EPS & rev. topped as did midpoint of FY profit view
$DD +2%: Lifts FY profit view amid strong healthcare & aerospace demand
Morning all!
- US equity futures were varied ahead of the US midterm elections and with Apple (-2.7%) ultimately declining post-earnings.
- AUD/USD ultimately weakened after the RBA hiked the Cash Rate by 25bps to 4.85% via a 6-3 vote but stopped short of signalling another hike in December.
- Crude futures attempted to nurse losses after slumping by around 8% on Monday; 10yr UST futures slightly pulled back after gaining yesterday.
- APAC stocks traded mixed following the continued tech rout stateside; European equity futures indicate a lower cash market open.
- Looking ahead, highlights include Swiss CPI (Oct), US JOLTS (Sep), US Midterm Elections. Speakers include BoC's Macklem & Rogers. Supply from UK & Germany. Earnings from Pfizer, AMD & Super Micro.
Code: MIDTERMS26 for 7 days free and then 50% off the first three months, available during the midterms only.

Newsquawk retweeted
Upgrade your trading strategy with Newsquawk 🧢.
We provide real-time news that matters to your trading.
Experience the difference with a 7-day free trial: newsquawk.com/sign_up.html #EquityTrading
Quick snapshot of the focus points ahead of the US Midterms available below.
Full preview here > newsquawk.com/daily/us-midte…
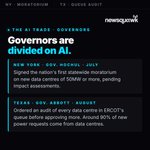
The AI angle: with a federal clampdown unlikely, data-centre policy is being set in the states, and governors are divided.
New York's Hochul signed a statewide moratorium on new data centres of 50MW+. Texas's Abbott ordered an audit of every data centre in ERCOT's queue.

