

Fundamentals. Finally, clear.
Joined February 2026
- Tweets177
- Following30
- Followers915
- Likes79
$AMD paid & taxed by the AI boom at the same time.
⚠️ 5 points to watch in earnings:
🔹 Data Center Revenue: $8.19B expected.
Helios racks began shipping in September.
When will that revenue will land?
🔹 Gaming segment: $655M expected, -49%.
Memory + storage costs have made parts more expensive.
What exactly is impacting revenue?
🔹 A shrinking PC market: $3.06B expected.
$INTC PC business fell -5% + guided down.
Does AMD see PC demand holding or following lower?
🔹 Q4 margin guide:
This quarter guided a 56% gross margin.
If Q4 guide comes in lower, a beat won’t matter.
🔹 Expectations:
Revenue $13B-$13.1B | Adj EPS $1.94 - $1.97


$PLTR had its best quarter ever and the stock is in a bear market.
Down -21% from highs.
The business:
✅ Revenue $2.31B, +96%
✅ Net dollar retention 165%, +8 points in one quarter
✅ U.S. commercial $984M, +148%
✅ FY26 guide raised to $8.53B from $8.15B
✅ Adjusted free cash flow margin 53%
The problem:
🔴 U.S. commercial contract value grew 11%,
against 148% revenue growth
🔴 Deals over $10M fell to 64, from 73 last quarter
🔴 70x forward earnings at $167
Palantir converts over half its revenue into cash.
But revenue is outrunning new contracts,
and until that flips the multiple has no cushion.


$AAPL margins are being eaten by memory prices driven by Big Tech’s $200B+ of CapEx.
Gross margin, quarter by quarter:
🔹 Mar: 49.3%
🔹 Jun: 50.1%
🔹 Sep: 47.9%
🔴 Dec guide: 45–46%
March had no tariff refund.
June had 2pts, Sep had 1pt.
$AAPL’s manufacturing purchase obligations rose $33B to lock in component supply.


$PLTR grew revenue 93% last quarter.
RBC says sell, BofA says buy.
Last quarter context:
- Commercial: $945M
- Government: $990M
- Operating margin: 47%
⚠️ What we need from earnings:
🔹 Commercial traction. Are customers converting into recurring contracts, or just trying the product.
🔹 Government momentum. Watch if new defense work maintains revenue.
🔹 $NBIS was named the preferred sovereign AI infrastructure partner. Listen for revenue detail.
🔹 Expectations: Revenue $2.16B - $2.18B | EPS $0.41

If you own $AAPL stock or options right now,
read this before market close:
Last quarter context:
- Revenue: $109.4B, +16% YoY
- iPhone: $54.3B, +22% YoY
- Gross margin: 50.1% (2 points one-time tariff refunds)
- EPS: $2.02, +29% YoY ($0.11 one-time tariff refunds)
⚠️ Earnings after close, what can impact price:
🔹 Memory Shortage & inflated component prices are expected to impact hardware profitability.
Gross margin guided at 47–48%.
🔹 Services Growth. The buffer against hardware volatility, $31.6B expected.
🔹 Commentary on $GOOGL partnership & Gemini integration.
🔹 Commentary on AI monetization.
🔹 Expectations: Revenue $113.3B - $113.5B
EPS $1.98 - $2.00

Worst earnings season for megacap tech stocks in a very long time.
$META First negative FCF ever.
🔸 CapEx: $33.94B
🔸 FCF: -$1.16B
$GOOGL FCF blew past -$2.70B est.
🔸 CapEx: $51.36B
🔸 FCF: -$9.07B
$AMZN Defended spending for AWS growth, but core retail showed weakness.
🔸 CapEx: $77.26B
🔸 FCF: -$34.84B
✅ The exception...
$MSFT
🔸 CapEx: $39.37B
🔸 FCF: $18.63B


$AMZN AWS projected revenue growth rates of over 40% in 2027 & 2028.
✅ AWS Q3
Revenue $46.0B, +39% YoY (est. $45.4B)
Operating margin 38.7%
🟡 CapEx $77.26B.
Full-year guide held at $220B.
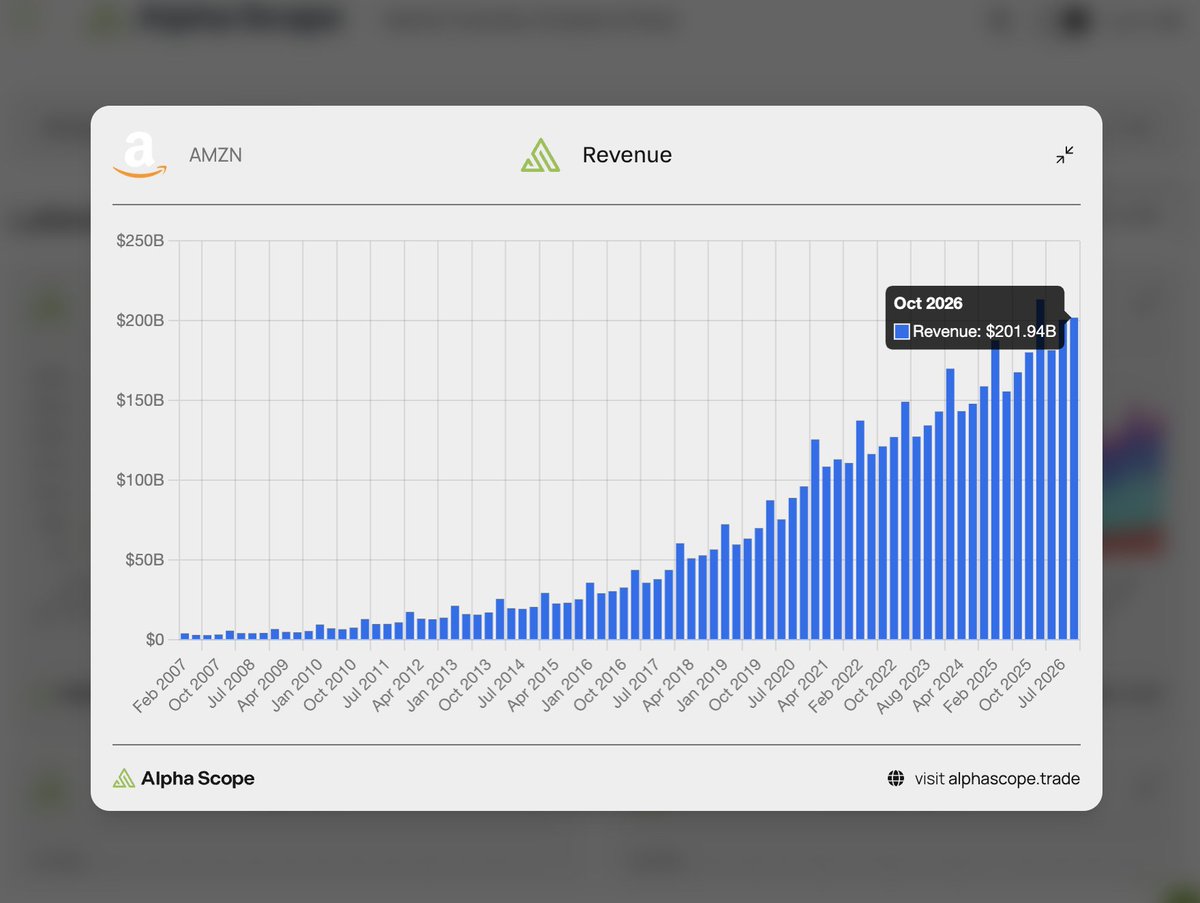
❌ Q3 Revenue: $201.9B vs $202.2B est
❌ EPS: $1.89 vs $1.96 est
❌ Free cash flow: −$42.4B
✅ Operating income $28.1B vs $26.2B est, +61% YoY


$INTC down nearly -30%
✅ Data center group: $7.3B, +78% YoY 🚀
✅ Gross profit margin: 43%
✅ Cash from Ops: $5.1B
🟡 Foundry $6.7B, +58% YoY
Operating at a $1.85B loss, but narrowed from $2.32B.
❌ Q4 revenue guided $15 - $16B, down 6% from Q3
❌ Q4 gross margin guided to 37.1%, from 43%


$AMZN what matters in earnings tonight 👇
Last quarter context:
- Revenue: $200.6B, +20% YoY
- AWS Revenue: $42.2B, +37% YoY
- Operating income: $27.5B, +43% YoY
- Free Cash Flow: −$7.6B
*negative FCF isn't as scrutinized because it's also a retail business
⚠️ What to watch:
• Does AWS keep accelerating?
Consensus is $45.4B, +38%.
• Is Capex spending still on track?
Amazon raised $25B in July bonds and said it wouldn’t borrow again in 2026.
Roughly $120B of CapEx is left for this half.
• Consensus: Revenue $202B (+12%), EPS $1.96


$MSFT spending paying off 💸💸💸
🟢 Revenue: $92.3B, +19% YoY (est. $90.6B)
🟢 EPS: $4.92, +32% YoY
🟢 Operating margin: 50%, up a point
🟡 Free cash flow: $18.6B, −27% YoY
🟢 Azure grew 48%, +40% YoY
24 new data centers online in the quarter.
Commercial RPO: $677B, +73%
($203B converts in the next 12 months)
Returned $7.3B dividends and $2.9B buybacks to shareholders.
$MSFT did what $GOOGL couldn't.


Can't believe $GOOGL
✅ Cloud accelerated
Revenue $30.7B, +103% YoY
Operating margin 36.2%, from 23.7%.
Backlog $561B, up $47B in one quarter.
❌ Free cash flow −$9.1B vs −$2.7B est. 😧
❌ EPS: $2.14 vs $2.99 est
($2.67 after adding back the $0.55 equity loss)
❌ Operating income: $40.6B vs $43.23B est
❌ Search $63.4B vs $64.99B est.
Management said AI Mode queries monetize below traditional search ads.
But Search is the profit engine, so a miss outweighs the Cloud beat.


$GOOGL sits on $514B Cloud backlog heading into earnings today. 🚨
Here's what we need from Q3 👇
Last quarter context:
• Revenue: $119.8B, +24% YoY
• Google Cloud: $24.8B, +82% YoY
• Operating Profit Margin: 34%
• CapEx: $44.9B, +107% YoY
• Free cash flow: −$5.9B
Full-year CapEx guidance raised to $195 – $205B. ($80.6B spent in H1)
⚠️ What to watch today:
• Cloud Momentum: Can it maintain growth?
• Free Cash Flow: Does it remain negative as CapEx climbs?
• Search Resilience: Search ads grew 17% in Q2.
Is AI driving queries or cannibalizing click revenue?
• Consensus: Revenue $127.9B | EPS $2.94

$MSFT doubled CapEx last quarter and cash fell -23%.
Buyout offers just went to a quarter of its global workforce.
Here’s what matters in earnings tonight 👇
Last quarter context:
- Revenue: $90B, +18% YoY
- Operating Profit Margin: 45%
- CapEx: $35.80B, +110% YoY
- Free cash flow: $19.64B, -23% YoY
⚠️ What to watch:
• What's limiting growth? CFO Amy Hood on Q4 FY26 call confirmed: “...demand still exceeds our available supply.”
• Commentary on the voluntary buyouts and what it does to margins.
$MSFT trades at 29x earnings but 58x free cash flow. CapEx is the gap. It’s only cheap if the spending pays off.


$VRT 🔥 one of the best earnings so far this season
🔸 Revenue: $4.31B, +61% YoY ✅
🔸 Operating profit: $983.8M, +90% YoY ✅
🔸 EPS: $1.99, +91% YoY ✅
🔸 Cash frm Ops: $794M, +64% YoY ✅
🔸 Organic orders UP more than 100% YoY ✅
$VRT doesn’t disclose backlog, so organic orders backs up accelerating demand.
CEO Giordano Albertazzi: “We are in the middle of the largest infrastructure buildout and it’s accelerating.”


Two things matter from hyperscalers this week:
1. Do they still want to spend?
2. Can they show how the spending gets paid back?
$MSFT & $GOOGL report Wed.
$AMZN reports Thu.
⚠️ Fed rate decision Wed, 2pm ET.
If the spending holds, the tightest component constraint is memory.
Direct reads on memory this week:
🔹 Mon $AMKR $RMBS
🔹 Wed $KLAC
🔹 Thu $SNDK
Other chokepoints reporting this week:
🔹 Mon $CLS
🔹 Tue $STX $GLW
🔹 Wed $VRT $APH $GEV


