

The intelligence layer for on-chain capital.
Munich
Joined July 2022
- Tweets694
- Following261
- Followers4K
- Likes365



1/ Stellar had roughly $4B of tokenised real-world
assets on-chain by late August.
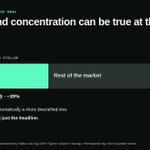
One issuer accounted for about $1.55B of that.
That’s roughly 39% of the total. Growth and
concentration can be true at the same time.

2/ The headline says the market is growing.
The next question is what sits underneath that
number: how much comes from one issuer, one asset
type, or one underlying exposure.
A larger market isn’t automatically a more diversified one.
3/ That’s why we read the markets, not just the
headline.
Backing. Concentration. Exit.
app.alterscope.org
Source: Stellar public RWA reporting, late Aug 2026.
Figures subject to change. Informational only.
Not investment advice.
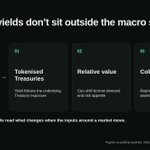
1/ On-chain yields don’t sit outside the macro system.
Rates move the return available on government debt,
the hurdle rate for riskier trades, and the price of assets
used as collateral. All three eventually show up on-
chain.

5/ The macro calendar belongs next to the on-chain one.
It won’t tell you where rates or prices will go. It tells you when inputs may get repriced.
Fed meetings. Minutes. Inflation data. Treasury moves. Those dates matter when collateral, borrow demand or yield depends on them.
6/ We don’t predict rates.
We read what a market looks like now, and what
changes when the inputs around it move.
alterscope.org
Sources: Federal Reserve, 7 Oct 2026; Farside
Investors. Figures subject to change. Informational
only. Not investment advice.
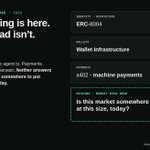
1/ 2026 gave agents a lot of the plumbing.
ERC-8004 added an on-chain layer for identity,
reputation and validation. Wallet infrastructure lets
agents control funds. x402 and machine-payment
integrations made it possible to pay for APIs and
services programmatically.

6/ Honest limit: the read does not make the decision.
It makes sure the decision is not being made blind.
That is a smaller claim, and a more useful one.
7/ docs.alterscope.org
Sources: ERC-8004 specification, Coinbase x402
documentation and Stripe machine-payments
documentation. Informational only. Not investment
advice.

1/ A year on from 10 October 2025, when more than $19 billion of leveraged crypto positions were liquidated within 24 hours. The lesson wasn’t that leverage is bad.

4/ That’s why headline liquidity and usable exit depth are not the same thing.The number that matters is what your position can actually get through when everyone else is trying to do the same.