
Owning tiny bits of quality businesses.
Joined December 2015
- Tweets3K
- Following1.3K
- Followers3.1K
- Likes2.2K




BLS Capital Fondsmaeglerselskab — Q3 2026
Initiated a sizeable new position in Netflix ($NFLX):
🟢 $135.2M | 5.40% of reported portfolio
Source: Form 13F

338
Blue Whale Capital — Q3 2026
5 new positions:
🟢 SK hynix 6.78%
🟢 Meta 4.73%
🟢 Marathon Petroleum 4.10%
🟢 Amazon 1.72%
🟢 Forgent 1.09%
❌ 8 exits, including AppLovin, Honeywell & Uber.
Source: 13F

421
The $pubm Pubmatic thesis has started to play out and strengthened materially over the last months …
CTV , mobile app and emerging revenues have now reached approximately 65% of revenue.
👉 CTV grew > 30%
👉 mobile app nearly 40%
👉 Emerging revenue more than doubled
👉 Activate buying activity > 8x YoY
👉 120 autonomous agentic campaigns in Q3 (vs 80 in Q2)
👉 more than 14000 AI -powered deals (up from 4k last q)
👉 Double digit growth has become the new norm
Investor perception starts changing from 👇
Pubmatic is just a commodity SSP intermediary business
to
Pubmatic is a potential AI beneficiary undergoing a genuine business model transformation.
AI simplifies advertising - buyers and publishers transact more directly - advertising moves from traditional sell-side targeting toward sell side decisioning where proprietary first party data and AI decide which impressions are most valuable in real time.
The transformation seems to be working with strong momentum carrying into 2027 and the Google Antitrust remedies pointing to market share gains and further upside not currently accounted for in the guidance.


Added to Pubmatic $Pubm . 2.3% position with my average cost basis dropping to $12.
Investment Thesis 👇
👉 The market is pricing it like a structurally declining and commoditized SSP, while CTV and SPO-led demand will reaccelerate revenue growth to 15%+ CAGR and expand EBITDA margins, driving a durable re-rating.
An asymmetric bet on the plumbing of the open internet. The downside is protected by a $150M net cash balance sheet (~25% of market cap) with zero debt and a profitable core business with a structural cost advantage from owned infrastructure. The upside is a rerating from accelerating CTV revenue mix with the Google Antitrust Case providing additional optionality for market share gains.

2
504
Greenbrier Partners initiated a small but meaningful position in Tyler Technologies ($TYL) in Q3 2026.
🟢 50,000 shares | $15.9M | 1.18% of portfolio.
Source: Form 13F

2
1
518
Brazil judge suspends part of the new meal voucher rules.
$eden.pa Edenred shares up 5%
Seen this movie before, not very hopeful on 🇧🇷 with Lula winning the election.


3
635
"Even a stopped clock is right twice a day"

Fund manager Nick Train has best month since 2000 on back of AI market rout ft.trib.al/UG3uEYw

383
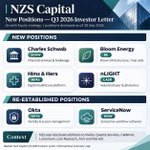
NZS Capital | Q3 2026 Portfolio Changes
New positions:
• $SCHW — Charles Schwab
• $BE — Bloom Energy
• $HIMS — Hims & Hers
• $LASR — nLIGHT
Re-established positions:
• $OKTA — Okta
• $NOW — ServiceNow
Exits:
• $IR — Ingersoll Rand
• $UBER — Uber
• $CSGP — CoStar
Source: NZS Capital Q3 2026 Investor Letter.

1
717

Yannis Stamatopoulos retweeted
We just released the Pershing Square Inc. third quarter letter which includes an update on the business, a detailed portfolio review including an update on F2, some thoughts on AI and the hyperscalers, and our perspectives on recent developments in the capital markets. It can be found here:
pershingsquareinc.com/wp-con…
In both investing and life, there will always be someone better and more talented.
Stop competing on their terms. Instead, choose the game that fits your own strengths and maximise your chances of winning.
Added 3 more stocks in the kids portfolio and sprinkled some extra cash across some losers…
Stock no 35: Boston Scientific $bsx
Stock no 36: HCA Healthcare $hca
Stock no 37: Hubbell $hubb
$mc.pa $bro $cprt $bf.b $ma $msft $cp $nke $mcd $v $aapl $wkl $zts $vrsk $bmi $tri $bdx $efx $pfe $dhr $awk $dis $tyl $csgp $ice $cme $spgi $TDG $vie.pa $snn $otis $bsx $hca $hubb


Have started buying a few stocks for the kids as a fun experiment. Miniscule position on each, will keep adding one new name every month.
Durable well known brands with incumbency and slow fade rates that will hopefully survive the test of time.
The first 3 names 👇
What should we add you reckon?
$nke $mcd $aapl

2
589
Tom Gayner’s Markel Group — New positions Q3 2026
16 newly reported positions, including Zebra, Silicon Labs, Tyler Technologies and Copart.
$ZBRA $MBGL $SLAB $TYL $CPRT $XPEL $VGZ $WSC $XRN $XYL $WTS $VVV $SITE $TOST $XPO $VMC
These are all small tracker positions what he calls ‘farming process’ . There are a lot of seeds that are planted to see which of these investments will flourish and get himself familiar with the names.
The largest is just 0.018% of Markel’s $12.84B portfolio.
❌ Exit: Brown & Brown
🤖 Made with AI

3
932
Investing is a deeply personal experience, and what looks like a great investment to one person may not to another. The same holds true for investment philosophies, processes and decision frameworks. They need to suit your own temperament and personality, they cannot be outsourced.
My Coffee Can decision framework is a mosaic of multiple investment philosophies I stumbled across and reasomated with me. Summarized 👇
Gate 0 — Investment killers
A stock is rejected, or at minimum becomes “no new money”, if it fails any of these:
👉 AI / technological disruption risk
If AI or another technological shift can plausibly commoditize the core product, eliminate the economic rent, or substantially weaken the moat over 10–20 years, the company fails. I want AI to be neutral, helpful, or demand-creating.
👉 Poor management
Weak execution, questionable incentives, unreliable guidance, poor governance, bad succession, accounting concerns, unwillingness to acknowledge mistakes.
👉 Poor capital allocation
Value-destructive M&A, expensive buybacks, chronic dilution, uneconomic capex, empire building, or persistent failure to convert operating success into per-share wealth.
👉 Secular business challenge
The core economic engine is shrinking, losing relevance, being substituted, losing pricing power, or facing an unavoidable structural decline. Temporary difficulty is acceptable. Structural deterioration isn’t.
👉 Insufficient long-term earnings power
I want a credible path to approximately high-single-digit or better EPS/FCF-per-share growth through a cycle, including dividends where relevant. A great balance sheet and cheap multiple aren’t enough if intrinsic value barely compounds.
👉 Excessive risk relative to prospective return
Binary outcomes, excessive leverage, extreme cyclicality, geopolitical dependence, regulatory dependence, customer/product concentration or a very wide range of plausible outcomes can kill the idea even when expected IRR looks attractive.
👉 Excessive valuation
If today’s price requires heroic growth, flawless execution or an unrealistically high terminal multiple, I don’t buy. The important nuance is that valuation is usually a “not now” killer, rather than a permanent rejection. The other gates can be much more fundamental.
Only companies that survive those seven gates get assessed against my four pillars:
👉 Pillar 1 — Business Quality
Essential/increasingly relevant franchise, widening moat, strong culture/management, high returns on incremental capital, genuine FCF-per-share compounding.
👉 Pillar 2 — Resilience
Few narrow predictions required, many ways to win, adaptability, low entropy, positive stakeholder economics, ability to survive a future different from the one I forecast.
👉 Pillar 3 — Valuation & Return
Conservative five-year bear/base/bull returns; normally 12–15%+ base IRR, with 15–18%+ especially attractive for new Coffee Can capital.
👉 Pillar 4 — Portfolio Construction
Does it improve the whole portfolio? Diversifies existing regulatory/geographic/business-model dependencies, strengthens the Resilient sleeve and deserves its position size based on range of outcomes
👉 When do I sell?
Never. All of my positions are set and forget . I get out of the way and don’t unecessarily interrupt their compounding . Not everything will work and I’m fully cognizant of this. But what I also know is that power laws and positive assymetry is the holy grail in the stock market. All I need is to hit a couple of big winners.
🤖 Made with AI

$bats $BTI VELO Nicotine Pouches Receive U.S. FDA Marketing Authorization
FDA's Marketing Granted Orders included the following flavors and strengths:
VELO Mini Pouch 400 mg Crema 4 mg
VELO Mini Pouch 400 mg Lime 4 mg
VELO Mini Pouch 400 mg Orange Crema 4 mg
VELO Mini Pouch 400 mg Passion Fruit 4 mg
VELO Mini Pouch 2 400 mg Crema 4 mg
VELO Mini Pouch 2 400 mg Lime 4 mg
VELO Mini Pouch 2 400 mg Orange Crema 4 mg
VELO Mini Pouch 2 400 mg Cinnamon 4 mg
"Today's Marketing Granted Orders demonstrate the FDA's leadership in accelerating progress toward a Smokeless America," said David Waterfield, President and CEO at Reynolds American Inc. "With adult smoking rates below 10 percent for the first time in recorded history, science‑based decisions like this highlight the role that FDA‑authorized alternatives can play in driving further declines in cigarette smoking."
Source: Reynolds American
☕️can Portfolio Update - Oct 2026
11 bagger 🏆: Metlen
2 baggers 🥇: Fortinet, Semi ETF, Eurofins
+5.47% YTD
“Good investing is a minority sport, which means that in order to earn returns better than everyone else we need to be doing things different to the crowd. And one of the things the crowd is not, is patient.”
Source: Nomad Investment Partnership letters
$baba $payc $bats $bti $prx.as $tcehy $evo.st $evo $adyen $pdd $mytil.at $mtln.l $eden.pa $ftnt $mele $bidu $four $knos.l $erf.pa
🤖 Made with AI


2
12
1,141

Yannis Stamatopoulos retweeted

BILL ACKMAN: owning few stocks, permanent capital and why he loves X! Tune in to our podcast!
YouTube: youtu.be/T8nHLUlRGkg?si=z9tO…
Spotify: open.spotify.com/episode/2WC…
Apple: podcasts.apple.com/no/podcas…
#InGoodCompany
Power laws don’t care about your hit rate. They only care about the size of your winners 👇
‘Nvidia was one of the 476 IPOs in 1999. If all had gone to zero except for Nvidia, a portfolio of all those companies would still have beaten the S&P 500’.
Source: John Authers at Bloomberg - 1999 Vs. These IPOs Is Apples to Bowling Balls
1
449
Todd Ahlsten’s Parnassus Core Equity Fund initiated 5 new positions in Q3 2026:
$META — 2.3%
$TSM — 1.6%
$TJX — 1.6%
$AZN — 1.3%
$CTAS — 1.3%
- We initiated a position in TSMC, which makes the most advanced chips behind the AI build out
- We also initiated a position in Meta despite the rerate in September. So, the company announced advancements in their personal assistant Muse and reported good results relative to their model benchmarks. And even after the move at just 21 times forward earnings, we still feel like the price was attractive and think the company will continue to benefit here, especially relative to the other parts of the AI ecosystem.
- We initiated a position in AstraZeneca. AstraZeneca has one of the best growth profiles in large cap pharma, yet it trailed its peers by over 30 points over the prior year. At 15 times earnings we don't think the market's giving much credit to its pipeline. And this move also helps narrow our pharma underweight.
- Next, we have Cintas. It's the leader and most skilled uniform rental provider has a route density that's very hard to replicate. It's lagged the market overall, and we think that the growth runway is not fully reflected in its current valuation.
- And lastly, TJX. So, this is the off-price leader its stock fell 20% in just a month on slowing growth and macro concerns. And at the time, it traded below 22 times forward earnings. We didn't see any sign of lasting brand damage. And, you know, we don't need to underwrite a return to peak growth or peak multiple to generate attractive return here. So, we took the opportunity to initiate, some exposure in in off price, which has historically been a very attractive category
Source: Parnassus Q3 2026 Core Equity Fund Portfolio Update.
🤖 Made with AI
