



Pinned Tweet
The massive bull case for $NBIS (Nebius) which most will not see coming : Enterprise ROI 🤯
Right now, enterprises using closed source behemoths (Claude Opus, GPT-5.5) for day to day automations / operations are the equivalent of dropping a F1 turbo engine into a Toyota Corolla to drive to work. It's a massive, expensive overkill.
(1/4)

Let me tell you exactly what will happen to $NBIS demand in the next few months.
- open source models will become really good for coding
- millions of developers will seek lower cost alternatives to Claude Code and OpenAI Codex because they are currently spending billions on them and see real value but need to start being cost-efficient
- demand for companies like Nebius that provide the full infrastructure that's just ready to use and start building instantly, easily and at a fraction of the cost will 100x again
B Kad retweeted

#NBIS Weekly #3
WE LIVE. COME JOIN US IN PAIN.
youtube.com/live/WXvpqj-P1b8…


Ever wondered what $NBIS Token Factory could be valued at if we carved out just that piece of $NBIS and valued it at competitor parity with players like Fireworks and Baseten?
Same managed inference, dedicated endpoints, post training, fine tuning, custom models and enterprise/agentic orchestration features but backed by Nebius’s own full stack AI cloud, their own physical infrastructure and rapidly expanding hardware capacity at that.
Let's start with the math shall we.
COMPETITOR BENCHMARKS:
- Fireworks: 40T+ tokens/day, $1B+ annualized revenue, $17.5B last closed valuation and reportedly discussing $30B - $40B.
- Baseten: approximately 40T - 50T tokens/day, reportedly $1B+ annualized revenue, $13B last closed valuation and reportedly approached at approximately $26B.
- Together AI: approximately 13T tokens/day, more than $1.15B in annual bookings and an $8.3B valuation.
Now compare that with $NBIS Token Factory.
The publicly visible number is only around 50B tokens/day through OpenRouter.
But Prosus alone has disclosed Token Factory workloads of up to 200B tokens/day through Nebius dedicated endpoints.
And this is where the public numbers can badly understate the real business.
Baseten shows roughly 368B tokens/day through OpenRouter, but says it processes 40T–50T tokens/day overall. (Based on Data recorded on 26th - 27th Oct)
That means OpenRouter may represent less than 1% of Baseten’s actual production volume.
If Nebius $NBIS has a similar public-to-private traffic ratio, its 51B visible tokens could imply roughly 3T-7T total tokens/day across serverless, dedicated endpoints and private enterprise workloads.
Again that is an estimate, not a disclosed Nebius figure but it means Token Factory may already be at 6%-15% of Fireworks/Baseten scale despite only launching in November 2025.
THE REVENUE MATH:
Fireworks produces $1B+ in annualized revenue from 40T+ daily tokens.
That implies blended monetization of approximately:
$1B ÷ 365 ÷ 40T × 1M
= approximately $0.068 per million processed tokens.
The formula is:
Annual revenue in billions
= 0.365 × daily trillions of tokens × net revenue per million tokens.
If $NBIS Token Factory reaches 45T tokens/day and monetizes at $0.08/M:
0.365 × 45 × $0.08
= approximately $1.31B ARR.
At 50T/day and $0.09/M:
0.365 × 50 × $0.09
= approximately $1.64B ARR.
Apply competitor-parity multiples of 20×-24×:
- $1.31B × 20-22× = $26B-$29B
- $1.64B × 22-24× = $36B-$39B
That gives Nebius $NBIS Token Factory a reasonable three year competitor parity valuation of approximately $30B-$40B.
So what should Token Factory be worth TODAY?
Take a $35B midpoint three-year parity value and discount it at 30% annually:
$35B ÷ 1.30 ^ 3
= approximately $15.9B today if competitor parity were guaranteed.
But it is not guaranteed, so I'll probability weight it:
- 60% probability of competitor parity: $35B
- 30% probability of partial success: $10B
- 10% probability of major underperformance: $2B
The calculation:
(60% × $35B + 30% × $10B + 10% × $2B) ÷ 1.30 ^ 3
= ~$11B today.
That gives me a, risk adjusted CURRENT standalone valuation with a slight bullish bias of:
$8B-$12B for Nebius $NBIS Token Factory.
My midpoint is approximately $10B–$11B.

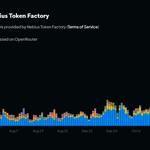
Velocity matters. After a few of us devs explicitly pushed for public endpoint prompt caching on X, $NBIS Token Factory finally shipped it within months and the Open Router volume has gone instantly parabolic (scaling past 80B daily tokens just today). Get ready for $NBIS Token Factory to now take a massive chunk of public endpoint Open Weights Tokens processed from competitors like @FireworksAI_HQ & @togethercompute
Raw serving performance like Latency/TTFT and TBT or Tokens per Minute/Throughput was never the blocker for $NBIS Token Factory. Without public endpoints having input prompts with cached pricing user cost bottlenecks alongside Token Factory simply not being picked as a default routing option on routing platforms like Open Router, $NBIS Token Factory for sure had a massive impact to its true potential token volume as I have highlighted plenty of times before.
That single engineering friction point was holding back production grade volume from providers like Open router, Vercel AI Gateway and more. With $NBIS closing the feedback loop and delivering this as fast as they just did, the instant usage spike on Open Router to $NBIS Token Factory speaks for itself. Keep and eye on this chart as this will continue to balloon.
Software + Hardware Infrastructure execution doesn't get better than this. $NBIS

Why does the $NBIS stock valuation not clearly show this?
First off Token Factory is buried inside Nebius AI Cloud and it's trading in the public markets which are more short term sentiment driven than the overtly euphoric far too forward looking private markets.
Plus Nebius does not separately disclose Token Factory revenue, ARR, gross margin or total enterprise token volume which if disclosed would make a significant difference to how $NBIS itself is valued.
Public OpenRouter data misses most dedicated/private workloads.
The market still largely values $NBIS as a capital intensive GPU cloud rather than assigning Token Factory a Fireworks/Baseten style inference multiple although players like Fireworks/ Baseten are the ones who will be squeezed far more than $NBIS is a massive physical compute shortage which it seems like we are in.
At a ~$45B total $NBIS market cap, an $11B Token Factory would represent only around 23% of Nebius.
Though Token Factory could become one of the highest multiple assets inside the entire Nebius group.
THE TOP END CASE/ POTENTIAL:
If Nebius $NBIS becomes a category leader rather than merely reaching competitor parity:
70T tokens/day × $0.11/M × 0.365 = approximately $2.81B ARR.
At 22×–25× ARR:
$2.81B × 22–25× = approximately $62B-$70B.
That makes $60B–$80B my credible three year top end for Token Factory though it will take a lot of work for Nebius to get there which I am confident they will.
A $100B+ blue sky valuation becomes mathematically possible at approximately 90T tokens/day, $4B+ ARR and a sustained premium multiple but I would not make that the core case considering how wildly different public market valuations tend to be compared to current day private markets.
Why could $NBIS still seriously reach these volumes?
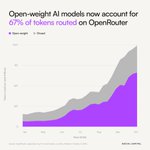
- OpenRouter token volume has grown approximately 250× in under two years.
- Agentic workloads can consume 5×-15× more tokens than ordinary chatbot interactions as we all know now.
- Token Factory production inference workloads more than tripled in Q2.
- Nebius controls the infrastructure instead of depending entirely on rented third party capacity which is a massive advantage in a supply glut.
- Eigen AI added model, kernel and inference optimization, Clarifai adds orchestration and system level optimization, Inferize targets cold starts, elasticity and GPU utilization. This acquisition pipeline just shows the amount of Focus Nebius as a company has towards optimizing Token Factory to the best of its potential. All these acquisitions happened within a span of months and this can easily continue.
- Nebius already ranks as the fastest inference providers on several major open models as per Artificial Analysis.
The remaining challenge is converting raw speed and infrastructure ownership into Fireworks/Baseten level reliability, enterprise adoption and recurring revenue.
This is the real $NBIS Token Factory thesis:
Current bullish value: $8B-$12B Three year competitor parity: $30B-$40B Credible category leader top end: $60B-$80B
The market is currently treating Token Factory like an optional feature attached to the Nebius GPU cloud and when the markets realize it's true potential there is a significant chance of the stock rerating.
If Nebius at some point starts disclosing Token Factory ARR, total enterprise tokens and dedicated endpoint growth, the market might be forced to value it as an inference platform instead.
This could then absolutely be the next rerating event for $NBIS.
Finally this is personal math and it' not unlikely for me to make mistakes. Please feel free to correct me if you think otherwise. And finally these are merely estimates and none of this is to be considered as financial advice. NFA
B Kad retweeted

damn, this is the most natural sounding AI model i've heard

We believe voice is the most natural way to interact with intelligence, so we created Dessa, the most authentic full-duplex speech model ever built. Talking with it feels like talking with a person…full of emotion, nuance, pauses, and a natural cadence.
block.xyz/dessa

Velocity matters. After a few of us devs explicitly pushed for public endpoint prompt caching on X, $NBIS Token Factory finally shipped it within months and the Open Router volume has gone instantly parabolic (scaling past 80B daily tokens just today). Get ready for $NBIS Token Factory to now take a massive chunk of public endpoint Open Weights Tokens processed from competitors like @FireworksAI_HQ & @togethercompute
Raw serving performance like Latency/TTFT and TBT or Tokens per Minute/Throughput was never the blocker for $NBIS Token Factory. Without public endpoints having input prompts with cached pricing user cost bottlenecks alongside Token Factory simply not being picked as a default routing option on routing platforms like Open Router, $NBIS Token Factory for sure had a massive impact to its true potential token volume as I have highlighted plenty of times before.
That single engineering friction point was holding back production grade volume from providers like Open router, Vercel AI Gateway and more. With $NBIS closing the feedback loop and delivering this as fast as they just did, the instant usage spike on Open Router to $NBIS Token Factory speaks for itself. Keep and eye on this chart as this will continue to balloon.
Software + Hardware Infrastructure execution doesn't get better than this. $NBIS

Cached tokens are now live on Nebius Token Factory⚡
Reusing context across requests?
Cached input can help reduce costs. See cached-token usage in API responses and billing, with pricing per model.
More info: docs.tokenfactory.nebius.com…

B Kad retweeted
For anyone that missed the $NBIS weekly last night
I konw it was a late one!
youtube.com/live/ILSpO184V_k…

I didn’t notice anyone diving in deep into this new $NBIS credit facility, so here’s exactly the mechanics of the said bridge loan that is very creative capital engineering from $NBIS All the while the rest of the AI cloud and neocloud space is getting crushed by high financing costs, balance sheet anxiety & sudden tight capital markets
$NBIS just pulled off a $3.5B senior secured credit facility with Citi. First off accessing this level of institutional liquidity without needing any immediate asset level contracts locked up is to me a a massive win that separates $NBIS from it's peers who is currently dragging $NBIS down. Let's dive deep in to how exactly this credit facility work, why management chose this structure and what the end game looks like.
1/ How the 364 day "credit line" work:
This isn't an amortizing loan where $NBIS starts dumping principal cash right away. It functions as a flexible bridge credit line. They draw funds as needed to build data centers and procure GPUs. The entire $3.5B principal sits as a hard lump-sum deadline at the end of the 364 days.
2/ The 90 day step up pricing structure
The baseline interest starts at Term SOFR + 2.75%. To prevent $NBIS from treating this short term bank facility as permanent capital, Citi built in a step up penalty. Every 90 days the borrowing margin ticks up by 25 bps until it caps out at SOFR + 3.50%. Still $NBIS has the flexibility to prepay and exit the loan at any time with zero prepayment penalty.
3/ Why would $NBIS takes on short term bridge debt all of a sudden right now?
Right now speed of bringing compute online is everything. Demand is scaling so fast that the return on getting physical clusters online immediately far outpaces a temporary ~3.5% spread over SOFR. Rather than spending 6 to 12 months negotiating slow, complex project finance debt up front, $NBIS takes rapid bank liquidity to capture hardware immediately which now has absurdly low payback periods. (Short term spot between 6 months - 1 year)
4/ The sequencing plan
Management explicitly calls this "sequencing" capital. First, they use the $3.5B Citi bridge line to acquire GPUs and bring up clusters. Second, they attach these active sites to their pipeline of long term hyperscaler contracts (backed by over $40B in deal interest with $35B of that non optional). Once the sites are operational and cash flowing, $NBIS swaps out this bridge facility for long term, even lower cost asset backed securities (ABS) before the 364 day clock expires.
Bottom line: Thus this would have a near 0 impact on the balance sheet. It's an aggressive tactical play to capture market share today where the demand is beyond absurd.

$NBIS SECURES $3.5 BILLION FINANCING FACILITY FROM CITI
Nebius announced a new senior secured credit facility to fund its global AI data center expansion and GPU purchases.
The facility has a 364-day maturity, with interest starting at SOFR + 2.75% and potentially rising to SOFR + 3.50%.
Nebius has more than $40 billion in long-term contracts with investment-grade customers, which could support additional asset-backed financing as it expands AI capacity in 2027 and beyond.


$NBIS end goal is more apparent than ever now. They are trying to not simply be a hyperscaler but the full stack alternative to the frontier labs going head to head against them. This will be their pavement to be a trillion dollar giant not another 100000 Blackwells. $NBIS is embedding themselves more deeply into each and every single piece of the open weights stack than most imagined:
PyTorch Foundation: Officially joining as a Platinum Member directly influencing upstream runtime & distributed kernel optimizations. (Read the attached article from Pytorch to understand how deeply $NBIS is being tied to the open source ecosystem and how deeply their co-engineering goes)
vLLM Engine: I met a gentleman who is now a $NBIS fellow in one of the $NBIS developer events who was a part of the original vLLM team And frankly I don’t think he’s the only one. For those who don’t know vLLM the default at scale model serving engine in the market.
LangChain: One of $NBIS customers serving as the core ecosystem powering high throughput production agentic systems.
NVIDIA, Hugging Face & Reflection AI: We all know about how interconnected these are to the open source ecosystem and $NbIS.
While traditional hyperscalers push proprietary walled gardens, $NBIS is co designing anything from bare metal compute to serving infrastructure including serving engines which are high level inference software to agentic infrastructure with the leading players of each layer while the rest of the so called Neoclouds that are tied to the same basket as of $NBIS are still trying to figure out setting up liquid cooled racks.
“Nebius’s Applied AI team contributes inference and post-training optimizations to open-source projects, and its open-source work has been incorporated into the PyTorch Ecosystem. As a Platinum member, Nebius plans to contribute to PyTorch and vLLM performance on the latest hardware platforms and share what it learns from running inference and post-training at production scale.”
-PyTorch
Anyone who still claims $NBIS to be a Neocloud please point out any other company in the said basket that does anything remotely similar.
Source: pytorch.org/blog/nebius-join…

FinX is making wild conclusions over short term $NBIS spot ticks to the upside and downside claiming H100 spot crashes (-80%+ within the last 7 days) mean weak demand while $NBIS Blackwell (B300) spikes signal the opposite. My personal research on spot data confirmed the fact that these short term trends are a fundamentally broken metric for drawing utilization and demand conclusions directly while theirs creative ways to use this data to estimate utilization in different ways.
Dynamic spot pricing was brought online by $NBIS just weeks ago on October 8, 2026 $NBIS dynamic spot pricing updates every 15 minutes between a fixed floor ($0.79 - $0.99) and a ceiling ($0.01 below PAYG). These swings track marginal preemptible pool pressure and localized spare capacity not overall $NBIS fleet utilization. A cluster can have 90%+ enterprise contracts or cloud reservations locked in while a regional spot pool sits at its floor. This distinction is crucial though this data can be leveraged in sophisticated ways to map real demand.
Short term spot volatility as a trend doesn't mean much while this market is still finding its footing. The real alpha is what the extremes reveal: US Blackwell demand is exceptionally high with B300 spot hugging its $9.49 ceiling (leaving just a $0.01 discount vs. $9.50 PAYG). This highlights massive pricing power and regional arbitrage. Plus these data points reveal the likely decisions that $NBIS will make in the year ahead in terms of pricing and capacity. Such are,
1/ Prioritizing securing new capacity in high demand US pockets with less focus on the European regions.
2/ Optimizing region specific pricing structures which could lead to region specific price hikes on PAYG or Reserved rates.
Over the last few days of my research I’ve been building a better way to estimate broad utilization by conjoining data from parallel cloud platforms with $NBIS data.
For anyone trying to do the same here is a tip to start with extracting longer term pricing data instead of trying to scrape UI charts and store short term 7 data pricing trends. $NBIS has a unauthenticated public API endpoint directly for this data: [api.nebius.cloud/billing/v1a…](api.nebius.cloud/billing/v1a…) (and use /spot-price/list series with startTime filters and granularity=GRANULARITY_HOUR to pull clean historical data well beyond the 7 day UI limit).
If you wanna know anything further on setting this up to use the unsecured endpoint for extracting and modeling data beyond 7 days, reply down here or send me a message and I’ll walk you through it.
I am still continuing the said research to estimate regional utilization bounds conjoining $NBIS spot pricing data with competitor spot pricing methodologies and hierarchical modeling to avoid false precision. Stay tuned for the next deep dive thread to see the results.


B Kad retweeted

Introducing Nebius Customer Atlas: mapping 302+ companies using Nebius - from Base44 and Cursor to Porsche, Revolut, Google DeepMind and Mastercard.
➡️ nebiusatlas.com
I built it after finding dozens of customers Nebius had never publicly announced. So far it's surfaced 126+ undisclosed customer relationships!
Base44 (Wix) uses Nebius for LLM calls. Baptist Health runs agents on AI Cloud. CAVA uses Tavily in its production agent. Orbiq moved to Token Factory after a Mistral outage.
Together they reveal a super broad customer base spanning training, inference, agent search, robotics, financial services, drug discovery, and more.
$NBIS has said it likely won’t do another mega-deal. That makes tracking customer growth one of the best ways to understand the business between quarterly results.
If you know of any Nebius customers I've missed, I'd love to hear about them.

B Kad retweeted

We keep improving performance across Claude, and you may have noticed it starts responding sooner!
Claude Code now gzips the conversation it sends on every turn, so it reaches the model faster. Cloud sessions also start up as soon as you start typing.

This SemiAnalysis report shows a vulnerable spot $NVDA has in the inference market and how they are countering it. I will explain how well positioned $NBIS and $CRWV are in compared to anyone else in the industry in a time where these two are getting immense hate in the market due to Datacenter Capex alongside why from a technical standpoint is $NVDA forced to do this favouritism and vice versa where they absolutely need a player like $NBIS
We touched this point a bit on Nate’s stream during our first ever Nebius Weekly (Linked Below): $NBIS and $CRWV are in the most advantageous position compared to hyperscalers, frontier labs, and rival neoclouds. While these two face CapEx and debt related pushback now, $NVDA needs these two and more such players for Nvidia to succeed which will guarantee that these two specifically avoid future Nvidia pricing taxes or gpu availability bottlenecks.
We’ll dive deeper into the $NVDA vs. ASICs debate in upcoming weekly episodes with @EndicottInvests and @SMASIMHO , but here is a concise breakdown on this in the meantime.
1/ The ASIC Threat to General Purpose GPUs in Inference:
ASICs (TPUs, LPUs, custom silicon) strip out general graphics pipelines and programmable overhead to maximize raw matrix multiplication efficiency, rendering them far superior in performance per watt and TCO for specific inference workloads. As ASICs capture market share in inference, $NVDA needs really well aligned, highly loyal players to defend its hardware and software footprint. Which in this case are $NBIS & $CRWV
2/ Open Source Inference & The Unified Layer:
Though more efficient, custom ASICs create fragmented developer ecosystems with vendor locked compiler stacks. Yet to counter these ASiICS on Hyperscaler clouds $NVDA needs unified streams to capture market share in anyway possible. That’s where primarily $NBIS (The inference leader in this sector) comes in with their managed inference and cloud alongside $CRWV as well more recently. This is immensely valuable to $NVDA to dominate the open source inference market thus $NVDA success in that lane will be directly tied to players like $NBIS giving them guaranteed priority and safety by $NVDA
3/ The Sovereign Protection Dynamic:
Recent market panic over $CRWV debt ignores all this. $NVDA holds stakes (~10%) in both companies and shares deep engineering integration with them. Crucially, $NBIS and $CRWV remain strict $NVDA only buyers, avoiding $AMD or alternative ASICs for the visible future. As SemiAnalysis highlights, $NVDA rewards absolute loyalty while penalizing multi vendor platforms every way they can might that be these type of events or prices or priority when it comes to gpu delivery. In a hardware constrained market $NVDA will aggressively protect and prioritize allocation for its pure play partners over anyone else and even backstop and prioritize in making sure these 2 players succeed over anyone else.

SHOCKING: We have confirmed that multiple Neoclouds have been refused access to GTC Berlin due to them adding AMD GPUs, TPUs, and other chips to their cloud offerings
Note that this doesn't apply to hyperscalers, as they have more buying power. But for neoclouds, executives feel NVIDIA has been using high-pressure tactics to keep them NVIDIA-only.
As such, neocloud executives are starting to consider offering TPUs or AMD GPUs quietly to avoid getting pressured by NVIDIA and to avoid the feeling that NVIDIA will retaliate.
nitter.cf/SemiAnalysis_/status/2…

Here’s the link to the first ever Nebius weekly if you haven’t already watched it 👇
youtube.com/live/HQ4p_a6EpNM…

B Kad retweeted

Thank you to everyone that tuned into our inaugural $NBIS Weekly Stream today!
@EndicottInvests, @BKad2005 and myself had such a great time shooting the shit with y'all, we ran way over time.
We'll be going live each Thursday at 7PM EST!
Stream recording in comments 👇

B Kad retweeted
$NBIS Weekly #1
Live in ONE HOUR
LFG
youtube.com/live/HQ4p_a6EpNM…

Turns out typing paragraphs about $NBIS wasn't enough, now I actually have to use my voice.
Our boy Nate @EndicottInvests myself and The Nebulizer @SMASIMHO are kicking off something the $NBIS community has been missing for a long time.
Pull up tonight at 7pm EST we’re gonna talk some $NBIS at a time when we all need a little extra conviction.

$NBIS NEBIUS WEEKLY #1 COMING AT YOU🔥🔥
FEATURING @SMASIMHO & @BKad2005
Now this might be the worst time ever(or best) to get this going but I wanted an avenue for peeps to get A LOT of value without a paywall or subscription you have to pay for
Just a Youtube account!
The long term goal is to bring on subject matter experts in the space, other $NBIS investors and maybe even have the ability to interview executives in the AI space.
All with the goal of being able to better understand your Nebius investment and what is playing out in the space.
We will discuss all Nebius related news + AI related news every single week.
We'll see how it develops over time but excited to get this started! :D
First Episode is LIVE tonight at 7pm EST. Link below.
SEE YOU THEN
