

Investor @ Macro | AI Infra | Bitcoin | "New Joule Order"
Tampa, FL
Joined February 2013
- Tweets8.4K
- Following2.4K
- Followers1.4K
- Likes9.2K
Pinned Tweet
The US and its markets are priming for the greatest run in history. I’m literally shaking.
Bit Whitman retweeted

With the Sept monthly close, the remaining confirming factors for a new Bitcoin Cycle are now in.
The slightly early Cycle Low (44 months vs 47), and lack of deeper move in June/July sets up a possibility of a Cycle that could well (upside) surprise. Versus say the diminishing return idea.
But, don't forget that new Cycles (in all assets) generally have one major shakeout, the type to give bears hope, one more time.


Hallelujah if this has legs

This is AMAZING NEWS!!
The Department of Education will start tying federal student loan eligibility to graduate earning outcomes.
Under the rule:
> undergrad programs must out-earn high school graduates and
> graduate programs must out-earn undergraduate programs
This is going dismantle many BS predatory college programs.
A would be win for the future of American students!

GP delivers 🔥

$IREN
Unlike the Goldman Sachs conference, where Dan Roberts declined to speculate on the potential ARR embedded in IREN’s 2027 roadmap, Kent Draper was much more explicit in the @McnallieM interview.
He basically handed us the inputs and told us to pull out an envelope:
Kent Quote:
“We haven't specifically guided to a 2027 ARR target, but all the building blocks are there.
We mentioned where we've been contracting today: $23 million a megawatt. In terms of 2027, we have 500 megawatts of IT load expected to come online. We are seeing upward pricing pressure... so it's relatively easy to do some back-of-the-envelope calculations and work out where this could go."
For anyone without an envelope handy, let me do the math for you:
500MW-IT of incremental 2027 capacity × $23M of ARR per MW-IT = $11.5B of incremental ARR.
The key word is incremental.
That ~$11.5B is the annualized revenue potential from the 500MW of new IT capacity expected to come online in 2027. It would sit on top of the $4B+ ARR associated with the 2026 roadmap.
Kent also explicitly said pricing is seeing upward pressure, so $23M/MW-IT may not even be the ceiling.
No, IREN has not formally guided to $11.5B of incremental 2027 ARR.
But this is about as close as management can get without actually putting the number on a slide.
And I think Kent’s confidence has less to do with squeezing another couple million dollars of ARR out of each MW in pricing than it does with what I believe is the much bigger embedded sandbag in the 2027 roadmap:
PUE.
Wait, what?
Yes, PUE!
One of the most important changes in IREN’s latest roadmap is that management is now talking in IT MW, not just gross facility MW.
On the prior earnings call, the 2027 roadmap was roughly 730MW gross. The latest framing is ~500MW-IT.
Using the disclosed site mix and reasonable PUE assumptions, the bridge looks roughly like this:
NVIDIA 60MW Air: 60MW / 1.37 PUE = ~44MW-IT
Childress 190MW Air: 190MW / 1.37 = ~139MW-IT
Canal Flats 30MW LC: 30MW / 1.50 = 20MW-IT
Horizon 5–6 LC: 150MW / 1.50 = 100MW-IT
Sweetwater 1: 300MW / 1.50 = 200MW-IT
That gets you to:
730MW gross → ~503MW-IT
Which is almost exactly the 500MW-IT management is now guiding to.
Here’s the catch:
@danroberts0101 acknowledged on the earnings call that IREN has been deliberately conservative with the headline PUE assumptions it uses for these deployments, including the 1.5 PUE currently applied to liquid-cooled capacity.
And that matters.
I find it very hard to believe Sweetwater 1 (or frankly Horizon 1-4), or any future NVIDIA DSX AI Factory, operates anywhere near a 1.50 PUE.
IREN hasn’t disclosed what the actual operating PUE could be, so I’m not going to pretend we know the answer.
But for context, NVIDIA’s own Omniverse DSX Blueprint documentation uses a 1.20 PUE base case in its example dashboard.
That is a huge difference.
Because if gross power stays fixed but actual PUE comes in materially below 1.50, the amount of revenue-generating IT MW goes up.
And not by a little.
Take Sweetwater 1:
300MW gross / 1.50 PUE = 200MW-IT (guidance)
300MW gross / 1.20 PUE = 250MW-IT
That’s an extra 50MW-IT from the exact same 300MW gross power.
At today’s contracted pricing of roughly $23M ARR per MW-IT, that incremental 50MW-IT would represent:
50 × $23M = $1.15B of additional ARR
Same site.
Same gross megawatts.
50 more revenue-producing IT megawatts.
Now apply the same math to Horizon 5-6 and Canal Flats.
That’s why I think PUE will be one of the most underappreciated upside levers in IREN’s 2027 roadmap.
And it doesn’t stop with simply outperforming the conservative design PUE assumptions.
IREN has other levers it will pull to unlock even more revenue-generating IT capacity from the same underlying power footprint:
1.Liquid-cooling Prince George and Mackenzie.
Those sites are currently constrained by air-cooled infrastructure, which limits how much of the gross power can actually be converted into IT load. Moving more capacity to liquid cooling will allow IREN to push closer to the sites’ gross power ceilings.
2. NVIDIA DSX power-management tools, including Max LPS.
These tools will potentially allow them to oversubscribe megawatts because GPU clusters don't constantly pull their max power 100% of the time, simultaneously.
And on to my broader point.
The 500MW-IT 2027 roadmap may look like a fixed number, but it isn't!
If PUE comes in better than the conservative assumptions, existing sites are pushed closer to their gross power limits, and DSX enables better utilization of that power, IREN could end up extracting far more IT MW from essentially the same gross megawatt footprint.
At ~$25M of ARR per MW-IT, every additional 10MW-IT is worth roughly $250M of ARR.
Yuge! 🤯
So when Kent says the building blocks are already there to form a 2027 ARR target, I think there may be more embedded in those blocks than the headline 500MW-IT suggests.
(Great interview Bryce and Anthony!)
(holy shit this went longer than I expected, I hope this post makes @franklee6924T proud)

Bit Whitman retweeted

The state of $IREN according to CEO Dan Roberts. The common thread: Execution. The next 18 months will be all about execution. If $IREN executes, the multiples will soar and the stock will be re-rated.
1. Investors are becoming immune to $20-40bn mega-deal announcements. They understand why the deals get done: for customers, a cheap call option if the neocloud delivers before the termination date. For emerging neoclouds, the announcement raises the capital to launch. Both rational. What matters is commissioning actual capacity. Execution > announcements.
2. The forward-contracting question has flipped 180 degrees. Not long ago it was "wen deal". This week: how long can you hold your capacity available. The structural point is being understood: only half a dozen companies in the world can contract capacity 12-18 months ahead of commissioning. Every month closer to delivery, that universe expands, and capacity allocation becomes a strategic and economic decision rather than a funding necessity.
3. Nobody asked about colo. A year ago it was every 2nd question. ~3 year paybacks on the full stack, with customers and lenders funding >100% of the GPU cost, seems to have settled it.
4. Everyone's watching execution. Operators deciding who to join. Customers deciding who's reliable. Lenders deciding who to back. Execute well and all three compound for you. Struggle, and they compound against you. Us included.
5. The biggest debate on our stock: the gap between $71m of quarterly AI Cloud revenue and $1bn of ARR operating, $4bn contracted for year end. Is it real, and will we deliver. Some disappointment with last quarter traces to ramp assumptions that ran ahead of anything we guided. That's on us to manage better. Specific sites, tighter windows.
6. Most direct question of the week, and the fairest: can you operate cloud at hyperscale, not just build data centers? It's the area we've been building hardest. Headcount roughly tripled in 12 months, with serious operators joining. Mirantis brought two decades of running production private clouds for enterprises like PayPal and NASA. The biggest test so far came back a pass: Horizon 1 delivered to Microsoft and accepted. More to prove from here.
7. One thing that came up in every meeting: we don't pay for GPUs until 30 days after they ship. Prepayments arrive at signing, lenders commit before delivery, the hardware bill comes last. The buildout is largely funding itself as it goes and the payment terms give us flexibility to hold capacity for a deeper customer base (see 2 above).
8. The enterprise wave is the one to watch (and really excites us internally). Enterprise AI needs virtualization, security, compliance and real support. Early conversations are starting. When that demand hits, software and services on the same MWs can expand margins materially.
9. The next 12-18 months are all about execution, and the delay chatter was constant. 3 sites commissioning between now and year end, 4,000+ people on the ground. We're in the spotlight, and it's delivery time.


Bit Whitman retweeted

$IREN
I won’t go as far as saying SemiAnalysis is full of shit, because I’ve actually suspected for several quarters that IREN may have some operational issues (particularly around uptime) that could be contributing to the softer than expected revenue prints.
But SA makes it *very* easy to get close.
For starters, IREN does not have a single GPU operational at Mackenzie today.
Not one.
The company explicitly guided on its earnings call that the 50,000 B300s going into Mackenzie (and Childress)would not begin coming online until Q4. So any analysis treating Mackenzie as currently deployed, operational, or contributing meaningful production data is starting from a fundamentally incorrect premise.
If you’re going to make serious claims about IREN’s GPU utilization, uptime, or operational performance, you first need to correctly identify which which sites are operational!
Come on man!
You cannot take capacity that hasn’t even been commissioned yet, mix it into the operating fleet, and then use the resulting numbers to argue that the company has an operational problem across British Columbia.
That isn’t a minor rating overisght. It puts into question their entire conclusion!
There may very well be legitimate questions to ask about IREN’s uptime, like I said, I have some of those same questions myself.
But if the TMZ of AI wants to make a credible case, it needs to start with getting their fucking facts straight.
(As of the earnings call, the only operational sites IREN has is 40MW at Prince George and Horizon 1 - hence the $1B operational ARR)

Bit Whitman retweeted

The Funniest Thing about ClusterMax 3.0
Much of X only knows like ~5 of the names on ClusterMax 3.0. I know a few more of them so I can point out how ridiculous some of these rankings are.
I used VastAI for my masters project because they are by far the lowest price. VastAI is a distributed GPU hosting network with a thin veil software support. Anyone can apply and put their GPUs on VastAI (1). Some of these GPUs are literally hosted in people's basements. Literally, if you put up their listings for RTX 5090, the top four recommended listings are GPUs hosted in Vietnam, Taiwan, Nebraska, and Estonia (2).
Now @SemiAnalysis_ ranks VastAI above $IREN and one tier below AWS. $CRWV and $NBIS are two tiers above AWS. This means I can plug in GPUs in my bedroom and be closer to AWS than AWS is to $CRWV and $NBIS on ClusterMax rankings. Hey but you know what? My home has a Generac Generator and Cisco CW9300 Enterprise Grade Switch. I'm now a tier above $IREN and only one grade below AWS.


ClusterMAX 3.0 is here!
ClusterMAX 3.0 debuts with a comprehensive review of the neocloud industry, covering 77 providers.
We increase our market view to cover 323 providers, up from 209 in ClusterMAX 2.0, 169 in ClusterMAX 1.0, and 124 in the original AI Neocloud Playbook and Anatomy article.
We have now interviewed well over 200 end users of neoclouds as part of this research.
We update our itemized list of criteria across 10 categories, and update our direct descriptions of our expectations for Slurm, Kubernetes, Standalone Machines, Monitoring Dashboards, and Health Checks. All of this content is live on our website. We encourage providers to use these lists when developing their offerings. We still consider these lists as an amalgamation of our experience interviewing end users, making them representative of the features that end users expect from their cloud providers.
Nebius joins CoreWeave in the Platinum tier. While CoreWeave still sets the technical bar for others to follow, Nebius is now established as a provider that consistently commands a premium pricing over others. Strong business decisions by Nebius have put them in a position to serve an entire class of neolabs at seller’s prices.
Google Cloud joins Oracle in the Gold tier. Azure moves to Silver, Fluidstack moves to Unavailable, and Crusoe drops to Bronze. Lambda, Firmus and TensorWave remain in Silver, while GMI moves up to Silver from Bronze.
Many companies drop from Silver (or Gold) to Bronze or lower. We raise the bar this round as only 19 neoclouds globally achieve a Medallion rating.
We establish a tier between Bronze and Underperforming: the Participation Ribbon tier. 15 providers join this rating, which more accurately describes our opinion that they do the bare minimum to get by.

Bit Whitman retweeted

@glenchernen you nailed it. The most misunderstood piece of $IREN is the power pipeline the Roberts brothers built while almost nobody was watching.
They had the vision in 2018 and spent years hunting sites globally. Here’s proof (photos by me) of how fanatical they were.
Photo 1: Will Roberts in the lobby of a prospective site, January 2020, right after Iris Energy (now $IREN) acquired PodTech in Canal Flats.
Photo 2: the multi-day massive snow blizzard we drove through looking for more of them.
Photo 3: for reference snow covered cars in my driveway
Nothing was going to stop them.


$IREN isn't complicated...Or...maybe it is 🤔
IREN is many things.
One of the most under appreciated or misunderstood things is its power pipeline. More accurately might be to say its undisclosed power holdings. How can we know this?
This is something only a few of us truly understand and we have learned this by observing every move of the company for years.
They incorporated in late 2018 but did not ipo until November 2021. Personally, I watched with only vague interest from the sidelines from around late 2019, when I heard about a tiny company with large ambitions that wanted to ipo. This was just as Covid struck Wuhan and the world was beginning to go into a mindless panic. I only heard they mined bitcoin, which didn't particularly interest me so it took at least a year of them trading before I acquired any, or even paid much attention. A few of my close friends were bitcoin nuts right from its inception and (are v wealthy) and one of them (a whale) was very very very excited about IRIS ENERGY. I thought he was still just being crazy. It turns out he was not very well informed about IRIS but that didn't matter because I began studying them and became an early fanboy under a pseudonym on stocktwits and eventually educated my friend who still holds all his shares.
They priced their initial shares at $28 right at "The Height of the "Crypto Bull Run":
IREN went public at the absolute peak of the pandemic-era tech and crypto bubble, driven by unprecedented retail investing and loose monetary policy."
Here is the nugget that you were waiting for but it requires faith in IREN and the founders, therefore a ton of research, and if it continues to pan out as I expect it to...a degree of luck. The thing about luck though is often hard work is confused with luck so maybe its just hard research and an unteachable 5th sense?
In my informed opinion, IREN is a misunderstood and massive power supply option. I have felt this way from the moment I made my first share purchase and it is unwavering.
After years of keenly observing the company, it is my strongest opinion that all the way back to incorporating in 2018 and all throughout Covid, that the Roberts brothers had an almost unmatched vision about what would unfold in the power markets. I shared that vision from back then as I watched the green warriors try to push everyone into a Tesla and force them outof their reliable gas powered vehicle.
In this time of panic, the brothers were busy travelling the globe in search of power assets for IRIS. Much of this is documented and should make a decent movie one day after IREN breaks a trillion market cap.
This is where it becomes interesting. Every once in a while, IREN discloses a new blockbuster MW/GW electrical site that is nearly full permitted.
These sites take huge effort to convert into real generating sites. The brothers don't seem to be particularly keen on disclosing the depth of their pipeline except to admit it is far larger than anyone knows.
What if its another 50GW?...or 100GW?...or 250GW?
Their cash generation flywheel is finally beginning to spin. We will learn of many more sites which they will be able to internally fund without debt.
1 trillion...here we come!

Are you still here, anon?

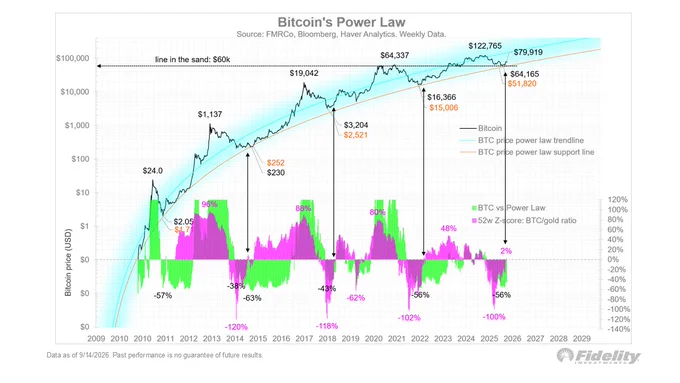
Finally, Bitcoin has been on the move after holding the $60k support zone for almost a year. That’s how long a typical Bitcoin winter lasts, so I’m sensing that a new 4-year cycle bull market is underway. Note that the Z-score of BTC/gold has turned positive after being -100%. In the past that has generally been confirmation of a bottom.
What does all of the above suggest? We are in a new secular regime of a higher cost of capital, which suggests that governments will respond with that oldest trick in the book: financial repression.
X will feed your ego for stock picks all day, but every once in a while, you should pay attention.
Brian tells a great story. They often begin far before anyone knew they mattered.

1/4
I have been trying to explain for a long time why $IREN is playing a different game. Credit to @mcF_dan for the inspiration for this thread.
When I first met $IREN co-CEOs Dan and Will in 2019, that was obvious. They didn’t know everything. What I could see was how fast they could learn. That is the rare part. Not a perfect map on day one. A learning rate fast enough to outrun the problems and still land exactly where they needed to be.
They built from first principles: secure the scarce physical layer first, keep as much optionality as possible, learn from people who had already been through it, then go further, way further than the starting playbook.
That is why the strategy can look slow if you only watch deal-by-deal headlines. In a tightening market, waiting can mean better counterparties and better economics. Don’t get lost in one contract. Watch the whole stack in the age of AI.


Pin it. Live it. Do it.

Before you say it’s not “fair” that you’re poor, answer these questions:
1. Do you save half of your income?
For my entire life, even when I was mowing grass for a living, I saved half of my after-tax income. How?
I didn’t have my own place. I didn’t have a TV. I didn’t have a cell phone. I drove a 1983 Honda Accord with 225,000 miles on it—a car I bought from a friend for $2,000 when I was 19.
I didn’t have a credit card until 2001, when I was 29. I didn’t have my own place to live until I was making more than $1 million a year.
I bought my first stock—Coca-Cola—in 1992, when I was 21. I bought my second stock—Amazon—in 1997, when I was 26.
Whenever I had excess liquidity in my checking account, I bought gold coins—almost every year—and I’ve never sold a single one.
I’m not a slave. I don’t save their worthless money.
2. Do you work every day of the week, at least 12 hours a day?
For the first decade of my career, from 1996 through 2007, I worked seven days a week, from 7 a.m. to 7 p.m. That didn’t include the reading I did when I got home.
I started taking weekends off after I had my first child. Even today, I still work seven days a week. I write every day.
This year, I’ve written a daily e-letter five days a week. I write two investment newsletters each month, and I’ve written two best-selling books.
I run a business with more than 100,000 customers and roughly 30 employees. I also recently had my fourth child and am building a new house in Winter Park, Florida.
I cook dinner for my family every night. That’s my hobby.
3. Did you get an education?
In America, anyone can become almost anything they want professionally in about seven years. If you don’t have valuable skills, go acquire them.
I got my first job in financial research by agreeing to work for free. I didn’t have a degree in finance or accounting, but learning the necessary skills wasn’t hard.
I used the library. I read every letter Buffett ever wrote. I read Rothbard, Hayek, von Mises, Bastiat, and thousands of SEC filings.
Use the library. Find a mentor. Today, it’s even easier because of the internet.
There’s no question that if you save half your income, work hard, and educate yourself, you can become financially independent. Is it hard? Of course. But it isn’t as hard as being poor and ignorant.
Here’s a big hint: No one can tell you how to succeed. And if you believe what they tell you, you will end up with only what they give you—nothing more.
You have to find your own path. If you do what everyone else does, you’re only going to get what everyone else gets.
I’m sure you can imagine what my friends and family said when I told them, after I got out of college, “I’m going to build the most respected financial advisory firm in the world over the next decade.”
I’m sure they thought I was nuts.
Finally, if you have a good income but never seem to build wealth, learn to use credit the right way. I constantly use low-cost credit to fund assets that appreciate—farmland, securities, my business, and real estate.
Poor people use credit to buy things. Rich people use credit to buy assets.
Remember what Ayn Rand said about the poor: “Don’t be one of them.”
There we go, Dan. 👏

Goldman's CommTech conference, San Francisco. 48 hours of @IREN_Ltd investor meetings, and the mood has shifted meaningfully.
Key takeaways:
Bit Whitman retweeted

It really just comes down to whether Bessent has enough ammo and willingness to keep things from normalizing to fair value or not


Absolutely no one was thinking this far ahead. You wanna bet against that vision, anon?
A story for the ages. $IREN


And then what happened….?

As someone who’s been through the peaks and doldrums of the Bitcoin market for 10 years, this seems like a great time to take a position/expand or DCA.
A bunch of metrics based investors will tell you that because vol has declined, bitcoin may not have eccentric and overheated bull markets going forward. I disagree. In each cycle since 2020 I’ve felt that new highs would undershoot expectations simply because retail expected it. Now that expectations are tempered this is the first time I’ve felt we have the potential to wildly overshoot any expectation. Also, the fiscal debt situation is finally reaching a point of no return that bitcoiners have hypothesized for many years. The Fourth Turning will almost certainly include Warsh/Bessent at war with the long end of the curve. Not many understand the implications of such a thing.
Lock in, fren. Game time is almost here. Will delete if wrong. bitcoin:native