

Helping 2,650+ eCommerce businesses thrive. Over $26M saved. 483+ accounts overturned. 30+ years of payment expertise to fuel your global growth.
Schedule your Consultation →
Joined May 2024
- Tweets448
- Following163
- Followers333
- Likes114





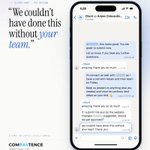
Another five stars for Compaytence, and thank you to our client for the kind words. 🤝
"They supported us throughout the entire process of setting up our payment processor." 💪
With a network of 30+ top-tier providers, our PSP Setup team handles the compliance and underwriting preparation that gets merchants approved with the right processor. Need to talk payments? Get in touch through our site.

Our Co-Founders Michael and Lars are heading to Rome next week for SiGMA World and Affiliate Grand Slam. 🌐
Both events run at Fiera Roma from Nov 2 to 5, with iGaming, nutra, dating, lead gen and telehealth businesses in the same building.
Michael and Lars are looking forward to four full days of meetings. If you'll be there and want to chat, come say hello! Booking link in the reply 👇


A live account can be frozen for paperwork that was fine two years ago. 🔒
It's called periodic review, and every regulated provider runs one. Directors change, addresses change, a passport expires, ownership shifts by a few percent. None of it matters until the review runs and the file no longer matches reality.
Keep it current: incorporation, ownership, IDs, proof of address, processing history. Update it whenever the company changes.
Refresh requests have deadlines, and missing one looks like evasion. ⏰
The data collected at checkout directly affects your auth rates 👉
CVV: verifies the security code
AVS / ZIP: confirms the billing address
Expiration: confirms current card details
Email: adds an identity and risk signal
IP and device: provides location and device data
3DS2: authenticates the buyer and can shift fraud liability
Give banks more data for a better chance of getting approved. 🚨


Our new website is live, and it opens with a number we're proud of: more than $26 million recovered for merchants. 🎉
compaytence.com has a fresh, modern design on every page. You'll find a real result next to each service, MyCompaytence one click away, and all 38 Google reviews and our case studies in one place.
While you're there, book a 30-minute call with our team. Link in the reply 👇


Holiday sales well above your usual volume can get your account frozen, even when every order is legitimate. 🚨
Risk systems flag deviation, and a spike in volume is deviation.
Then January brings the refunds and disputes, against December revenue you already spent.
Tell your provider what is coming, in writing, before it comes. 📩
Your busiest month is the most likely time to have issues with your provider. 📈
Six checks to run now, while they are still easy: send a volume forecast in writing, know your monthly cap and what happens past it, make sure customer service can keep up with order questions, and put the refund policy where checkout can see it.
Then switch on dispute alerts and set up a backup processor in case your main account is paused.
If your provider has your forecast before volume rises, the increase will not surprise their risk team. ✅

★★★★★ on Google. 💪
It's awesome to be recognized for going above and beyond the status quo.
Our work continues after an account is approved. We keep an eye on the setup, answer provider requests quickly, and step in early when a processor flags something.
Want a payments team that stays involved? Get in touch through our website. 🤝

Your new merchant account probably has volume limits nobody told you about. ⚠️
Most new accounts are boarded with a monthly volume cap and a per-transaction limit. If you hit the cap mid-month, the provider either holds your funds or declines transactions until the next month.
Those limits are based on the volume projections in your application.
If you forecast low to look safe, your limits may be set too low for your real volume.
If you forecast high without processing history to support it, your application is likely to be declined.
Forecast the real number, show the history that supports it, and ask what happens when you exceed it. Ask well before your best month arrives. 📈
Your best Q4 can be the reason your payouts stop.
A store that goes from 50 orders a day to 500 can look very different to an automated risk system.
That's when the document requests start. Sometimes payouts wait while the review runs.
A few of the triggers:
Business details that don't match your documents.
A restricted product on a general Stripe or Shopify Payments account.
Ads that promise more than the product page.
A chargeback ratio divided by last month's smaller volume.
Staying under a card-network threshold isn't enough. Your acquirer has its own limits.
Check your account before the volume comes.
Full breakdown in the reply 👇

All 10 triggers, what changed since last holiday season, and what to do if your account gets flagged anyway: compaytence.com/post/10-ways…

Agentic AI, fraud and regulation are this year's main themes at Money20/20 USA, the flagship event for payments and fintech. 🤝
Co-Founder Michael and VP of Sales Jake will be a part of those conversations, October 18th to 21st, at The Venetian in Las Vegas.
If you want to talk payments while we're in Vegas, get in touch through our website. 👉

“We couldn't have done this without your team.” 💪
Your website plays a major role in the payment processing approval process.
For this client, we restructured their site around the processor’s compliance requirements, resolved the issues holding up onboarding, and got them approved.
Website compliance often decides whether an account gets approved. 🤝

When international merchants want to sell in the U.S., there are two mandatory screening processes they need to navigate: KYB, and KYC.
For KYB, you just need the standard paper trail: an EIN, Articles of Incorporation, and a business address. Pretty straightforward.
KYC gets personal. You'll need a tax ID in your own name, a government photo ID, and proof of your home address.
The personal tax ID is usually the holdup. You can easily file paperwork for a company, but if you don’t have an SSN, getting an ITIN means waiting on the IRS’s notoriously slow timeline. ⏳
Chat with us on how to navigate these best 🤝
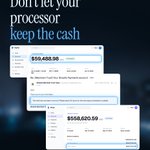
Your best month ever can end with a reserve.
A 10% rolling reserve held for 90 days:
$10 of every $100 you process, locked up.
And it grows with you.
Process $100,000: $10,000 held.
Hit $300,000 on Black Friday: $30,000 held.
All while earlier reserves are still waiting to be released.
What risk teams watch: sudden volume spikes, longer delivery times, preorders, rising refunds.
The fix starts before the spike.
Tell your processor before you 4X.
Full breakdown in the reply 👇

Rolling vs. fixed reserves, what triggers one, and four ways to lower your odds before peak season: compaytence.com/post/paypal-…

Don't treat your reserve as a punishment, treat it as a conversation. A reserve is the reply to the way you communicate with the bank's risk assessment.
You have control over what you're telling the bank, whether you know it or not. 👉
Six pieces move it: your website, your marketing claims, your customer due diligence, your routing and descriptor, your fulfillment proof, your chargeback rate.
If it's a conversation, then you control what you show the bank, and they will respond accordingly. 🗣️
Fix two, the number drops. Fix all six and the hold comes off.

Beautiful views in San Diego and a rooftop dinner to close out the event ☀️
Special thanks to our co-hosts @phoenixcommercetech and @shipvelocity, and to @commerceroundtable for bringing everyone together. This is the part of the job we like best: chatting with some of the best operators in ecomm.
Until the next one 🥂