

Beaumont-sur-Mer
Joined August 2015
- Tweets31
- Following50
- Followers852
- Likes136



The two riddles from $SIVE’s Q2 call:
-Six unnamed pluggable engagements — three evaluating alpha samples and three in technical/supply-chain assessment.
-One new unnamed foundry partner.
On the latter, one speculative candidate worth putting on the watchlist could be Global Communication Semiconductors, GCS.
To be clear: there is no disclosed Sivers–GCS relationship. This is a hypothesis, not a claim.
Still, several pieces fit unusually well.
GCS is a California-based pure-play III–V foundry with roots in RF, wireless and millimetre-wave semiconductors — an interesting overlap with Sivers’ heritage. It also has a long InP/optoelectronics track record and offers foundry services for lasers, SOAs and other photonic devices.
GCS has described both 4-inch and 6-inch InP capability, plus volume production, second sourcing and customer-proprietary process manufacturing. That matters because Sivers may need a partner capable of transferring and qualifying its InP100 process, not merely offering a standard PDK.
CEO Vickram Vathulya said Sivers had been engaged with the new partner “for a while”, that it was “extremely motivated”, and had “tremendous capacity allocation for Sivers” available now.
The geographic angle is also worth considering. VV spoke of long-term supply resilience, while Sivers’ manufacturing slide explicitly adds “multiple production routes” and “geopolitical flexibility”.
Sivers is expanding its own Glasgow line, expected to add capacity from Q4 2027. WIN Semiconductor provides the main external route from Taiwan. A California source could create a strategically attractive triangle: internal process control in the UK, Asian scale through WIN, and North American capacity closer to major US AI and defence customers — while reducing exposure to any single site, supplier or potential Taiwan Strait disruption.
That does not prove GCS. The same slide describes external foundry and chip-on-carrier relationships as “Asia+”, so the new partner’s location remains ambiguous.
I haven't found any clear Sivers–GCS link yet, and compatibility with the exact InP100 epitaxy, gratings, facets, coatings and array process remains unverified. So no smoking gun…. But GCS appears to be technically, geographically and strategically the best match I can come up with. At least until we get more clues in this case.
Next riddle: The six unnamed pluggable engagements.

While waiting for Sivers Semiconductors' next partnership announcement, I mapped out the full prospect universe around their Photonics division.
Six partnerships are already confirmed:
• GlobalFoundries $GFS — CPO/NPO laser partner
• Jabil $JBL — 1.6T LRO transceiver
• Ayar Labs — ELSFP laser arrays
• POET Technologies $POET — Optical Interposer + DFB
• Aeva $AEVA — LiDAR laser supplier
• O-Net — Laser array partner (Asia)
Beyond these, I count 23 companies with a logical connection to Sivers' InP CW-DFB laser arrays. The framework is straightforward: technical fit, existing relationship, confirmed test orders, featured in investor presentations, mutual research projects etc.
All together I tried to match and rank all these prospects in a straight up supply chain logic with estimated mature market revenue.
Some prospects in closer orbit:
Aeva — Already confirmed for LiDAR. Now expanding into AI datacenter optics with SOA-based architecture.
Nokia — Mutual board member (Karin Raj). Just acquired an InP fab for AI datacenter capacity.
Nubis/Ciena CIEN — Sold their own InP fab in 2016. Must source lasers externally.
Lightmatter — Indicated as test customer. Builds on the same GF SiPho platform.
See full map attached. Interested to hear which connection you guys find most compelling.
$SIVE

Seems like a lot of people get it wrong about
Sivers + Global Foundries SCALE = AMD.
It's not correct... It's much bigger than that ++++++
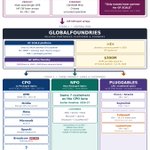
I mapped out the full GF SCALE ecosystem after today's GF Q2 earnings call.
Here's what most investors are missing:
GlobalFoundries is the ONLY OCI MSA-certified CPO platform. Every design on the platform requires external CW lasers. Sivers is the only named laser partner for GF SCALE.
Three product lanes — not just CPO:
CPO: AMD, Nvidia, Meta, Microsoft, OpenAI, Broadcom + an unconfirmed 7th(speculation in the map)
All active SCALE engagements confirmed today.
NPO: Same 7 customers above, same photonic IC, but earlier timeline (2026-27). GF´s CEO called it "an important application ahead of broader CPO adoption."
Pluggables: GF engaged with 4 of the top 5 transceiver players. Their roadmap to 1.6T and beyond is where Sivers' multi-wavelength arrays become critical.
...and more design wins taped out in Q2, another expected Q3 .
This isn't a one-customer story. It's a full platform play with 7+ engagements across three form factors — and Sivers sits at the top of the supply chain as the prime laser source.
Please check out the map and tell me if I got something backwards or needs to be clarified.
$SIVE $GFS $AMD
