
Data Engineer. Python & SQL. Small/Micro Cap Special Situations. SPAC Secondary Markets. Capital Management. Not investment advice.
Joined February 2024
- Tweets958
- Following105
- Followers532
- Likes420





Getty Images completed its SPAC merger in 2022, then refused to honor warrant exercises, citing unmet registration conditions. By the time exercises were permitted, shares had fallen below the $11.50 strike.
Warrant holders sued and won. Now Getty is pursuing Chapter 11 and seeking to wipe out remaining warrant litigation claims.
If successful, this could set a troubling precedent for SPAC warrant holders. Worth watching.
$TONT Graf Global filed S-4 today. BIG3 increased its valuation by $95 million at the last minute. On June 10, BIG3 informed Graf that it would not proceed below $290 million. This was just one day before board approval. No independent valuation or financial projections were reviewed.
sec.gov/ix?doc=/Archives/edg…
Interesting provision in Heroic Empire Acquisition Limited’s recently filed S-1: The SPAC can settle its $10,000 monthly administrative fees by issuing ordinary shares at $10 per share upon completion of its business combination, rather than paying cash.
sec.gov/Archives/edgar/data/…
The new S-1 filed today by Heroic Empire Acquisition Limited does not include the customary $100,000 dissolution expense provision. This could mean the SPAC would not deduct $100,000 from its trust account in the event of liquidation.
sec.gov/Archives/edgar/data/…
SPAC's switching from Nasdaq to NYSE during S-4 process for target shows a general disdain for SPAC's wanting to IPO on Nasdaq these days.

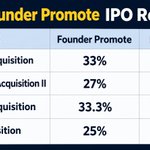
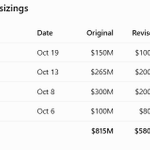
Institutional SPAC IPO investors may be pushing back against excessive sponsor promotes. The four SPAC offerings this month that were reduced all include promotes above the standard 20%.

DataTrack retweeted

The #SPAC market is showing renewed momentum, but the economics of getting a deal across the finish line have changed considerably.
With more SPACs searching for targets and more companies considering the public markets, the opportunity is definitely there. But the challenge is making sure the financing holds up when shareholders have the option to redeem.
A signed #merger agreement doesnt guarantee the cash needed to close.
In my latest article with Eric Chow and Alexandre Camargo Turqueto for Foley & Lardner LLP, we look at the financing structures, redemption risks, and sponsor incentives shaping this next chapter of the SPAC market.
Check out our insights on Ignite here – foley.com/insights/publicati…


A whole warrant plus a 1/2 share right is a generous SPAC unit package, and they still reduced the offering by 33%.

SPACCircle Acquisition lowers deal size by 33% ahead of $100 million IPO $SCQCU $IPO #IPO zpr.io/BjkBneUmaes5

"Hyperscale Data Targets 2027 Public Listing for askROI AI Unit. The company is weighing an IPO, reverse takeover or SPAC transaction."
tokenpost.com/news/business/…

Spring Valley Acquisition V charging $75,000/month for office space, utilities, and secretarial and administrative support is the most egregious administrative fee I've ever seen in a SPAC filing.
That's $900,000 annually paid to the sponsor. For context, $10,000/month has historically been common.
sec.gov/Archives/edgar/data/…
Interesting SPAC development.
Tang Capital filed six USPTO trademarks on August 13, 2026, covering NP SPAC, NP-SPAC, NPSPAC, PF SPAC, PF-SPAC and PFSPAC.
54 days later, Tang publicly filed its S-1 for a no-promote SPAC.
Trademarking multiple variations suggests Tang may see promote free SPACs as a repeatable model rather than a one off offering.
Could no promote structures become the next evolution of SPACs?
trademarks.justia.com/owners…
I collected and analyzed 100 SPAC redemption notices from Continental Stock Transfer (CST), covering 94 events with payment timing data and 93 with approximate vs. actual redemption prices. Data is from Jan 2026 through today.
The dataset tracks meeting dates, payment dates, redemption types, processing times, and NAV discrepancies.
Some interesting findings on business-combination closing risk, and how accurate approximate redemption NAV really is.


SPACs from the 2020–2021 boom appear to finally be settling litigation.
cornerstone.com/wp-content/u…

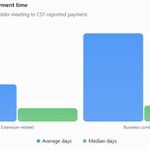
I analyzed 23 SPAC extension redemption payments processed by Continental Stock Transfer & Trust to better understand the timing between shareholder meetings and redemption payouts.
Based on data from June–September 2026, excluding two outliers, the average time from meeting to payment was 7 calendar days, or approximately 5 business days.

Unusual arrangement between $PMTR & $TVA disclosed in $TVA's recently filed S-4.
$PMTR had been negotiating a potential merger with PlusAI and already had a draft term sheet.
On May 21, 2026, $PMTR & $TVA agreed to partner on the proposed PlusAI transaction. $PMTR's existing draft term sheet with PlusAI was then delivered to $TVA, which became the merger vehicle.
A pre-merger SPAC helping another pre-merger SPAC secure a deal. Interesting.
sec.gov/Archives/edgar/data/…
$LPBB 23 million shares before redemption. 4,677,929 after redemption. 4,481,851 of the remaining shares under non redemption agreements.
For every 100 public shares covered by the agreements, investors collectively stand to receive approximately 34.3 additional sponsor shares if all six monthly extensions are used and the transfer conditions are satisfied.
Non-redemption agreements were aggressive for this SPAC. For comparison, GP-Act III 0.05 additional shares. Launch One was 0.20. Andretti II was 0.25–0.333.
Is the amount of sponsor shares being forfeited for non redemption agreements increasing and what does this mean for SPACs?