

financial analysts|Defi analysts|Web3 community manager|founder(MoMs Academy). Partnership with @protocol_blend. Managing community for @Raacfi
Delta
Joined March 2022
- Tweets8.2K
- Following1.4K
- Followers1.1K
- Likes8.3K




Pinned Tweet
My name is Investor CD and am a magnet in the web3 community and crypto space at large..I attract everythin good..
I’m the founder of MöMś Academy, work as a team member with NoahSwap.io
We help in revitalizing dying projects with a minimum of 500 holders
INVESTOR CD retweeted

Epoch 4 of Phase 2 Testnet is on the board ✅
• 8K+ new DAU on Arbitrum Sepolia
The week covered all five pools, USDZ routes traced from swap to settlement on Arbiscan, and how reserves shape what a pool can take.


INVESTOR CD retweeted

Options led global exchange-traded derivatives in 2025, accounting for 74% of futures and options contracts.
Onchain, it's a different story.
Over the past 30 days, perps did $633.8B in volume, while options did just $4.26B.
Two major barriers are fragmented liquidity and complexity. Traders still have to figure out strikes, expiries, and strategies before placing a trade.
At LayerV, we’re working to change that, with the goal of becoming the largest and most liquid onchain options venue.
INVESTOR CD retweeted
Bitcoin options suggest downside caution, with comparable contracts on Deribit pricing protection against a fall more richly than upside exposure.
At the time of the snapshot, with $BTC trading at around $83,050, put expiring on 30 October shows 34.98% implied volatility, versus 32.41% for an $85,000 call with the same expiry. Implied volatility expresses the volatility embedded in an option's price, helping us compare how richly different options are priced.
The comparison needs some care. We keep the expiry identical so both contracts cover the same period, and choose options close to 25 delta: their values have similar sensitivity to Bitcoin's price, in opposite directions. The put benefits from a fall, while the call benefits from a rise, all else equal.
We use different strikes because we want to compare demand for protection below the current market price, with upside exposure above it. At the same strike and expiry, put and call IVs should generally align under consistent pricing assumptions, so that comparison would reveal little about how the market prices the two directions.
This relative pricing difference is volatility skew. Here, the put's IV was 2.57 percentage points higher than the call's. That premium is consistent with demand for downside insurance against a potential drop, without necessarily implying that traders expect Bitcoin to fall.


INVESTOR CD retweeted
USDG approved for Stabilizer
Global Dollar, issued by @Paxos as the core asset of the Global Dollar Network. Risk-assessed and available for testing on Arbitrum Sepolia.
Read the announcement 👇
stabilizer.discourse.group/t…


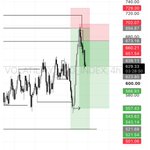
Sometimes aggressive entry is actually better lmao…
What’s all this missed entries because of confirmation 😂


