Northwise Project (@InvestNorthwise) header
Northwise Project (@InvestNorthwise) profile picture

Build Wealth with Direction. Fundamental Investing across AI, FinTech, Ecommerce, & Emerging Markets. $AMD $NBIS $SOFI $HOOD $META $NU $IREN $SNOW $CELH $MELI

United States
Joined April 2025
Photo by Northwise Project (@InvestNorthwise)Photo by Northwise Project (@InvestNorthwise)Photo by Northwise Project (@InvestNorthwise)Photo by Northwise Project (@InvestNorthwise)Photo by Northwise Project (@InvestNorthwise)Photo by Northwise Project (@InvestNorthwise)Photo by Northwise Project (@InvestNorthwise)Photo by Northwise Project (@InvestNorthwise)Photo by Northwise Project (@InvestNorthwise)Photo by Northwise Project (@InvestNorthwise)
Nebius $NBIS is nearly 50% below its all-time high, and the fear spreading through AI infrastructure is hard to ignore: what if demand keeps growing, but the companies building for it run out of money? The pressure on $CRWV and $IREN shows how widely that fear has spread. For businesses buying expensive GPUs and renting out computing capacity, access to financing can decide whether a full order book ever becomes a good outcome for shareholders. We think the market is underestimating how much revenue Nebius can bring online in 2027. Our base case forecasts $21.9B of revenue and $12.5B of EBITDA as new capacity enters service. But getting there requires $58.8B of cash capex. Even with $21.6B of operating cash flow, including customer prepayments, that leaves roughly $37.2B to fund. The timing of those advances, the availability of secured debt and the price of new equity all matter. That is where our conviction has to earn its keep. We follow the capacity through delivery, contracts and cash, then account for the debt and dilution needed to build it. Slower commissioning or worse financing terms change the outcome. We've made the full operating analysis and the bear, base and bull results free to read. The image below puts the capacity, earnings, cash requirements and share count together so you can see what our view depends on. The new Nebius 2027 report is in the first reply.
7
3
3
74
21,814
Our AST SpaceMobile $ASTS Base forecast reaches about $5.15B of revenue in 2030, but the financing challenge arrives earlier. The build requires cash before the full customer base is generating receipts. Our forecast assumes roughly $570M of new gross equity and $556M of additional debt across 2027 and 2028 to maintain a $750M minimum unrestricted cash balance. That minimum is an analyst planning assumption, not an announced company commitment. By 2029, modeled operating cash flow covers capital spending. Getting to that point still requires the intervening launches, commissioning, carrier uptake and funding to arrive on workable terms. We think this is one of the most useful ways to examine the opportunity: a business can have an attractive destination while the route changes the number of shares and debt claims attached to it. The free operating model lets readers change the deployment and commercial assumptions and follow the consequences through funding and cash flow. northwiseproject.com/researc…
1
2
484
Northwise Project retweeted
Be patient today with $NBIS and others. Don’t over-leverage. The fundamentals will eventually take charge of the sentiment and picture. Earnings continue to explode around the market, and demand remains n a consistent upwards trend. That does not mean the market has to rally back next week. I see this as a possible bottom, but it could be a 2018 like scenario. Yesterday definitely felt near capitulation, but that’s often where a last unexpected down move finishes.
2
31
2,617
Northwise Project retweeted
The red is a bit blinding, but this is a phenomenal opportunity to pick up the highest names across tech. Some names we like most here: AI Infra: $NBIS $AMD $NVDA Fintech: $SOFI $NU $HOOD Hyperscalers: $AMZN $GOOG $META Emerging: $MELI $JMIA $GRAB Discretionary: $CELH $HNST $HIMS Bonus: $RKLB $NFLX $MU $SNDK With the market officially in correction territory, I believe it’s prudent to keep a long term horizon and to slowly move risk on in lots. NFA, but we are buyers across Northwise and personal allocations with some valuations hitting GFC levels.
3
1
21
1,762
Competition with NVIDIA $NVDA looks different depending on who is buying the hardware. A large cloud with a predictable internal workload can justify building a chip around that job. An independent provider such as Nebius $NBIS or IREN $IREN has to sell capacity to customers whose software and needs may vary. AMD $AMD gives those buyers another merchant supplier without requiring them to design a chip themselves. We think NVIDIA's platform breadth is especially valuable where that customer mix is less predictable. Custom chips can win substantial workloads while NVIDIA continues to grow elsewhere. Our question is where each alternative wins enough useful work per dollar to change a purchasing decision. One industry-wide market-share number hides much of that competition.
1
1
1,061
Great report from $CELH in what is becoming a larger position in our main holdings. We continue to see great value here as people underestimate Alani breaking into new segments and demographics in the U.S. and a further severe underestimation of future international growth opportunity across the brands. Very pleased as well to see the decision to assign dedicated presidents and teams to each distinct brands. Looks like management is really considering lessons learned with SKU optimization, which caused the real short term stumble with the Core Celsius brand.
772
Northwise Project retweeted
We’re going to be deep diving heavily back into the AI infra buildout here soon. Core model updates coming to $NBIS $CRWV $IREN to start. Looking to build year by year through 2030 with an emphasis of separating fact from FUD regarding where these names stand today. We remain very constructive on the sector as a whole with special credit to those with a healthy balance sheet, plenty of financing flexibility for the buildout ahead, and those creating full AI native integrated stacks. Overall, we believe the current market dynamics are extremely sentiment driven and could flip “overnight” at any time. We aren’t predictors of short term technicals, but we believe the flip will come now or over the next several months. In the meantime, we see a multitude of opportunities across the sector and continue to average into the most high quality names. We view this is a generational buying opportunity for the next leaders in Cloud. The fundamental picture has not worsened and if anything valuations are more attractive across tech as a whole than they have been over many years. We are buyers and will continue to be at these prices, unless the thesis is fundamentally proven broken.
2
4
40
2,479
Northwise Project retweeted
Congrats to those who picked up $NBIS under $150. Our smaller active internal fund is now 100% nebius for the time being. We might not be completely out of the woods yet, but I do see a lot of narratives dissipating/reframing after today. Don’t underestimate how much politics influences the markets at times. Really good opportunity to return to the fundamentals with earnings coming up. Highly recommend checking out our 2027 model to familiarise yourself at some differentiated perspectives. We expect a very large beat of street estimates for 2027, but management will likely raise guidance for exit ARR and capex a few times before it’s all said and done to keep some stability.
9
1
2
105
8,954
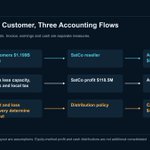
The European partnership can expand AST SpaceMobile $ASTS distribution, but customer spending, AST revenue and cash received by AST are different amounts. In our Base 2030 forecast, European customers pay the SatCo reseller about $1.20B. SatCo pays AST roughly $935M for capacity. AST also receives a 50% share of the venture's profit, modeled at about $59M, while the assumed cash distribution is approximately $47M. We record the capacity payment as AST revenue. The profit share is a separate earnings contribution, and the cash distribution follows the venture's payout assumptions. Adding all four figures together as AST revenue would substantially overstate the business. The commercial attraction is access to local carrier relationships and shared economics. Assessing that attraction requires following what AST supplies, what the partner retains and what eventually reaches AST in cash. These figures are forecast assumptions, not promised payments.
1
6
1,051
A dollar can appear in several AI partnership announcements before it pays for a single piece of equipment. Equity, loans and customer prepayments can finance a build for an operator such as Nebius $NBIS or IREN $IREN. Its orders from NVIDIA $NVDA are one use of those funds. Adding the funding and equipment headlines together counts the same money twice. We follow those dollars through the project. A partnership can make a build more likely without its headline value becoming additional NVIDIA revenue.
2
7
6
1,242
Northwise Project retweeted
Our $NBIS 2027 model and forecast might be our least viewed model for Nebius yet, but I think it's the most well done by the team and the most significant and relevant timing wise. We are planning a massive build after Nebius earnings, where we are going to leverage this new data and model to fill in the gaps and model out 2028, 2029, and then a new 2030 model using this year by year approach in hand with our ground-up data center capacity data. It's never been more important to understand the fundamentals of this sector and Nebius' specific circumstances. If you follow our work and haven't yet pulled the trigger on a membership, we are running our first year anniversary sale until early Monday morning. I highly recommend seeing if its a fit for your individual research workflow. Members get our full price targets for 30+ names, both flagship and active growth portfolios, data center tracker, imbedded capacity built financial forecasting tools for $NBIS $IREN $CRWV $CIFR $KEEL and $WULF and support our goal of bringing a full time research team to Northwise. Regardless, cheers to an incredible full first year of Northwise memberships and a special thanks to those who continue to support our journey to fill the gap between institutional and retail research. northwiseproject.com/checkou…
Nebius $NBIS is nearly 50% below its all-time high, and the fear spreading through AI infrastructure is hard to ignore: what if demand keeps growing, but the companies building for it run out of money? The pressure on $CRWV and $IREN shows how widely that fear has spread. For businesses buying expensive GPUs and renting out computing capacity, access to financing can decide whether a full order book ever becomes a good outcome for shareholders. We think the market is underestimating how much revenue Nebius can bring online in 2027. Our base case forecasts $21.9B of revenue and $12.5B of EBITDA as new capacity enters service. But getting there requires $58.8B of cash capex. Even with $21.6B of operating cash flow, including customer prepayments, that leaves roughly $37.2B to fund. The timing of those advances, the availability of secured debt and the price of new equity all matter. That is where our conviction has to earn its keep. We follow the capacity through delivery, contracts and cash, then account for the debt and dilution needed to build it. Slower commissioning or worse financing terms change the outcome. We've made the full operating analysis and the bear, base and bull results free to read. The image below puts the capacity, earnings, cash requirements and share count together so you can see what our view depends on. The new Nebius 2027 report is in the first reply.
2
7
59
7,774
A faster processor aboard an AST SpaceMobile $ASTS satellite can be valuable, but the data still has to reach the carrier's network. The complete path runs from the phone through the satellite's access radio and processor, then through the feeder link, ground gateway and carrier connection. Each stage has its own limits. In the attached hypothetical example, the access link can carry eight units, the processor six and the feeder link four. Delivered traffic is limited to four. Doubling processor capacity alone leaves that output unchanged. We use this distinction when assessing hardware upgrades. More capability in one component can remove an important constraint, provide headroom or improve flexibility. The revenue benefit depends on whether the rest of the path can carry additional billable traffic. Our focus is the capacity of the working network under relevant conditions. A component specification is useful evidence; the commercial result depends on how the components work together.
7
3
1,024
Northwise Project retweeted
Remember $NBIS is trading for less than one time our projected 2027 ARR. If we are too high by 50%, nebius is still trading less than two times next year’s exit. Not many opportunities to intersect that deep of value, elite management, and an insatiable demand environment.
2
8
2
113
17,867
Celsius $CELH's planned Energy+ Hydration line gives the company a way to reach people who want a noncarbonated drink. Some of those buyers will also be existing Celsius customers choosing a different can. We allow for both in our 2027 forecast. Of the $75 million in sales we estimate for the new line, we assume 35% replaces purchases of existing Celsius products. That leaves roughly $49 million of additional company revenue. Manufacturing and freight still have to be paid on every new can sold. After those costs and the costs avoided on displaced products, the forecast adds about $19 million of gross profit, before marketing and overhead. We like innovation that broadens when and why people buy Celsius. The test is how much it adds to the whole franchise after customer switching and launch costs. A busy new-product shelf can make that harder to see. Full analysis: northwiseproject.com/researc…
6
3
1,066
We forecast Meta $META generating $308.61B of operating cash in 2030. The amount available for share repurchases is much smaller. In our October 9 Base model, capital spending leaves $98.67B of free cash flow. Cash paid for employee stock taxes and dividends brings that down to $63.50B. Investment commitments, debt repayment and liquidity decisions still follow. Repurchases end up at $35.85B. This is why we follow the whole cash schedule when estimating earnings per share. A large operating cash number does not automatically mean a rapidly shrinking share count. The model gives Meta credit for a substantial recovery in cash generation by 2030. It also makes the competing uses of that cash explicit. The report and model: northwiseproject.com/researc…
5
4
837
Our forecasts have CoreWeave $CRWV and Nebius $NBIS buying more NVIDIA $NVDA equipment while accounting for a smaller share of its broader market. Across those two providers plus IREN $IREN, we estimate $415.4B of potential NVIDIA equipment purchases over 2026 through 2030. These are our forecasts, not disclosed orders. The narrower annual comparison in the chart includes CoreWeave and Nebius only. Their combined share of our forecast for NVIDIA's AI compute infrastructure equipment revenue falls from 20.6% in 2026 to 10.0% in 2030, even as their purchases grow. We think that is the more interesting expansion story: large customers getting larger inside a market growing faster still. It requires new buyers to arrive alongside them, with the funding and demand to support their own buildouts.
3
5
10
1,601
Northwise Project retweeted
Nebius $NBIS could earn more per megawatt while customers pay less per unit of AI work. Better hardware can make that happen. If the amount of useful work a system delivers grows faster than the price of renting it, the customer gets better economics even as the provider earns more. The Rubin illustration in our 2027 Nebius Model shows the relationship. Using a selected NVIDIA benchmark and reference rack-power figures, we get about 59% more useful work per megawatt than GB300. Our assumed gross rental revenue per megawatt rises by about 22%. Under those assumptions, the customer's price per unit of work falls roughly 23%, while Nebius earns more from the same power budget. The figures are a workload-specific illustration. Actual customer workloads and negotiated prices will determine how much of the gain Nebius captures. For Nebius, Rubin could raise the revenue potential of each secured megawatt while making it more economical for customers to expand their AI usage. Its software platform can help turn that hardware capability into billable revenue by keeping the systems busy and delivering reliable performance.
3
4
53
2,763
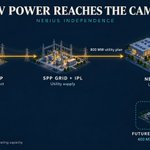
$NBIS's Independence campus could become a foundation for years of US growth, giving Nebius more control over where and how it adds compute. The site is planned for up to 1.2 GW across four buildings. Owning that footprint lets Nebius plan power, cooling and later expansions together. The buildings and electrical infrastructure can support several generations of GPUs, giving it a place to expand customer capacity over many years. For shareholders, the opportunity is a larger business built on infrastructure Nebius controls. Ownership also puts more of the construction and financing burden on Nebius. The return depends on getting power, computing equipment and customers into place together. Delays leave capital tied up longer before it earns revenue. That makes the power arrangements central to the story. The utility supply, off-site Blue Valley generation and future on-site generation are separate parts of the plan. A power-station permit is progress, but it does not establish operating compute. The 1.2 GW is ultimate planned capacity. Our review did not verify current active IT MW. Nebius's May 2026 guidance pointed to Missouri operations in 2027, while its four-building plan spans five to seven years. Confirmed power delivery, commissioned capacity and customer activation will show when that long-term opportunity starts contributing to the business. Our refreshed Independence report explains the full site, its power arrangements and the path ahead, with new diagrams and direct tracker and model connections.
🤖 Made with AI
2
2
1
45
3,719
Northwise Project retweeted
I think the Street is underestimating the size of the business Nebius $NBIS could be operating by the end of 2027. Our forecast is $21.9B of 2027 revenue, roughly 79% above the $12.2B consensus used in our report. We also see $42.6B of owned-cloud exit ARR, rising to a $44.2B platform run rate when net partner revenue is included. Here is what gives me conviction in numbers that far apart. In its Q2 shareholder letter, Nebius said: "We could sell our entire 2027 capacity on these terms today." It was deliberately retaining capacity for customers willing to pay more for immediate access. The same letter reported landmark deals at $20M-$25M of annual revenue per MW and a $40M-$50M opportunity for short-duration capacity, with the first such deal already signed. At GTC Berlin, Arkady Volozh said demand was not the constraint and that he wanted at least half of capacity serving those shorter-duration needs. That commercial mix matters enormously. The revenue potential of a megawatt changes with the hardware inside it and the contract attached to it. Then there is the physical expansion. Management plans to deploy more than 1 GW a year starting in 2027. The Berlin discussion specifically addressed 1 GW of Vera Rubin, with Volozh describing a ramp weighted toward Q3 and Q4. Pennsylvania provides a concrete site milestone: an initial 260 MW phase targeted for October 2027. We translate that evidence into 1 GW of new Rubin installations, another 250 MW of Blackwell, and an existing fleet that continues earning. Those are our assumptions. We allow time for commissioning, price each hardware generation separately, honor signed contracts and allocate roughly half of incremental accepted capacity to shorter-duration customers. That leaves about 1.61 GW accepted at year end, but only 938 MW billing on average during 2027. This timing is why the exit ARR looks so large relative to annual revenue. A cluster arriving late in the year contributes little to that year's sales while contributing fully to December's annualized pace. My reading is that consensus implies a smaller productive fleet, lower realized pricing, later delivery, or some combination of the three. I think the capacity plans and signed deal economics support a much larger outcome.
Nebius $NBIS is nearly 50% below its all-time high, and the fear spreading through AI infrastructure is hard to ignore: what if demand keeps growing, but the companies building for it run out of money? The pressure on $CRWV and $IREN shows how widely that fear has spread. For businesses buying expensive GPUs and renting out computing capacity, access to financing can decide whether a full order book ever becomes a good outcome for shareholders. We think the market is underestimating how much revenue Nebius can bring online in 2027. Our base case forecasts $21.9B of revenue and $12.5B of EBITDA as new capacity enters service. But getting there requires $58.8B of cash capex. Even with $21.6B of operating cash flow, including customer prepayments, that leaves roughly $37.2B to fund. The timing of those advances, the availability of secured debt and the price of new equity all matter. That is where our conviction has to earn its keep. We follow the capacity through delivery, contracts and cash, then account for the debt and dilution needed to build it. Slower commissioning or worse financing terms change the outcome. We've made the full operating analysis and the bear, base and bull results free to read. The image below puts the capacity, earnings, cash requirements and share count together so you can see what our view depends on. The new Nebius 2027 report is in the first reply.
2
5
40
3,317
Our free Nebius $NBIS 2027 operating analysis and bear, base and bull forecasts are here: northwiseproject.com/researc… We're also marking Northwise Premium's first anniversary with a one-week offer for new members. If you'd like to work through your own assumptions, Premium includes the editable workbook, valuation scenarios and entry framework. Start with the free research and see whether our approach is useful to you.
3
15
1,524