

Associate Prof of Finance at UIUC @giesbusiness
Joined February 2010
- Tweets100
- Following323
- Followers857
- Likes698


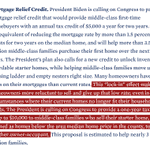
This has been in the back of our minds since we started working on credit scoring years ago. Credit scores are used by lenders and others, so can a lower score worsen financial health and cause the default it predicts? If so, do scorers have incentives to limit these defaults?

Credit scores cause at least part of the default they predict for risky borrowers. A score assessed on separating defaulters from non-defaulters is rewarded for defaults it causes, from Victor Duarte and @JuliaAFonseca nber.org/papers/w35508

The reason is simple: the causal effect is concentrated on borrowers that the score ranks as risky (i.e. "separates" from non-defaulters). So separation metrics reward the score for defaults it causes, giving scorers no incentive to limit the self-fulfilling defaults we document.
1
1
114

Julia Fonseca retweeted
Credit scores cause at least part of the default they predict for risky borrowers. A score assessed on separating defaulters from non-defaulters is rewarded for defaults it causes, from Victor Duarte and @JuliaAFonseca nber.org/papers/w35508
Excited to see this out! We come up with (AFAIK) a brand new way to solve for market-clearing prices: target an imbalance of zero like a moment condition. We expand the state space to include parameters and prices, so we can estimate and clear markets after solving the model once

Also, neural networks learn the mapping between parameters and moments, making this very efficient (as in from days to minutes). To lower entry costs, we built an agent that writes code to implement our approach based on a natural language description of the model. Coming soon!
2
5
936
Joint with the one and only Victor Duarte. Link to the paper: nber.org/papers/w35283
5
728
Julia Fonseca retweeted
A global estimation method learns the parameter-to-moment mapping, and treats prices as parameters and market clearing as moment conditions, reducing run time from days to minutes, from Victor Duarte and @JuliaAFonseca nber.org/papers/w35283

Julia Fonseca retweeted
Mortgage lock-in keeps would-be downsizers in larger homes. These missing downsizers raise net demand, offsetting a third of the house price decline caused by higher interest rates, from @JuliaAFonseca, @luliu_fin, and Pierre Mabille nber.org/papers/w35237

🚨New pre-doc position! Come work with @luliu_fin and me on mortgage, housing, and labor markets. We'll be tackling policy-relevant questions with both empirical and structural methods. @econ_ra #EconTwitter
The position will be up to 2 years, shared between UIUC and Wharton (with the option to do the first year remotely or spend the full two years at Wharton). Please apply asap using the link below. The priority deadline is Dec 1, and we will review on a rolling basis.
1
573
Julia Fonseca retweeted
The April 2023 decision to stop reporting medical debts below $500 on consumer credit reports had no effect on credit access or financial health, from Victor Duarte, @JuliaAFonseca, Divij Kohli, and Julian Reif nber.org/papers/w33644

Julia Fonseca retweeted

Call for papers for the very 1st UMass Amherst Finance Conference
isomfinancedept.wixsite.com/…
The conference is on Friday, May 9, 2025
The deadline for submitting your paper is February 1
@econ_conf #econtwitter @UMassAmherst @IsenbergUMass
