





ALT Bar chart of outcomes for U.S. power capacity that requested interconnection from 2000 to 2020: 13 percent had been built by the end of 2025, and 75 percent had been withdrawn. Source: Berkeley Lab, Queued Up 2026 Edition.

ALT Bar chart of ServiceNow goodwill in millions of dollars: 3,578 at Dec 31, 2025 and 10,012 at Sep 30, 2026 highlighted.

ALT Bar chart of PayPal loans derecognized, unpaid balance in billions of dollars: 18.3 in the first nine months of 2025 and 24.0 in the first nine months of 2026 highlighted.

ALT Bar chart of Rivian property and equipment in millions of dollars. Construction in progress fell from 1,712 at Dec 31, 2025 to 463 at Sep 30, 2026, while machinery and equipment rose from 4,152 to 5,868 over the same period.


ALT Bar chart of Boeing 777X work in process in millions of dollars: 4,313 at Dec 31, 2025 and 7,608 at Sep 30, 2026 highlighted.

ALT Bar chart of Microsoft leases not yet commenced in billions of dollars: 329.1 at June 30, 2026 and 364.6 at September 30, 2026 highlighted.

ALT Bar chart of Robinhood Q3 transaction revenue in millions of dollars: event contracts 27 in Q3 2025 and 173 in Q3 2026 highlighted, crypto 268 in Q3 2025 and 120 in Q3 2026.

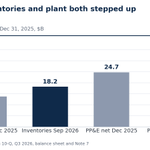
ALT Bar chart of Eli Lilly inventories and net property and equipment in billions of dollars: inventories 13.7 at Dec 31, 2025 and 18.2 at Sep 30, 2026, property and equipment net 24.7 and 32.2.

ALT Bar chart of Amazon's total commitments in billions of dollars: 650.0 at June 30, 2026 and 883.6 at September 30, 2026, the September bar highlighted. Source: Amazon Forms 10-Q for Q2 and Q3 2026, Note 4.

ALT Bar chart in billions of dollars: Meta mandatory convertible preferred closed October 29, 12.5; forward sale at the initial price, not yet received, 24.9 highlighted.

ALT Bar chart of Alphabet inventory in millions of dollars: 2,439 at Dec 31, 2025, 9,991 at Jun 30, 2026, and 13,308 at Sep 30, 2026 highlighted.


ALT Bar chart of Mastercard's preliminary BVNK purchase price allocation in millions of dollars: goodwill 1,271 highlighted, developed technology 238, customer relationships 125.

ALT Bar chart of Ford Credit total finance receivables in millions of dollars: 110,579 at December 31, 2025 and 105,865 at September 30, 2026 highlighted.

ALT Bar chart of Caterpillar long-term trade and other receivables rising from $2,142 million at Dec 31, 2025 to $2,490 million at Mar 31, 2026, $3,086 million at Jun 30, 2026, and $3,348 million at Sep 30, 2026, with the September bar highlighted.

ALT Bar chart of Chevron upstream capex in millions of dollars for the nine months ended September 30: U.S. upstream 7,209 in 2025 and 6,046 in 2026, international upstream 3,967 in 2025 and 5,632 in 2026 highlighted.


ALT Bar chart of ExxonMobil notes and accounts receivable, net, in billions of dollars: 44.6 on December 31, 2025 and 66.5 on September 30, 2026 highlighted.