



Pinned Tweet
$TSLA the AUTO OEM! - Dissecting the three major bull case inconsistencies and why 2027 EBIT of $40bn could have ~60% downside. Tweet B1) to B6) & D3), D4) has data you probably have not seen before. Not financial or investment advice. A 23 Tweet🧵

$ANT - Inference gross margin is not collapsing despite a decline in cost per token and here is why.


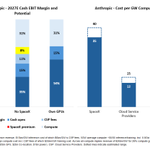
$ANT - Literally the only chart you need to understand to estimate Anthropic cash generation potential!

Clearly OpenAi should just wait. Their subsequent fundraising depends on a successful $ANT IPO. See the bigger picture @sama !!

So far, there is no sign of anything from OpenAI, no new "GPT-6.2 Astra." While there is still reason to hope, I am becoming increasingly puzzled. It feels as though both Anthropic and OpenAI are waiting on each other; neither wants to make the first move, yet each aims to outdo the other.
Ultimately, the stakes couldn't be much higher, especially when you consider the prospect of an IPO for Anthropic. Their success would need to surpass what OpenAI achieved prior to its own potential public offering.
1
562
$ANT Most don't appreciate how much of a moat scale is. Pre-training cost scale with ^2 of parameters. 4x P = 16x cost. China OW will soon be unable to fund training runs or they need to start charging more which is hard as they no longer have an intelligence / cost advantage.

$ANT - Post IPO will have nearly $0.25trn of net cash likely the highers of any company on earth earning interest of ~ $10bn p.a. or about 1/3 of its compute cost in 2026 and the market worry they can't pay their bills!
1
431
This is the correct take. Had $ANT issued equity back in 2023 and 2024 the equity dilution would have been even higher. The fundamental benefit of a convert is you get to issue the equity at a higher price.

Anthropic just reported an $80.7B loss for the first half of 2026.
Revenue was $16.3B. The operating loss was only $693M.
So where did the other $80B come from?
A few pieces of paper Amazon bought in 2023 and 2024.
Rewind to September 2023.
Anthropic was valued around $4B, a distant second to OpenAI.
Andy Jassy's Amazon wanted a frontier model of its own on AWS.
On Sept 19, 2023, Amazon signed a convertible note deal with Dario Amodei's company:
- $1.25B up front, another $2.75B in March 2024
- 8% interest, 10 year maturity
- Convertible at $20.93 a share
In November 2024, Amazon came back with $4B more:
- Paid in three pieces through November 2025
- 8.5% on the first piece, zero on the rest
- Convertible at $50.48 a share, a 10% discount to the next round
Then the valuation went vertical:
- $61.5B in March 2025
- $183B in September 2025
- $380B in February 2026
- $965B in May 2026, at $589 a share
Now do the math.
A note that converts at $20.93 into a $589 share is worth 28x its face value.
The 2024 notes are worth almost 12x.
Accounting rules make Anthropic carry these notes at fair value.
Every quarter it asks what Amazon would get if it converted today.
Any increase goes through the income statement as a loss.
$6.2B of principal is still outstanding:
- Carried at $41.7B on Dec 31, 2025
- Carried at $108.6B on June 30, 2026
- That $72.4B jump is most of the loss
Another $8.8B came from booking new funding deals signed with Google and Amazon this spring.
Same story in 2025: $34.3B of a $42B loss.
So why are the notes still there?
Amazon has an ownership cap.
Each new round triggered conversion, but anything above the cap rolled into a fresh zero interest note.
Then the next round marked those up too.
Strip the marks out and you see the real business:
- Q2 2026 operating profit of $974M, its first ever
- Positive $3.9B cash from operations for the half
But somebody does pay for this.
At the IPO, the notes convert into shares for Amazon.
Every other shareholder gets diluted.
Amazon has put about $13B into Anthropic.
Its own books now value the stake at roughly $190B.
Possibly the best trade of the AI era.
nitter.cf/hedgiemarkets/status/2…
$ANT to those confused about non-cash losses from convert revaluations please look at the FCF statement and the Balance Sheet and you will see its all ties in. The company will end the year with $240bn of NET CASH post IPO this highest of any public company.

Its getting tiresome. Compute in 2026 is around $32bn (60% of $56bn revs). End 2025/26 was 1GW/5GW so AVERAGE compute in 2026 is ~3GW or $11bn per GW or $3.2 per GPU hour well with-in market rates. Sure recent deals are higher but as revenue per GW is $50bn lots of headroom...

Anthropic spent $7.2 billion for 1.4 GW of compute in 2025 (based on reports from investor presentation).
Anthropic told investors in presentation they were tracking 5 GW in 2026. They are tracking $20 billion spent.
Anthropic spent $5.14 billion / GW in 2025
Anthropic is tracking $4.0 billion / GW in 2026 spent (4x lower than industry standard of $16-$22 billion / GW)
Anthropic just signed a contract with N-Scale at $16 billion / GW in 2026, 4x higher than its reporting in its S-1.
The magic of $AMZN deal. 75% off compute.
Their true compute cost would have been closer to $80 billion in 2026 vs $20 billion.

Not more so than $SPCX where 85% of locked up shares now trade freely and the stock has outperformed the market since IPO…


6
641
Don't like the neoclouds at all (of which $SPCX is one too) but someone needs to appreciate when Elon is just talking his own book.


$4trn over say 8 years is $0.5trn p.a. The companies in the chart have EBITDA of $1.2trn in 2026 (in the bag) and if you believe the 2027 numbers $1.7trn. It is not obvious why @zerohedge worry about this every single day.

Total Hyperscaler off balance sheet debt as of Oct 21: $3.6 trillion (with META and SPCX reporting). Expect this to cross $4 trillion when the rest report.

379
$TSLA updated an old friend. $1.5trn market cap. $2bn cumulative core FCF since inception (red bars). Best described as a $100bn run-rate revenue science project that never has and never will make money.

$TSLA CFO just mentioned entire sequential margin improvement due to one-offs, so more like $450mn net income impact or $0.13 per share of EPS so excl this $0.35 clean EPS vs. $0.43 consensus.

$TSLA Energy saw a 24% ASP decline ($/kWh) to now $197 taking revenue down 16% in Q3 and down 5% YTD. Yet 3Q gross margin was 33% up from 20% in 2Q. I suspect a one-off tariff benefit like in 1Q. If 23% underlying margin then $300mn boost or $0.07/share = entire beat and more...

$TSLA Energy saw a 24% ASP decline ($/kWh) to now $197 taking revenue down 16% in Q3 and down 5% YTD. Yet 3Q gross margin was 33% up from 20% in 2Q. I suspect a one-off tariff benefit like in 1Q. If 23% underlying margin then $300mn boost or $0.07/share = entire beat and more...

Imagine building compute based on mostly 90 day rolling contracts. $SPCX
