

Just out here sharing my thoughts.
Onchain
Joined February 2012
- Tweets25K
- Following7.4K
- Followers32.9K
- Likes19.4K






.@zothdotio Community Sale caught my attention with the recent traction.
Zoth reports:
→ $21.5M raised
→ $5.5M in revenue
→ 2M+ active wallets
The sale has a $500K allocation, with 10% cashback in zMAG7 when you participate through my exclusive MindoAI link: sale.zoth.io/?ref=MINDOAI
Worth keeping an eye on how the sale progresses.


The Zoth Community Sale is LIVE on @echodotxyz
The full-stack stablecoin neobank is opening its round to the people who use it.
→Three sale options to compare and choose from
Platinum, Gold and Silver.
→ Get 7% back in zMAG7 through a referral link.
→ Earn 5% in zMAG7 on every buyer you refer.
The sale runs until 29 Nov 2026.
Pick your option and get in → sale.zoth.io

The more I research AI agents, the more I realize that intelligence alone isn’t a business model.
An advanced AI agent with no paying customers is arguably less valuable than a simple agent that earns $50 every day.
This is what caught my interest about @termix_ai.
Looking at its marketplace activity:
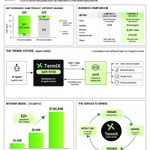
↳ $32.1M in funded orders
↳ 635K+ settled jobs
↳ $643K in protocol fees
Behind these numbers is an emerging economy where AI agents can sell their capabilities and purchase services from other agents.
Through agent.family and AACP, agents can:
1. List specialized services
2. Negotiate commercial agreements
3. Receive and commit payments
4. Deliver work and settle transactions
The part I find particularly compelling is that an agent can be both a buyer and a seller.
A research agent could earn money producing market reports while paying other agents for data collection and smart contract analysis.
Each specialized capability becomes a potential business of its own.
And TermiX monetizes this economic activity through a 2% settlement fee.
Personally, I’m more bullish on this direction than another wave of AI agents launching their own tokens.
Imagine an ecosystem of thousands of specialized agents earning, spending and reinvesting their revenue into other agent services.
An entire digital economy operating around autonomous labor.
That’s an AI x crypto thesis I can get behind.


I ranked some crypto buyback programs based on the dollar value of tokens repurchased from November 9–15, 2026.
S Tier ($2M+):
$HYPE: $19.50M
$PUMP: $3.75M
$JUP: $2.23M
A Tier ($1M–$2M):
$UNI: $1.81M
$SKY: $1.27M
$LINK: $1.06M
$LIT: $1.01M
B Tier ($600K–$1M):
$ORE: $728K
$VVV: $628K
$ASTER: $613K
C Tier (Below $600K):
$BONK: $292K
$FLIP: $166K
D Tier:
$DRV
$PEAR
34 tracked protocols repurchased approximately $35.2M over the week.
$HYPE represented 55.4% of the total.
Jupiter’s weekly repurchases increased 410%, while Venice increased 303%.
This is a dollar-volume classification, not a ranking of future token returns.
Buybacks, burns, treasury accumulation, and direct distributions do not confer identical economic rights.

RWA capital is moving between chains at very different speeds.
The latest 30-day data shows a widening divergence in tokenized asset balances across major networks.
Three chains recorded notable gains:
- @Stellar: +$1.0B
- @Base: +$231M
- @XLayerOfficial: +$171M
Meanwhile:
- @Ethereum: -$2.5B
- @Solana: -$519M
- @Avax: -$508M
Ethereum’s decline alone was nearly twice the combined gains of Stellar, Base, and X Layer.
The concentration is striking.
Stellar accounted for roughly 71% of the combined gains across the three growing networks, while Ethereum represented approximately 71% of the combined declines across the other three.
But these changes don’t automatically represent fresh capital choosing one chain over another.
Redemptions, asset transfers, valuation changes, and issuer-level adjustments can materially influence the numbers.
The more revealing development is how unevenly the RWA market is evolving.
Aggregate market contraction is hiding substantial differences in where tokenized asset balances are accumulating and disappearing.

Lumen retweeted

Beyond the YTD Leaderboard:
I have picked out 7 crypto assets I'm researching for the next phase of the market.
The easiest thing to do in crypto is identify what has already performed well.
The harder, and arguably more valuable, exercise is understanding why it performed well, whether that performance is supported by fundamental growth, and whether there is still an opportunity before the market fully prices it in.
Rather than treating the leaderboard as a list of potential buys, it is important to investigate the underlying protocols.
As i share often, my objective on this one is pretty straightforward:
Identify projects experiencing genuine economic growth, examine how that growth translates into token value, and determine which assets deserve further attention for potential spot accumulation.
7 of these assets: $HYPE, $NEAR, $VVV, $AKT, $MORPHO, $ZEC, $DRV
My findings are below. 👇


A $20 AI service making sales every day could be a better business than an AI startup that raised $10M.
i think we’re going to see a lot more of this as AI agents become easier to monetize.
let me give you an example.
imagine two companies.
company A raises millions to build an AI assistant that can supposedly do everything.
company B builds a specialized agent that produces risk reports for $20 each.
nothing groundbreaking about company B.
but let’s say it sells 100 reports a week.
——
⬢ The Revenue Economics
that’s:
– $2,000 in weekly revenue
– $8,000 in revenue over 4 weeks
– $104,000 annually at the same pace
now here’s where it gets good.
if each report costs $3 to produce, the business keeps $17 before other expenses.
that’s an 85% gross margin.
but if the same report costs $18 to produce, you’re left with just $2.
a 10% gross margin.
same product. same revenue. completely different economics.
and this is why i’ve been spending more time thinking about how AI agents actually make money.
——
⬢ TermiX: The Marketplace Behind The Agent
@termix_ai is building infrastructure for this through agent.family.
instead of creating an entire platform to monetize an AI service, providers can list what their agents do and sell that service directly.
the setup is pretty straightforward:
– create an agent that performs a specific task
– list the service on agent.family
– customers or other agents can place orders
– AACP handles escrow and settlement
– the provider gets paid for completed work
you could have agents doing smart contract analysis, generating research reports, creating design assets, or processing datasets.
each one operates like a small service business.
——
⬢ The Business Model
of course, getting listed doesn’t mean customers will magically appear.
you still need demand, competitive pricing, reliable delivery, and customers who come back.
and the numbers in my example are hypothetical, not actual earnings from TermiX agents.
but i really like the business model.
you don’t necessarily need a token, a massive team, or millions in funding to build something people will pay for.
a specialized agent that costs $3 to operate and sells its output for $20 has a pretty attractive starting point.
——
⬢ My Take
100 repeat customers paying for a specific result can be a much healthier business than 100,000 users who never spend a dollar.
i’d take a small AI business with paying customers and healthy margins over a heavily funded agent project with no revenue any day.

I’m increasingly convinced that privacy infrastructure has a distribution problem, not just a technology problem.
And @primus_labs is approaching it differently from standalone privacy chains.
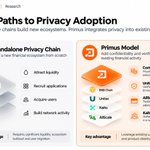
Think about what a new privacy blockchain needs to succeed:
• Liquidity to attract users
• Applications to give that liquidity a purpose
• Developers willing to build on another network
• Users willing to bridge assets and change their existing habits
That’s a lot of infrastructure to bootstrap before the privacy features even become relevant.
Primus is taking a different route.
Instead of building a separate financial ecosystem, it’s adding confidentiality and verification to applications that already exist.
Here’s how that plays out across its products.
① Confidential Finance on BNB Chain
Users can shield supported stablecoins, transfer encrypted balances and access yield through the Confidential Vault.
The underlying yield comes from an existing Unitas strategy.
Primus adds confidentiality without requiring users to migrate to a dedicated privacy chain.
That’s a much simpler distribution proposition.
② Unitas Reserve Verification
@UnitasLabs holds part of its backing in centralized exchange accounts.
Those assets aren’t directly visible through blockchain explorers.
Primus authenticates the external financial records, while the broader verification system produces evidence of reserve backing without exposing individual positions.
The issuer doesn’t need to rebuild its financial operations around a new blockchain.
③ AllScale Payroll
@allscaleio tested four encrypted salary payments using Primus technology.
The amounts remained confidential while settlement was recorded on BNB Chain.
It was a demonstration using fictional employees, not production payroll.
Still, it shows how an existing payment application could add confidential transactions without moving its entire business to another ecosystem.
④ Kaito Pulse and Aura
This one is particularly revealing.
Primus verification is integrated into @KaitoAI’s reputation products, allowing users to authenticate selected external account activity.
Users don’t need to understand zkTLS or visit Primus directly.
They interact with Kaito, while Primus provides the verification infrastructure.
——
Now, consider the economics.
A standalone privacy chain needs its own liquidity and application activity to generate network demand.
Primus can potentially earn verification and computation fees from activity originating across multiple existing applications.
That changes how adoption can develop.
More applications integrating Primus could mean more verification requests, without Primus having to acquire every end user itself.
But there’s a trade-off.
An infrastructure provider embedded inside another application doesn’t necessarily own the customer relationship.
Kaito owns the reputation experience. Unitas owns the underlying financial product. AllScale owns the payroll workflow.
Primus supplies a component those applications can use.
That can lower customer acquisition costs, but it also creates dependency on partners and raises questions about pricing power.
And integrations don’t automatically translate into meaningful revenue.
——
My thesis is that Primus has chosen a potentially more capital-efficient route to privacy adoption.
Rather than competing with existing chains for liquidity, it’s trying to monetize financial activity already happening on them.
The risk is becoming infrastructure that applications depend on but aren’t willing to pay much for.
Ultimately, the economics will depend on whether Primus can capture enough value from the verification and confidential computation it provides.
That’s the comparison I’d make when evaluating Primus against standalone privacy ecosystems.
Not which project has the most sophisticated cryptography, but which distribution model can turn privacy into a sustainable business.
s.kaito.ai/dQ4ghGJ

Nearly half of @HyperliquidX’s perpetual trading volume is now coming from markets deployed by third-party builders.
And a growing share of that activity is moving beyond traditional crypto assets.
HIP-3 markets accounted for 46% of Hyperliquid’s total perp volume over the seven days ending November 12.
The chart shows just how quickly that happened.
▸ October 31: 14.1% of total volume
▸ November 2: 46.0%
▸ November 5: 49.9%
▸ November 6: 54.2%
▸ November 11: 49.7%
In just six days, HIP-3’s share nearly quadrupled, briefly surpassing the volume generated by Hyperliquid’s native crypto markets.
That expansion is being driven by third-party teams introducing new trading markets directly onto HyperCore.
These include:
▸ Oil and natural gas
▸ Gold, silver, and other commodities
▸ US equities and semiconductor stocks
▸ Major equity indices
Rather than building separate exchanges, these teams can use Hyperliquid’s existing trading infrastructure to offer perpetual exposure to traditional financial markets.
The revenue breakdown adds another dimension.
Over the latest 30-day period, Hyperliquid generated:
▸ $89M in exchange fees
▸ $68.8M in protocol revenue
▸ Approximately $2.3M in daily revenue
▸ Just $848.5K in HyperEVM gas revenue
Trading activity continues to dominate Hyperliquid’s economics, with HyperEVM contributing only a small fraction of total revenue.
HIP-3 expands that trading business beyond crypto without requiring Hyperliquid to originate every new market.
But the distribution of volume reveals another development.
On November 9, @tradexyz controlled 98.6% of HIP-3 trading volume.
Despite permissionless market creation, activity remains heavily concentrated around a single builder.
This suggests that opening market deployment to third parties doesn’t automatically distribute liquidity equally across them.
The deeper implication is how Hyperliquid’s business model is evolving.
Third-party builders introduce new markets, traders provide volume, and Hyperliquid earns trading fees through the same underlying infrastructure.
For HYPE, this creates additional sources of fee-generating activity beyond crypto perpetuals, strengthening the relationship between broader market adoption and the protocol’s token economics.
Hyperliquid is gradually moving beyond competing for crypto derivatives volume toward becoming infrastructure for trading a wider range of financial assets.
And with HIP-3 already approaching half of exchange volume, that expansion is showing up in actual trading activity rather than remaining a product roadmap.

Financial privacy has economic value when disclosure changes how competitors trade, price risk or negotiate.
A market maker revealing inventory, an OTC desk exposing transaction size or a fund publishing treasury movements can surrender valuable information.
But concealing information from competitors is different from withholding evidence from authorized counterparties.
That’s the institutional use case behind @primus_labs’ FHE and zkTLS infrastructure.
FHE protects supported onchain balances and transactions. zkTLS authenticates external financial records without disclosing everything.
Five applications stand out.
1. Market-Making Inventory
Market makers rebalance inventory, hedge exposure and move collateral across venues.
Visible movements can reveal inventory pressure, helping competitors anticipate trades or adjust quotes.
Primus’s encrypted balances could protect supported onchain positions, while verification tools authenticate selected financial records.
External orders, hedges and wallet relationships may still be visible.
2. OTC Settlement
A desk negotiating a $20M purchase doesn’t want competitors knowing its available capital or urgency.
Counterparties still need settlement assurance.
Primus’s zkTLS could authenticate selected exchange-held balances, while confidential transfers protect supported settlement amounts.
But verified balances don’t prove legal ownership or that assets are unencumbered.
3. Institutional Lending
Credit underwriting relies on sensitive income, balance, repayment and collateral records.
Primus and Brevis are developing ZKredit on BNB Chain to verify selected external financial claims without exposing complete account histories.
Lenders could check eligibility thresholds while borrowers retain privacy.
Yet verified balances don’t guarantee repayment, and external collateral still requires enforceability.
ZKredit’s planned ListaDAO application remains a proof-of-concept direction.
4. Corporate Treasury
Public treasury transfers can expose suppliers, liquidity movements and operating expenses.
Creditors and auditors still need reliable reporting.
Primus’s Confidential Vault and reserve-verification integration with Unitas and Brevis demonstrate complementary capabilities: encrypted supported balances and authenticated inputs for verifiable aggregate calculations.
Selected financial claims can be checked without publishing every underlying position.
5. Payroll
Public stablecoin payroll can expose salaries, bonuses and compensation differences.
Primus and AllScale tested confidential payroll on BNB Chain using four fictional employee payments.
Amounts remained encrypted, recipients could view their own payments, and decrypted figures matched the payroll file.
Wallets, timestamps and transaction counts remained visible.
This was a limited technical validation, not a production payroll service.
The Deployment Gap
These applications aren’t equally mature.
Primus has demonstrated encrypted financial positions and reserve verification, completed a small payroll test, and is developing credit-verification infrastructure.
Complete private OTC settlement and market-making inventory protection need additional capabilities.
The economic logic remains clear: trading desks need inventory confidentiality, OTC participants need negotiating privacy, borrowers need protected financial histories, and businesses need confidential treasury and payroll operations.
None eliminates verification.
A reserve ratio can be checked. A collateral threshold verified. A payment reconciled.
The complete trading book, treasury structure or salary schedule doesn’t need to become public.


Proof-of-reserves can verify what’s reported, but stablecoin backing isn’t always visible onchain.
Some reserves sit in DeFi. Others sit on exchanges, where balances and liabilities aren’t publicly accessible.
That’s the gap @primus_labs is working to address with zkTLS, including through its integration with Perena and Brevis.
——
⬢ The Primus × Brevis Architecture
In April, Primus and Brevis deployed reserve verification for Perena’s USD* across six Solana protocols:
• Prime
• Nest
• Glow
• Onyc
• Marginfi
• Seedpool
Three components support the system:
→ Primus authenticates information from external sources.
→ Secure computing infrastructure helps process sensitive reserve data.
→ Brevis verifies that calculations using that data were performed correctly.
Together, they help turn reserve information into reports that can be checked independently.
——
⬢ Why Exchange Reserves Are Harder
The April announcement also identified Binance and Hyperliquid as targets for future verification.
Onchain reserves can often be inspected publicly. Exchange balances may only be available through private account records.
Primus uses zkTLS to authenticate data returned by external services without requiring them to expose their entire databases.
That data can then feed into verifiable reserve reports.
But confirming that an exchange reported a balance doesn’t prove the funds are fully available. Loans, hedges, collateral obligations and other liabilities still have to be considered.
——
⬢ Verification Is Not the Same as Coverage
Imagine a stablecoin backed by $100M:
• $40M in verified DeFi positions
• $35M in exchange accounts
• $25M in other assets
The system could verify all $40M in DeFi while covering only 40% of total backing.
The proof would be valid, but the reserve picture would remain incomplete.
That’s why the number of integrations tells us less than the share of total reserves actually covered.
——
⬢ What Primus Actually Contributes
Reserve verification involves three separate questions:
1. Primus: Did the information come from the stated source?
2. Brevis: Was the result calculated correctly from the supplied data?
3. Issuer or auditor: Does the report account for all backing assets and liabilities?
Primus handles data authentication. Brevis supports verifiable calculations. The issuer or auditor remains responsible for the completeness of the reserve accounts.
These roles complement one another, but they don’t replace one another.
——
Perena’s initial deployment covered six Solana protocols. Binance and Hyperliquid were named for expansion, but I haven’t independently confirmed that either integration is live.
Primus makes it possible to authenticate financial data that isn’t publicly available onchain.
What it cannot do is verify reserves or liabilities that were never included in the report.

Here’s a simple guide to completing KYC and opening a virtual card on @UstarPay.
①. Register through my referral link below, download the UstarPay app and log in.
②. Open the identity verification section and follow the instructions to complete KYC using your own valid documents.
③. Deposit enough funds into your wallet to cover the card-opening fee. The virtual card fee shown in this video is 9.9 USDT. Please check the current fee in the app.
④. Select “Apply for Card”, choose the virtual card and follow the instructions to set your transaction password.
⑤. Review your details and the applicable fee, then submit your application. You can check the application status in the app.
5 USDT Trial Credit giveaway
Up to 10 eligible users will each receive 5 USDT Trial Credit through a random draw.
To participate:
• Register through my referral link.
• Complete KYC verification.
• Comment your UstarPay UID below this post.
Trial Credit can only be used for card spending after your card is opened and activated. It cannot be withdrawn or transferred. A free card is not included, and card-opening fees still apply.
Check supported regions and applicable terms before registering.
Registration link:
register.ustarpay.com/regist…
#UstarPay
🤝 Paid partnership
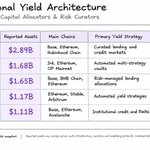
Five DeFi capital allocators and curators now represent roughly $8.5B in reported assets.
But they’re not running the same business.
The numbers:
- Steakhouse: $2.89B
- Veda: $1.68B
- Gauntlet: $1.65B
- Concrete: $1.17B
- Grove Finance: $1.11B
The distinction is in how that capital gets deployed.
1. @SteakhouseFi
Curates lending vaults across @Morpho, @Kamino and other markets, selecting risk parameters and credit exposures.
Its advantage is portfolio construction and risk management, rather than operating a new base lending protocol.
2. @veda_labs
Provides the BoringVault infrastructure behind automated financial strategies.
Deposits, accounting and strategy execution are separated into modules, with curator actions constrained by onchain whitelists.
3. @gauntlet_xyz
Uses quantitative risk models to manage lending allocations, collateral exposure and vault parameters.
It competes primarily on risk management and capital deployment.
4. @ConcreteXYZ
Packages automated multi-strategy vaults that can allocate capital across different yield sources.
But strategy permissions, accounting and withdrawal dependencies require as much attention as advertised returns.
4. @grovedotfinance
Operates within the @Skyecosystem, directing capital into institutional credit, including tokenized Treasuries, private credit and senior CLO exposure.
Its cross-chain allocation infrastructure connects DeFi liquidity with offchain credit markets.
Here’s the catch.
These aren’t five independent pools of capital.
Steakhouse and Gauntlet curate positions that can sit inside underlying lending protocols, while Veda and Concrete provide vault infrastructure. Reported balances can overlap.
And $8.5B in assets doesn’t establish institutional inflows, superior returns or better risk management.
I’d compare each allocator using four measurements:
Net yield after every fee
Asset and borrower transparency
Manager permissions and withdrawal liquidity
Realized losses and drawdowns
Capital allocated is the starting point.
The better business is the one that can demonstrate durable net returns while giving depositors sufficient control and visibility over the risks they’re financing.

A $100 depositor and a six-figure depositor can receive the same Genesis multiplier on Atoma.
That’s what I like about how @atoma_fi structured Convergence Chapter I: Formation.
Instead of rewarding larger wallets with better multipliers, the entire protocol shares one boost of 1.25x–2x, determined by total TVL at the snapshot.
More deposits can improve the multiplier for existing participants too.
The process is simple:
1. Choose an Atoma vault.
2. Deposit USDC by November 13.
3. Check your qualifying balance and multiplier in the app.
Existing depositors already qualify.
Personally, I prefer this approach because early participation is recognized without giving larger wallets a separate multiplier advantage.
The final boost isn’t guaranteed, applies only to Atoma Points, and doesn’t remove vault trading risks or epoch-based withdrawal delays.
app.atoma.fi

Lumen retweeted

If I had $500k in crypto now, I would:
1. Go full-time crypto. Move somewhere cheap. One year to make it.
2. No BTC, no ETH, no SOL, no HYPE.
3. No memecoins. No directional leverage.
4. Allocate $250k to a delta-neutral strategy between @tradexyz and @metricxyz.
-> Short equity perps trading at a premium on tradexyz, buy the matching tokenized equities on metricxyz.
One strategy, three potential airdrops: HL S3 + tradexyz + metricxyz.
5. Allocate $50k to prediction markets on HIP-4. Market make tradfi outcomes. If options launch, be ready to arb them against a broker from day one.
6. Deposit and loop $200k of sUSDe on Aave.
-> Deposit sUSDe, borrow USDC, swap into more sUSDe. Use the net yield and some of the principal to cover living expenses.
Rotate into @acier, an upcoming lending protocol, when it's live.
7. Build AI apps on @flop_labs during testnet.
-> Vibe code your own apps. Use free testnet inference to get your first users and position yourself for the FLOP agent airdrop.
The goal: stay consistent and optimistic while positioning myself for potentially huge airdrops.
One year. Locked in.
Only $81M of tokenized stocks are being used as lending collateral, despite a multibillion-dollar market.
The collateral race is already looking pretty one-sided.
Here’s where the capital sits:
1. Kamino Opening Bell: $38M deposits / $7.5M debt
2. Kamino xStocks: $29M / $5.2M
3. Kamino Sentora xStocks: $7.8M / $600K
4. Lista USD1/SPYB: $2.3M / $900K
The surprising part is the utilization.
Kamino’s two largest markets have less than 20% of deposited collateral reflected in outstanding debt, while Lista’s USD1/SPYB market is closer to 39%.
And Ondo, despite being one of the largest tokenized-stock issuers, had only $1,400 backing loans on Morpho in the same research snapshot.
So far, Solana has captured the bulk of tokenized-equity lending collateral.
But even there, deposits are growing much faster than actual borrowing.
The market has plenty of tokenized shares.
The shortage is productive credit demand against them.

A 50% reduction in clinical review time could be a bigger catalyst for $IRTC than another quarter of 20% revenue growth.
iRhythm’s newly cleared AI algorithm is expected to cut review time by roughly half and generate $100M in cumulative savings over five years.
The economics are already improving:
▸ Q2 revenue: $224.2M (+20.1%)
▸ Gross margin: 72.8%
▸ Adjusted EBITDA margin: 19.3%
Tonight’s earnings put those efficiency expectations under scrutiny.
But a strong report doesn’t guarantee a clean entry.
@bitget’s rIRTC offers extended-hours access, and its stock-linked liquidity can provide deeper execution than isolated token pools.
That can reduce slippage, although earnings spreads may still widen. I’d use limit orders and avoid oversized entries.
The larger thesis is simple: AI improving the economics of an established healthcare business, not just adding another growth narrative.
rIRTC: bitget.com/spot/RIRTCUSDT
@Bitget_TradFi #Bitget #TradFi
PS: Earnings volatility, thin liquidity and token-price deviations can cause losses. Regional restrictions apply.

Morpho and Fluid are competing for the same lending capital, but I think they’re solving two different problems.
Morpho wants to make capital allocation more efficient.
Fluid wants to make the capital itself work harder.
And that difference changes how lenders and borrowers earn, take risks, and use DeFi.
——
⬢ @Morpho
Traditional lending pools combine assets and borrowers under shared risk parameters.
Morpho takes a different approach.
Each lending market has its own collateral, oracle, liquidation settings, and interest rate model.
On top of these markets, independent curators manage vaults that allocate deposits across selected opportunities.
For example, a USDC depositor can enter a curated vault instead of choosing individual lending markets.
The curator decides where capital can go. Allocators manage deployment within those limits.
The depositor receives vault shares and earns returns from the underlying lending positions.
The advantage?
Specialization.
One vault can prioritize conservative collateral and liquidity. Another can accept additional risk in exchange for potentially higher lending returns.
But there’s a catch.
You’re not just evaluating Morpho. You’re evaluating the curator.
A poorly constructed vault can expose depositors to concentrated collateral risk, weak oracles, or insufficient withdrawal liquidity.
Morpho provides the infrastructure.
——
⬢ @0xFluid
Fluid approaches lending from a different direction.
Instead of focusing primarily on where deposits are allocated, it connects lending, borrowing, and DEX liquidity through its Liquidity Layer.
This creates two mechanisms:
• Smart Collateral: Supported collateral positions can simultaneously provide DEX liquidity and generate trading fees.
• Smart Debt: Supported debt positions can participate in DEX liquidity, with trading fees potentially reducing effective borrowing costs.
Consider someone who wants to borrow against an ETH-related position.
In a conventional lending setup, collateral is deposited to secure the loan.
On Fluid, supported Smart Collateral can also participate in trading activity.
So the same position can support borrowing while potentially generating swap fees.
That’s the capital-efficiency advantage.
But it comes with a tradeoff.
You’re introducing additional dependencies on DEX liquidity, trading activity, collateral pricing, and the protocol’s risk management.
More productive collateral doesn’t necessarily mean safer collateral.
——
⬢ Which Model Has Better Economics?
This is where I’d separate lenders from borrowers.
For a lender depositing USDC, Morpho’s curated vaults offer a way to access specialized lending strategies without managing each position individually.
The return depends on the markets selected, borrower demand, utilization, and curator decisions.
Fluid’s advantage becomes more apparent when collateral or debt can participate in additional financial activity.
For a borrower, trading fees earned through supported Smart Collateral or Smart Debt positions can improve effective borrowing economics.
But neither architecture automatically offers better rates.
A Morpho market with abundant liquidity could offer cheaper borrowing than a Fluid vault.
A Fluid position earning substantial trading fees could produce better net economics than a conventional collateralized loan.
It depends on the actual position.
And the risks are different.
Morpho emphasizes isolated lending markets with curator-directed allocation.
Fluid connects more activities through shared liquidity infrastructure.
One concentrates the allocation decision.
The other increases the number of things capital can do.
⬢ My Take
Morpho competes through better credit allocation, curator selection and isolated risk.
Fluid competes through capital efficiency, making collateral and debt more productive.
For passive lenders, I’d lean Morpho. For borrowers optimizing capital efficiency, Fluid has the stronger proposition.

Lumen retweeted

even though I've been rooting for Aerodrome to keep gaining overall DEX market share lately, I have nothing but the highest respect for Uniswap.
incredible how they've almost single-handedly kept eating market share from CEXs, now sitting at more than 31% of Binance's spot volume.
that makes Uniswap the #2 crypto exchange in the world, including all CEXs and DEXs.
let that sink in.
and it means even more when you consider how unfair the game actually is. CEXs are in a completely different position to exploit their advantages, and they do. shady backdoor deals and extractive market making give them nearly endless capital and capacity to compete.
DEXs have none of that. just a protocol living onchain, fully transparent, truly sticking to the crypto ethos. but they have the better product, and slowly but surely that's winning out.
we don't get a ton of success stories like this in crypto. but it's exactly these rare cases of real innovation that keep me going, regardless of bull or bear market.
incredible what we can build as an industry despite all the obstacles in our way. and long term, it's always good to be reminded that the good ones win.
love to see it, true inspiration for all builders out there that genuinely care about building something long lasting. the better product will always win, regardless how intimidating your competition and incumbents may look like.
job isn't done until we're at 100%.
