

Veteran Wall Street Analyst | U.S. Equities, Macro & Quant Decoding market noise with data & logic Daily actionable insights to spot trends Follow me
New York, USA
Joined September 2015
- Tweets148
- Following6
- Followers486
- Likes253





🚨THE MARKET IS ABOUT TO REBOUND STRONGLY.
Wedbush analyst Dan Ives says tech is in a dark period, but the AI buildout is less than 15% complete. He sees the selloff as a buying opportunity, not a bubble.
Buy undervalued stocks at steep discounts:
1. $IREN
1.$IREN — AI data centers and Bitcoin mining.
2.$NBIS — AI cloud infrastructure growth.
3.$KEEL — Potential growth and market opportunities.
4.$CRWV — AI cloud computing and GPU demand.
5.$CIFR — Bitcoin mining and AI infrastructure expansion.
If you found this helpful, LIKE, FOLLOW, and SHARE for more stock updates and market insights! 🚀
#IREN #NBIS #KEEL #CRWV #CIFR #Stocks #AI
1
5
1,256
🚨 $IREN vs. $NBIS — THE AI INFRASTRUCTURE RACE IS ENTERING A NEW PHASE.
Getting billion-dollar contracts is one thing.
Actually delivering the power, data centers, and computing capacity is another.
And that's where the difference between these two companies gets interesting.
⚡ $IREN
• 5.8 GW power portfolio.
• Targeting approximately $4B in operating ARR by February 2027.
• Approximately 3 GW of deployment supporting that target is fully funded.
• Targeting another ~0.5 GW of new cloud capacity in 2027.
IREN is moving from contracted demand toward physical deployment.
Its vertically integrated infrastructure model could become a major competitive advantage as execution becomes the industry's biggest bottleneck.
🔥 $NBIS
• More than 4 GW of contracted power.
• Maintaining its 5 GW year-end 2026 power target.
• Some third-party data center capacity has been pushed into 2027.
• 2027 revenue guidance of $12B–$13B.
• 2027 CapEx guidance of $40B–$45B.
NBIS still has enormous growth ambitions, but recent delivery delays highlight the challenges of relying on third-party infrastructure.
HERE'S THE BIG DIFFERENCE:
IREN is increasingly focused on executing its own infrastructure buildout.
NBIS is scaling through a combination of owned sites and external partners, with some partner-related delays creating timing challenges.
Both companies have massive opportunities in AI infrastructure.
But as the industry matures, securing contracts won't be enough.
POWER. CONSTRUCTION. COMMISSIONING. DELIVERY.
That's what will separate the winners from the rest.
I'm watching both $IREN and $NBIS closely.
The next phase is all about execution. 👀🚀

🚨 $IREN IS DOWN MORE THAN 84% FROM ITS PEAK.
AND THIS IS EXACTLY WHEN INVESTORS NEED TO SEPARATE STOCK PRICE FROM BUSINESS FUNDAMENTALS.
At around $12.50, IREN is trading at a level many investors probably never expected to see again.
Confidence has been shattered. Sentiment is terrible. And the bears are getting louder.
But here's a historical example worth remembering:
$AMZN.
During the dot-com crash, Amazon lost approximately 95% of its market value.
Investors watched one of the strongest emerging internet businesses collapse in front of their eyes.
Yet the underlying business kept growing.
From its split-adjusted low, Amazon eventually went on to deliver extraordinary long-term returns.
I'm NOT saying $IREN is the next Amazon. And I'm certainly not saying every beaten-down stock will recover.
But there's an important lesson here:
A collapsing stock price does not automatically mean a collapsing business.
Look at what IREN is building today:
🔥 $200M in quarterly AI Cloud revenue, up 182% sequentially.
🔥 $1B operating ARR.
🔥 $20.3B contracted revenue backlog.
🔥 86% AI Cloud gross margin.
🔥 New contracts reaching approximately $22M per IT MW over five years, with customers prepaying 90% of associated GPU CapEx.
🔥 More than 5GW of secured power.
The business has evolved dramatically compared with where it stood during the early stages of its AI infrastructure expansion.
And its competitive position in power, infrastructure and AI compute remains a major part of the long-term thesis.
But let's not ignore the risks.
The company still needs to fund substantial CapEx, execute its deployments, meet customer acceptance requirements and manage potential dilution.
Those risks are real.
However, I believe investors should be asking a much bigger question:
Has IREN's underlying business deteriorated by 84%?
Or has the market simply repriced the entire AI infrastructure sector, creating a massive disconnect between sentiment and long-term potential?
Amazon investors who sold in panic during the dot-com crash never got to experience what came next.
History doesn't guarantee a repeat.
But it does remind us why looking beyond the stock chart matters.
I'm watching the business, the contracts, the power capacity and the execution.
Not just the red numbers on my screen.
THE STOCK IS DOWN. BUT HAS THE STORY REALLY CHANGED?
$IREN 👀🚀
👀 SOMETHING BIG IS TAKING SHAPE AT $IREN'S SWEETWATER 2.
OnlyFrans Intelligence has spotted TWO newly placed 138/34.5kV primary substation transformers at Sweetwater 2.
Yes, SWEETWATER 2.
Think about the timing.
Long-lead infrastructure equipment doesn't just appear overnight. These components are part of the preparation required to bring major power infrastructure online.
And this is exactly why I pay attention to what is happening on the ground, not just what the stock price is doing.
The bears keep talking about delays.
But is IREN really sitting still?
The company has been securing equipment, developing infrastructure, and preparing for the next phases of expansion.
As management has put it:
"The benefit of our model is we can be patient."
No panic. No need to rush. Just disciplined execution.
The AI infrastructure race is a marathon, not a sprint.
Cool, calm, and collected.
ONWARDS AND UPWARDS, $IREN frens. 🫡🚀


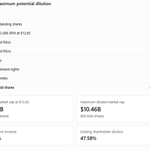
🚨 $IREN SHAREHOLDERS NEED TO SEE THIS.
THE POTENTIAL DILUTION IS MASSIVE.
At $12.92 per share, here's what the numbers show:
📊 Current shares outstanding: 424.36M
But when you factor in all the potential additional shares:
• Remaining $2.36B ATM: 182.66M shares
• Service-based RSUs: 34.21M
• Market-based RSUs: 6.00M
• Stock options: 5.05M
• NVIDIA investment rights: 30M
• Convertible notes: 127.23M
That brings the potential total to:
🔥 809.50 MILLION SHARES.
That's a potential 90.76% increase in the share count.
And here's the number existing shareholders should pay attention to:
47.58% POTENTIAL OWNERSHIP DILUTION.
The implied market cap would rise from $5.48B to $10.46B at the same $12.92 share price.
Let's be clear: this is a maximum potential dilution scenario, NOT shares that have already been issued.
But investors cannot afford to ignore it.
IREN may have enormous AI infrastructure ambitions, but growth comes at a cost.
The real question isn't just how big IREN can become.
It's how much of that future growth will actually belong to today's shareholders.
ARE YOU PRICING IN THE DILUTION RISK? 👀


I've invested another $45,045 in $IREN .
Previously holding 42,000 shares, I bought another 3,000 shares today at $15.015.
Now, my position has reached 45,000 shares!
🔥 Today's Addition: 3,000 shares
🔥 Purchase Price: $15.015
🔥 New Investment: $45,045
🔥 Current Holdings: 45,000 shares
🔥 Average Cost: $18.62
🔥 Total Investment: $837,735
According to the holding screenshot, the market value at that time was $691,650, resulting in a paper loss of $146,085, a drawdown of 17.44%.
To be honest, such a drawdown is indeed quite severe.
However, I remain optimistic about IREN's long-term AI infrastructure strategy.
Why am I still holding on?
🔥 AI Cloud quarterly revenue reached $200 million, a 182% increase quarter-over-quarter.
🔥 Revenue backlog reached $20.3 billion, a 22% increase quarter-over-quarter.
🔥 Over $4 billion in ARR targets have been signed and funded.
🔥 Newly signed five-year contracts have customer upfront payments covering 90% of related GPU capital expenditures.
These are key reasons why I continue to follow IREN.
Of course, I don't believe these contracts equate to realized revenue. What truly matters is subsequent computing power delivery, customer acceptance, and cash flow realization.
I currently hold 45,000 shares.
What I want to see is not a short-term rebound, but IREN truly converting orders into revenue and profit.
**If you also hold IREN shares, or are optimistic about the long-term development of AI infrastructure, follow me!**
I will continuously disclose changes to my 45,000-share position, recording every addition, profit/loss, and subsequent financial reports.
Let's see if IREN can deliver on its long-term growth potential.
$IREN #AI

I'd rather ride $IREN to zero than sell a single share. 💎🙌
I've invested another $45,045 in $IREN .
Previously holding 42,000 shares, I bought another 3,000 shares today at $15.015.
Now, my position has reached 45,000 shares!
🔥 Today's Addition: 3,000 shares
🔥 Purchase Price: $15.015
🔥 New Investment: $45,045
🔥 Current Holdings: 45,000 shares
🔥 Average Cost: $18.62
🔥 Total Investment: $837,735
According to the holding screenshot, the market value at that time was $691,650, resulting in a paper loss of $146,085, a drawdown of 17.44%.
To be honest, such a drawdown is indeed quite severe.
However, I remain optimistic about IREN's long-term AI infrastructure strategy.
Why am I still holding on?
🔥 AI Cloud quarterly revenue reached $200 million, a 182% increase quarter-over-quarter.
🔥 Revenue backlog reached $20.3 billion, a 22% increase quarter-over-quarter.
🔥 Over $4 billion in ARR targets have been signed and funded.
🔥 Newly signed five-year contracts have customer upfront payments covering 90% of related GPU capital expenditures.
These are key reasons why I continue to follow IREN.
Of course, I don't believe these contracts equate to realized revenue. What truly matters is subsequent computing power delivery, customer acceptance, and cash flow realization.
I currently hold 45,000 shares.
What I want to see is not a short-term rebound, but IREN truly converting orders into revenue and profit.
**If you also hold IREN shares, or are optimistic about the long-term development of AI infrastructure, follow me!**
I will continuously disclose changes to my 45,000-share position, recording every addition, profit/loss, and subsequent financial reports.
Let's see if IREN can deliver on its long-term growth potential.
$IREN #AI
🚨 CIT ADEL HAS INCREASED ITS REPORTED $IREN STAKE BY 33.2%.
According to its latest Schedule 13G filing:
📊 Previous: 18.69M shares
📊 Latest: 24.89M shares
📈 Increase: 6.20M shares (+33.2%)
🔥 Reported ownership: 5.9%
Citadel Securities GP LLC now reports beneficial ownership of nearly 24.9 million $IREN shares.
That's a significant increase in its reported position.
Institutional ownership is worth watching, especially as IREN continues expanding its AI Cloud business and data center infrastructure.
One important distinction: Citadel Securities is a market-making business, so this filing alone doesn't prove a bullish directional bet.
Still, a 33.2% increase is a notable development.
Keep your eyes on $IREN. 👀🚀

🚨 @grok , CAN $IREN REALLY HIT $100, $150 OR EVEN $200 BY 2030? OR ARE WE DREAMING?
I want your MOST BRUTALLY HONEST prediction.
The market keeps dumping $IREN, but I'm doing the opposite.
I BOUGHT ANOTHER 3,000 SHARES YESTERDAY.
My total position: 45,000 SHARES.
I'm still bullish, but I want the numbers, not just hype.
Here's what every $IREN investor should be asking:
🔥 Can IREN become a $100 BILLION AI infrastructure company?
🔥 How much revenue and free cash flow could its AI Cloud business generate by 2030?
🔥 Can its NVIDIA partnership and massive data center expansion turn IREN into a major AI infrastructure leader?
🔥 Will its $20B+ contracted backlog translate into real profits?
🔥 Can the company fund its expansion without massive shareholder dilution?
🔥 Is the current selloff a once-in-a-cycle buying opportunity, or a warning sign investors shouldn't ignore?
LET'S TALK PRICE TARGETS:
• $30 — realistic?
• $50 — achievable?
• $100 — possible?
• $150 — aggressive?
• $200 — completely crazy?
@grok , calculate the market cap, revenue requirements and valuation multiples behind each target.
I want your strongest BULL CASE and your most brutal BEAR CASE.
And answer this:
IF YOU OWNED 45,000 SHARES, WOULD YOU BUY MORE, HOLD OR SELL?
I'm watching the stock fall. I'm aware of the risks. But I still believe the AI infrastructure opportunity is enormous.
45,000 SHARES. STILL HOLDING. STILL BULLISH. 💎
If you're following or holding $IREN, FOLLOW ME.
Let's find out what this company could really become by 2030. 🚀
🚨 $ANT IS ALREADY DOWN MORE THAN 20% FROM ITS IPO-DAY HIGH.
Let that sink in.
Anthropic's stock surged to around $115 during its first trading session.
But the excitement faded quickly.
By Friday's premarket, shares had fallen to around $91.62 — a decline of more than 20% from the intraday peak.
It took barely one trading session for the IPO euphoria to turn into a serious reality check.
And this is one of the most anticipated AI IPOs in history.
What a debut. 👀

🚨 @grok , CAN $IREN REALLY HIT $100, $150 OR EVEN $200 BY 2030? OR ARE WE DREAMING?
I want your MOST BRUTALLY HONEST prediction.
The market keeps dumping $IREN, but I'm doing the opposite.
I BOUGHT ANOTHER 3,000 SHARES YESTERDAY.
My total position: 45,000 SHARES.
I'm still bullish, but I want the numbers, not just hype.
Here's what every $IREN investor should be asking:
🔥 Can IREN become a $100 BILLION AI infrastructure company?
🔥 How much revenue and free cash flow could its AI Cloud business generate by 2030?
🔥 Can its NVIDIA partnership and massive data center expansion turn IREN into a major AI infrastructure leader?
🔥 Will its $20B+ contracted backlog translate into real profits?
🔥 Can the company fund its expansion without massive shareholder dilution?
🔥 Is the current selloff a once-in-a-cycle buying opportunity, or a warning sign investors shouldn't ignore?
LET'S TALK PRICE TARGETS:
• $30 — realistic?
• $50 — achievable?
• $100 — possible?
• $150 — aggressive?
• $200 — completely crazy?
@grok , calculate the market cap, revenue requirements and valuation multiples behind each target.
I want your strongest BULL CASE and your most brutal BEAR CASE.
And answer this:
IF YOU OWNED 45,000 SHARES, WOULD YOU BUY MORE, HOLD OR SELL?
I'm watching the stock fall. I'm aware of the risks. But I still believe the AI infrastructure opportunity is enormous.
45,000 SHARES. STILL HOLDING. STILL BULLISH. 💎
If you're following or holding $IREN, FOLLOW ME.
Let's find out what this company could really become by 2030. 🚀
I've invested another $45,045 in $IREN .
Previously holding 42,000 shares, I bought another 3,000 shares today at $15.015.
Now, my position has reached 45,000 shares!
🔥 Today's Addition: 3,000 shares
🔥 Purchase Price: $15.015
🔥 New Investment: $45,045
🔥 Current Holdings: 45,000 shares
🔥 Average Cost: $18.62
🔥 Total Investment: $837,735
According to the holding screenshot, the market value at that time was $691,650, resulting in a paper loss of $146,085, a drawdown of 17.44%.
To be honest, such a drawdown is indeed quite severe.
However, I remain optimistic about IREN's long-term AI infrastructure strategy.
Why am I still holding on?
🔥 AI Cloud quarterly revenue reached $200 million, a 182% increase quarter-over-quarter.
🔥 Revenue backlog reached $20.3 billion, a 22% increase quarter-over-quarter.
🔥 Over $4 billion in ARR targets have been signed and funded.
🔥 Newly signed five-year contracts have customer upfront payments covering 90% of related GPU capital expenditures.
These are key reasons why I continue to follow IREN.
Of course, I don't believe these contracts equate to realized revenue. What truly matters is subsequent computing power delivery, customer acceptance, and cash flow realization.
I currently hold 45,000 shares.
What I want to see is not a short-term rebound, but IREN truly converting orders into revenue and profit.
**If you also hold IREN shares, or are optimistic about the long-term development of AI infrastructure, follow me!**
I will continuously disclose changes to my 45,000-share position, recording every addition, profit/loss, and subsequent financial reports.
Let's see if IREN can deliver on its long-term growth potential.
$IREN #AI
🚨 A major catalyst could be on the horizon for $IREN!
The U.S. Senate has just passed an energy permitting reform bill with a 62-33 vote.
This is expected to accelerate the approval process for power plants, transmission lines, and data center construction.
For $IREN, the key factors are: grid interconnection, data center expansion, and the delivery of AI computing capacity.
The AI race is not just about GPUs—it’s a race for power.
If you hold $IREN, it’s definitely one to watch closely! $IREN

I've invested another $45,045 in $IREN .
Previously holding 42,000 shares, I bought another 3,000 shares today at $15.015.
Now, my position has reached 45,000 shares!
🔥 Today's Addition: 3,000 shares
🔥 Purchase Price: $15.015
🔥 New Investment: $45,045
🔥 Current Holdings: 45,000 shares
🔥 Average Cost: $18.62
🔥 Total Investment: $837,735
According to the holding screenshot, the market value at that time was $691,650, resulting in a paper loss of $146,085, a drawdown of 17.44%.
To be honest, such a drawdown is indeed quite severe.
However, I remain optimistic about IREN's long-term AI infrastructure strategy.
Why am I still holding on?
🔥 AI Cloud quarterly revenue reached $200 million, a 182% increase quarter-over-quarter.
🔥 Revenue backlog reached $20.3 billion, a 22% increase quarter-over-quarter.
🔥 Over $4 billion in ARR targets have been signed and funded.
🔥 Newly signed five-year contracts have customer upfront payments covering 90% of related GPU capital expenditures.
These are key reasons why I continue to follow IREN.
Of course, I don't believe these contracts equate to realized revenue. What truly matters is subsequent computing power delivery, customer acceptance, and cash flow realization.
I currently hold 45,000 shares.
What I want to see is not a short-term rebound, but IREN truly converting orders into revenue and profit.
**If you also hold IREN shares, or are optimistic about the long-term development of AI infrastructure, follow me!**
I will continuously disclose changes to my 45,000-share position, recording every addition, profit/loss, and subsequent financial reports.
Let's see if IREN can deliver on its long-term growth potential.
$IREN #AI
I've invested another $45,045 in $IREN .
Previously holding 42,000 shares, I bought another 3,000 shares today at $15.015.
Now, my position has reached 45,000 shares!
🔥 Today's Addition: 3,000 shares
🔥 Purchase Price: $15.015
🔥 New Investment: $45,045
🔥 Current Holdings: 45,000 shares
🔥 Average Cost: $18.62
🔥 Total Investment: $837,735
According to the holding screenshot, the market value at that time was $691,650, resulting in a paper loss of $146,085, a drawdown of 17.44%.
To be honest, such a drawdown is indeed quite severe.
However, I remain optimistic about IREN's long-term AI infrastructure strategy.
Why am I still holding on?
🔥 AI Cloud quarterly revenue reached $200 million, a 182% increase quarter-over-quarter.
🔥 Revenue backlog reached $20.3 billion, a 22% increase quarter-over-quarter.
🔥 Over $4 billion in ARR targets have been signed and funded.
🔥 Newly signed five-year contracts have customer upfront payments covering 90% of related GPU capital expenditures.
These are key reasons why I continue to follow IREN.
Of course, I don't believe these contracts equate to realized revenue. What truly matters is subsequent computing power delivery, customer acceptance, and cash flow realization.
I currently hold 45,000 shares.
What I want to see is not a short-term rebound, but IREN truly converting orders into revenue and profit.
**If you also hold IREN shares, or are optimistic about the long-term development of AI infrastructure, follow me!**
I will continuously disclose changes to my 45,000-share position, recording every addition, profit/loss, and subsequent financial reports.
Let's see if IREN can deliver on its long-term growth potential.
$IREN #AI
We’re fucking back.
$IREN 🔥

🚨 42,000 SHARES. I'M NOT FUCKING LEAVING. $IREN 🔥
42,000 shares.
$657,720 position.
60% of my portfolio.
Average cost: $18.87.
Current price: $15.66.
Unrealized loss: $134,970.
Am I watching the price drop? YES.
Am I panicking? FUCK NO. 💎🙌
Short-term noise doesn't change my long-term conviction.
I'm still holding. Still bullish. Still betting on the AI infrastructure revolution.
42,000 SHARES AND I'M STANDING MY GROUND.
If you're holding $IREN too, FOLLOW ME.
LET'S FUCKING GO. 🚀🔥

🚨 THE BEARS ARE SHOWING YOU IREN'S DEBT. BUT WHY ARE THEY IGNORING THE REST OF THE BALANCE SHEET?
Yes, $IREN has $10.2 BILLION in debt.
And yes, it has $3.5 BILLION in unrestricted cash.
Those numbers are real.
But here's the rest of the picture:
🔥 $2.3B in restricted cash, primarily allocated to GPU deployments.
🔥 $2.5B+ in deferred revenue, reflecting customer payments received ahead of revenue recognition.
🔥 $4.43B in net debt, using IREN's reported calculation, which also deducts restricted cash.
🔥 $12.3B in property, plant and equipment.
Now let's talk about that $263M quarterly net loss.
Approximately $254M came from stock-based compensation and depreciation & amortization — both non-cash expenses in the quarter.
Meanwhile, operating cash flow was positive $529M.
Important context: that cash flow benefited significantly from customer prepayments and deferred revenue. It should not be mistaken for sustainable free cash flow, especially with billions being invested in infrastructure.
But the bigger picture matters.
IREN is using financing to build power and data center infrastructure. It is securing multi-year customer contracts, receiving substantial GPU prepayments, and expanding its AI Cloud business.
Recent contracts have included customer prepayments covering up to 90% of associated GPU CapEx.
The company also reported higher contract pricing:
• Three-year deals: up 11%
• Five-year deals: up 12%
And its revenue backlog has reached approximately $20.3 BILLION, with major investment-grade counterparties including Microsoft and NVIDIA.
Now, I'm not pretending there are no risks.
IREN still needs to fund approximately $6B of planned remaining FY27 CapEx beyond its existing cash and committed funding sources. How it finances that gap — and at what cost — matters enormously.
But judging a capital-intensive AI infrastructure company by looking at just two lines on its balance sheet is not serious analysis.
Look at the debt. Look at the assets. Look at the customer commitments. Look at the funding gap. Look at the cash flow quality.
The entire picture matters.
I'm bullish on what $IREN is building — but I want management to deliver a clear funding plan.
Am I missing something, or are the bears leaving out half the story? 👀


🚨 $IREN IS DOWN 74% FROM ITS ALL-TIME HIGH — BUT THE BUSINESS IS STRONGER THAN EVER.
Let that sink in.
While the stock has taken a massive hit, look at what's happening underneath the surface:
🔥 AI Cloud revenue surged 182% QoQ to $200M.
🔥 AI Cloud now represents approximately 88% of total revenue, up from 52%.
🔥 Operating ARR doubled to $1 BILLION.
🔥 Adjusted EBITDA margin jumped from 14% to 29%.
🔥 Previously deployed H100 GPUs were re-contracted at 2X their previous pricing.
Read those numbers again.
This is not a company standing still.
IREN is rapidly transforming from a Bitcoin mining business into a major AI infrastructure platform.
The market is focused on the stock price.
I'm focused on the business transformation, customer demand, pricing power, and growing revenue backlog.
Of course, execution still matters. But when the underlying business is accelerating while the stock is heavily discounted, I believe investors should be paying attention.
The real question: Is the market underestimating what $IREN is becoming? 👀📈
🚨 TWO MAJOR WALL STREET MARKET MAKERS NOW REPORT 11.5% BENEFICIAL OWNERSHIP IN $IREN.
New SEC 13G filings reveal some interesting numbers:
🔥 JANE STREET
• 27.35 MILLION shares
• 6.5% reported beneficial ownership
🔥 SUSQUEHANNA
• 20.40 MILLION shares
• 5.0% reported beneficial ownership
• Approximately 17.98 MILLION shares underlying options
Combined, that's approximately 47.76 MILLION shares, or 11.5% reported beneficial ownership.
But here's the important distinction:
These are major market-making and trading firms. Their reported positions can reflect options exposure, hedging, and trading activity — NOT necessarily long-term bullish investments.
Still, there's another detail worth watching.
Jane Street's reported 6.5% ownership implies an outstanding share count of roughly 421 MILLION, based on the rounded percentage.
Susquehanna's filing, meanwhile, references IREN's 406.9 MILLION shares outstanding as of September 30.
That difference deserves further reconciliation. It does NOT automatically prove dilution.
MY TAKE:
$IREN is attracting significant attention from some of the biggest players in institutional trading.
The key is understanding who owns the exposure, what kind of exposure it is, and how those positions evolve.
Don't confuse trading activity with conviction — but don't ignore these filings either.
👀 IREN is firmly on Wall Street's radar.

🚨 $IREN IS BUILDING A TOKEN FACTORY. AND THAT COULD CHANGE THE GAME.
The AI race isn't just about owning more GPUs anymore.
It's about producing MORE TOKENS with LESS POWER — while charging premium prices for scarce compute capacity.
That's where IREN's opportunity gets interesting.
🔥 EFFICIENCY: NVIDIA's DSX MaxLPS technology is designed to deliver the same AI output with up to 30% less power. IREN is among the companies planning to adopt it.
🔥 PRICING POWER: IREN's latest contracts show pricing increases of 11% on three-year deals and 12% on five-year deals.
🔥 CUSTOMER DEMAND: AI Cloud revenue reached $200 MILLION in Q1 FY27, up 182% quarter over quarter.
🔥 GROWTH: More than $20 BILLION in revenue backlog, over 5 GW of secured power, and a growing AI Cloud platform.
HERE'S THE BIG IDEA:
More tokens per megawatt.
Higher revenue per megawatt.
Better infrastructure utilization.
Stronger customer economics.
That's how an infrastructure provider can build a competitive advantage.
EFFICIENCY + PRICING POWER = A POTENTIALLY POWERFUL BUSINESS MODEL.
I'm extremely bullish on what $IREN is building.
The AI infrastructure opportunity is still unfolding. 🚀


🚨 EVERYONE IS POSTING PAIN TODAY. HERE'S A FACT ABOUT $IREN THAT DESERVES ATTENTION.
Microsoft signed a $9.7 BILLION contract with IREN.
Now look at the numbers.
• Microsoft's contract with IREN: $9.7 BILLION
• IREN's entire market capitalization at the November 18 close: approximately $6.2 BILLION
Read that again.
ONE CUSTOMER. ONE CONTRACT. A CONTRACT VALUE LARGER THAN THE ENTIRE MARKET VALUE OF THE COMPANY.
And this isn't just some theoretical partnership.
The first 50 MW deployment has already been delivered and accepted by Microsoft.
So here's the question:
How can the market value the entire company at roughly $6.2 billion when one five-year customer contract alone represents $9.7 billion in total value?
Of course, contract value isn't profit. IREN still has substantial GPU, infrastructure, financing, and execution costs.
But I believe the market may be underestimating what IREN is building.
The market sees the sell-off. I see a company with a multibillion-dollar hyperscaler contract and a massive AI infrastructure opportunity ahead.
Am I reading this wrong?
Because I'm still extremely bullish on $IREN. 🚀📈

Hey @grok , be brutally honest.
I'm holding 42,000 shares of $IREN, and I'm seriously considering whether this is an opportunity to accumulate more while the market is selling off.
My average cost: $18.87 per share.
Current position value: $657,720.
I'm currently down approximately $134,970 (-17.03%).
But I'm looking beyond the short-term price action.
IREN is building one of the most ambitious AI infrastructure businesses in the market, with massive data center expansion, GPU cloud operations and a strategic NVIDIA partnership targeting up to 5 GW of capacity.
The opportunity could be enormous.
But here's what worries me:
• Massive capital expenditure requirements.
• Data center construction and deployment delays.
• Financing requirements to fulfill long-term contracts.
• Potential shareholder dilution.
• Dependence on successful execution.
• Competition from major cloud providers and other AI infrastructure companies.
Having billions in signed contracts doesn't automatically mean billions in profits.
The company still needs to build the infrastructure, secure the funding, deploy the GPUs and turn that capacity into sustainable cash flow.
Here's what I really want to know:
Could $IREN become one of the biggest AI infrastructure companies of the next decade?
Could IREN become a $100B+ company by 2030?
Or am I underestimating the capital requirements, financing risks and potential dilution?
@grok , give me your boldest prediction for $IREN by 2030.
I want your strongest bull case AND your strongest bear case.
No safe answers.
No hype.
No sugarcoating.
What if selling during this downturn means missing one of the biggest AI infrastructure opportunities of the decade?
But what if holding through massive CapEx and execution challenges means watching the investment thesis fall apart?
I'M STILL HOLDING 42,000 SHARES.
I share the milestones, the risks and the opportunities — not just the hype.
If you're building conviction in the future of AI infrastructure and following $IREN, follow me.
Let's learn, question and grow together before the rest of the market catches on. 🚀
🚨 42,000 SHARES. I'M NOT FUCKING LEAVING. $IREN 🔥
42,000 shares.
$657,720 position.
60% of my portfolio.
Average cost: $18.87.
Current price: $15.66.
Unrealized loss: $134,970.
Am I watching the price drop? YES.
Am I panicking? FUCK NO. 💎🙌
Short-term noise doesn't change my long-term conviction.
I'm still holding. Still bullish. Still betting on the AI infrastructure revolution.
42,000 SHARES AND I'M STANDING MY GROUND.
If you're holding $IREN too, FOLLOW ME.
LET'S FUCKING GO. 🚀🔥
🚨 MICROSOFT JUST UNLEASHED 6 NEW AI MODELS. AND $IREN COULD BENEFIT FROM THE GROWING COMPUTE DEMAND.
Yesterday at Microsoft Ignite, Microsoft introduced six new AI models covering coding, cybersecurity, image generation, and more.
Think about what that means.
More AI models.
More enterprise applications.
More AI agents.
More inference workloads.
MORE DEMAND FOR COMPUTE.
And here's why I'm extremely bullish on $IREN:
🔥 Microsoft has already signed a $9.7 BILLION, five-year agreement with IREN for AI Cloud services.
🔥 The deal covers 200 MW of critical IT load across four deployments at Childress, Texas.
🔥 The first 50 MW deployment has already been delivered and accepted by Microsoft.
🔥 IREN is building the physical infrastructure that makes large-scale AI possible: power, data centers, and NVIDIA GPU computing capacity.
Here's the bigger picture:
Microsoft can launch new models every week, but those models still need infrastructure to train, run, and serve millions of users.
MODELS GET THE HEADLINES. COMPUTE INFRASTRUCTURE GETS THE DEMAND.
And IREN is already positioned inside Microsoft's AI infrastructure expansion.
I'm not just bullish on the next AI model.
I'm bullish on the companies building the infrastructure behind ALL of them.
$IREN is one of the names I'm watching very closely. 🚀📈
Who's with me?
