

Follow for market edge | https://nitter.cf/t.co/gD5jgim7ty Research Analyst: William O'Neil India Private Limited. SEBI Regn. Nos: INH000015543 valid till 18 Mar 2029
Karnataka, India
Joined November 2016
- Tweets11.7K
- Following208
- Followers15.2K
- Likes1K






Pinned Tweet
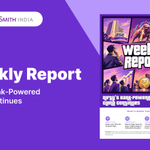
Our Latest Weekly Report is out — read, reflect, and share your thoughts in the comments.
What’s Inside This Report?
· Market Outlook: Banks Lead, Nifty Hits 10-Month High
· Learning Article: Ride the Rally, Keep the Gains: O'Neil's Guide to Selling With Discipline
· Featured Article: The Subsidiary That Costs More Than Its Parent
· Idea Lists: Five Stocks to Watch Right Now
This report highlights the key themes shaping markets and investment opportunities, with the Market Outlook: Banks Lead, Nifty Hits 10-Month High examining how strong banking sector performance, renewed institutional buying, and sustained market momentum have pushed the Nifty to a 10-month high, reinforcing the Confirmed Uptrend while emphasizing selective stock picking and disciplined portfolio management. Learning Article: Ride the Rally, Keep the Gains: O'Neil's Guide to Selling With Discipline explains how investors can protect their gains through systematic profit booking, the 20–25% selling rule, the eight-week holding exception, and disciplined risk management to avoid giving back hard-earned profits. In the Featured Article: The Subsidiary That Costs More Than Its Parent, we analyze Mahanadi Coalfields' IPO, exploring its valuation premium over parent company Coal India, strong operational profitability, declining earnings, and subdued investor subscription response to understand the factors shaping its investment appeal. Finally, Idea Lists: Five Stocks to Watch Right Now features technically strong companies exhibiting robust relative strength, healthy buyer demand, and promising breakout potential supported by institutional accumulation.
Read the full report here: zurl.co/eRhlk
#MarketSmithIndia #WeeklyReport #ONeilMethodology #StockMarketIndia #Investing #Trading #GrowthStocks #PortfolioStrategy #IndianEquities #SmartInvesting

1
1
684
Foreign investors put Rs 84,291 crore into Indian equities in the first half of November. About half went to one sector.
NSDL data (1–15 Nov):
Financial Services: +Rs 43,102 crore
Capital Goods: -Rs 3,781 crore.

1
656
Capital goods saw net foreign selling.
Jyoti CNC Automation's foreign holding used 6.07% of its permitted limit at 30 September, versus 10.69% a year earlier.
The sector mix changed sharply: financial services was a net sale in the previous fortnight.
1
56
Two risks:
Concentration: foreign buying focused on financial services, while the broader rally remained narrow.
Broadening: renewed demand could reach sectors left behind.
No forecast. The next read is NSDL's 16–30 November sector data.
#MarketSmithIndia #FPI #IndianStockMarket #InstitutionalInvestors #MarketOutlook
39
Foreign investors bought on all five days this week. Domestic institutions sold on four. Which side decides December?
57%Foreign buying broadens
0%Domestic selling persists
43%Rupee keeps firming
0%Q2 GDP on 30 Nov
7 votes • 19 hours 1
1
663
"As a principle, some aspect of inflation we put into our pricing when we quote
to defense, because in the past, we have suffered on this account."
Sorab Agarwal, Executive Director of Action Construction Equipment, on the Q2 FY27 earnings call, 13 November.
The question was whether long defence and export contracts block price increases. The answer: once a large order is 'fixed and frozen, the prices don't change'. Inflation can be discussed only on a fresh requirement.
Why it mattered this week: input costs are rising across industry, and the same call said steel reached 'multi-year highs in October'. A fixed-price order book turns that into a margin question, and the cushion is set on the day the bid goes in.
The tension: an inflation buffer priced into a bid is an estimate. If costs run past it before delivery, the supplier absorbs the gap.

1
671
Strong earnings. Higher growth guidance. Yet stocks are falling!
From HFCL and Sterlite Technologies to Acutaas and Alembic Pharma, the market is sending mixed signals.
The hidden twist? Earnings strength isn't enough when market sentiment turns against a crowded theme. 👀
Which companies are truly winning?
Read more: zurl.co/Crg6k
#EarningsSeason #Nifty500 #IndianStocks #EarningsAnalysis #GrowthInvesting #MarketSmithIndia

1
827
A 39-week base is a long one. Length is not the flaw; it is the time sellers need to run out.
Most bases last 7 to 15 weeks. When one runs to nine months, the chart is saying supply took longer to clear: holders from the old high, traders who bought the first bounce, and funds trimming into every rally.
What length changes: a long base tends to be wider and choppier, with several false starts inside it. What to read is the right side. Do the down weeks come on lighter volume than the up weeks, and does the base tighten as it nears the top of its range?
State Bank of India is building one in MarketSmith India data: consolidation, 39 weeks long, depth in the mid-20s percent band, stage 2, still forming.
The business underneath, from the Q2 FY27 press release, 3 November: 'Whole Bank Advances growth at 17.84% YoY', while 'Whole Bank Deposits grew by 12.27% YoY'. CASA ratio 38.32% at 30 September.
The tension: the group around it has moved fast, Banks-Money Center at 26 from 148 in 13 weeks, while the base itself is not finished. A long base still forming is a lesson in patience, not a buy signal.


1
711
137 electrical-equipment stocks have dropped in group rank four weeks running: 90, 109, 113, and now 128.
Four Saturday readings, each lower than the last (1 is strongest). Thirteen weeks ago the group stood at 51. The full board, group rank now against 13 weeks ago, in the latest MarketSmith India group data:
Climbing
Bldg-A/C & Heating Prds: 67, from 174 (12 stocks)
Tobacco: 84, from 170 (6 stocks)
Bldg-Cement/Concrt/Ag: 88, from 152 (45 stocks)
Cosmetics/Personal Care: 82, from 145 (38 stocks)
Telecom Svcs-Wireless: 34, from 102 (6 stocks)
Slipping
Electrical-Power/Equipmt: 128, from 51 (137 stocks)
Mining-Metal Ores: 160, from 75 (27 stocks)
Mining-Gold/Silver/Gems: 149, from 31 (8 stocks)
Oil&Gas-Machinery/Equip: 150, from 15 (7 stocks)
Follow-up from last Saturday: money-centre banks were 67 two weeks ago and 36 last week. They are 26 now.
The odd line: the rank slide and the flow data agree. In NSDL's sector data for 1 to 15 November, capital goods was the one large sector foreign investors sold while they bought almost everything else. Sunday's deep dive picks that up.
The caution: ranks measure relative strength, not earnings. Tobacco and Telecom Svcs-Wireless are six-stock groups, where one or two names can move the whole rank.

2
701
A group ranking is a map, not a verdict
A group can rank well while most companies inside it are ordinary. The ranking is useful because it tells you where to investigate next, not what conclusion to draw.
#CANSLIM #SupplyAndDemand #Volume #Float #IndianStockMarket #GrowthStocks #InvestingDiscipline #MarketSmithIndia
1
3
716
Then move down one level. Compare each company's earnings and sales evidence with its relative strength and price-and-volume record. MarketSmith India's 197 Industry Groups organize that first pass.
1
1
122
Context, not conclusion.
Disclaimer: Information contained herein is not and should not be construed as an offer, solicitation, or recommendation to buy or sell securities. It is for educational purposes only.
Legal disclosures: marketsmithindia.com/legalAg…

1
113
Bank of Maharashtra grew advances 30% in a year. Half of its large-corporate loan growth was booked at a single GIFT City branch.
Q2 FY27 earnings call (held 26 October, transcript filed 29 October) and the results release. Public-sector and private banks led today's market; this is the funding detail behind one of the fastest loan books in the group.
Where the loans went
— Advances: up 30% on the year; excluding the international banking unit (IBU), 23%
— Large credit added: Rs 36,000 crore, Rs 18,000 crore of it at the GIFT City IBU branch
— Domestic large credit: the other Rs 18,000 crore, a 19% growth rate
What paid for it
— IBU book of about Rs 18,500 crore, leveraged on roughly Rs 7,800–8,000 crore of FCNR(B) deposits
— Deposits: up 22%; 19% excluding FCNR(B)
— CASA: up 12%, with Rs 19,000 crore added over the last financial year
— Domestic CASA share: 46.47%, from 50.35% a year earlier
The tension: the FCNR(B) route that funded the IBU book is, in the MD's words, a window that 'is not there' going forward, and the IBU yield was not given on the call.

2
717
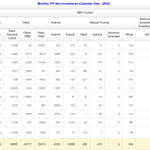
Foreign portfolio investors have bought Rs 1,22,265 crore of Indian equity so far in November. The calendar year is still Rs 1,72,880 crore in the red.
NSDL's calendar-year FPI report, equity column, updated to 20 November. Banks led today's session; the flow below is the backdrop the market is talking about.
November against 2026
— November to date: Rs 1,22,265 crore, larger than the previous monthly record of Rs 70,896 crore
(November 2020)
— The three earlier buying months of 2026 combined: Rs 72,446 crore (February, July, August)
— The year's largest outflow month, March: Rs 1,17,775 crore. November alone has now more than reversed it
— Jan–Oct outflow recovered so far: about 41%
What the table also shows
— Seven of the ten months before November were net sales
— Net equity for 2026 to date: minus Rs 1,72,880 crore
The tension: a single record month has not changed the sign of the year; it would take another November of similar size to do that.
This post does not forecast December or the next fortnight. The table records what has happened, not what comes next.

1
597
Max Healthcare added 758 beds in twelve months. Network occupancy in the September quarter was 77%, the same as a year earlier.
Q2 FY27 earnings call (held 3 November, transcript filed 9 November) and the results release.
Absorption
— 202 brownfield beds added in the quarter alone
— Occupied bed days: up 13% on the year and 7% on the quarter
— EBITDA per bed: Rs 77 lakh a year, up 4%
Ramp-up speed
— Max Smart's 260 new beds reached EBITDA breakeven within three months
— House guidance: a brownfield breaks even within the first quarter, a greenfield typically in one year
— The Saket complex carried a Q2 EBITDA drag from that ramp-up; outside Saket, EBITDA grew 25%
The next wave
— Sector-56 Gurgaon, 500 beds: phased start by the end of FY27, opening with 150–200 beds
— Start-up EBITDA loss put at Rs 40–50 crore, against Rs 30 crore when 300 beds opened at Dwarka
— Rs 415 crore approved for 209 more brownfield beds at Noida, Vaishali and BLK-Max
The tension: the drag that has been absorbed is a brownfield one. Gurgaon is greenfield, and the effect of the trade-margin cap on non-scheduled drugs is, in management's words, still being worked out.
For a hospital network, which tells you more over the next two years: how fast new beds fill, or what each
occupied bed earns?

1
623
The market sees GHCL Textiles as a traditional cotton yarn manufacturer riding a cyclical recovery.
But beneath the earnings surge, a bigger transformation is unfolding—premium yarn, expanding fabric operations and green energy advantages.
👀 Is this a lasting business turnaround, or are favourable cotton prices hiding the real risk?
Read more: zurl.co/h3Lkp
#GHCLTextiles #TextileStocks #IndianStocks #EarningsAnalysis #Manufacturing #GrowthInvesting #MarketSmithIndia

1
569