

“It ain't what you don't know that gets you into trouble. It's what you know for sure that just ain't so”
Atlantis
Joined February 2021
- Tweets3.8K
- Following439
- Followers579
- Likes588
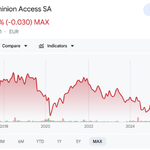




New company analysis: Global Dominion Access ($DOM.MC), a €400 million Spanish engineering solutions firm
Link (paywalled) in first comment and in bio (1/n)

(5/n) Plan broadly successful in simplifying complexity and improving profitability, but only partially delivering on the growth component
Market not giving give management credit for the ongoing transformation and punishing the stock at every miss on the growth promises

1
1
78
New company analysis: Ferrari Group ($FERGR.AS), a specialist provider of secure logistics, customs and value-added services tailored for the hard luxury sector (not the supercars manufacturer …)
Link in first comment and in bio (1/n)

1
1
117
(4/n) The listing process (no new cash raised, family still maintains control, low free-float, little to no support from the sell-side) led to a poor post-IPO performance

1
49
New company analysis: Verisure ($VSURE.ST), the European leading provider of professionally monitored alarm systems and smart-home security solutions for residential properties and SMEs
Link in first comment (and in bio), with a detailed analysis of business model and KPIs (1/n)

1
292
(3/n) IPO’d in Oct 2025 (Europe's largest in 3 years), financial performance has been good: double-digit ARR growth, first interim dividend, reduced net leverage
But the stock’s performance has been materially weaker: -35% from the IPO price and -46% from the first day closing

1
103
New company analysis: DO &CO ($DOC.VI), a €2.3 billion Austrian company that provides premium catering services for airlines and international events
Link in first comment and in bio (1/n)

1
1
159
(2/n) mrmarketmiscalculates.substa…
Three segments (% of rev):
- Airline (80%): in-flight meals to more than 60 airlines
- Int'l Events (13%): bespoke hospitality for major sporting events (Formula 1, FIFA World Cup)
- Restaurants, Lounges & Hotels (8%): premium hospitality venues

1
100

New company analysis: Olvi ($OLVAS.HE), a €700 million Finnish beverage company with a portfolio of both alcoholic and non-alcoholic beverages such as beer, cider, soft drinks, mineral water and energy drinks.
Link in first comment and in bio (1/n)

1
2
198
(5/n) Biggest problem: Belarus is a "trapped goldmine", highly profitable but completely isolated from the rest of the group: dividends are legally capped (€33m cash is trapped there) and the stake cannot be sold without government permission
1
56