

Stocks, markets, politics, energy. Play to win. Go for gold.
Joined March 2016
- Tweets17.3K
- Following479
- Followers3.6K
- Likes48.2K

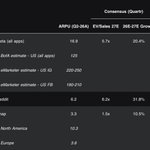





(1/2) Hung out with cousin’s boy today, 18yo, we had a german Döner at this new place. He was on his @snap and sent to his buddies. I asked him about the storage plan, he said he has it since summer, $4/month small cost b/c he has everything there since he was little. He also said everybody he knows got it too. He was not annoyed, he has other subs too Apple cloud etc
(2/2)
25m users @ $4 / month = $1.2bn per year. Not a huge number perhaps in 2026 but for $snap with $10bn mcap and other ad revenue likely on the rise, its a big number. This goes almost straight to the bottom line. Q3 will be exciting!
If $snap is really turning this around, the upside potential is nuts. Can they just reach half-ish of Meta’s ARPU and sales multiple, it’s a 5-10x. And monetization can go fast and also value re-rating. More thoughts 👇

2. I don’t see any other way @evanspiegel could have developed Snap TBH. Snap was a late mover versus Twitter and Facebook/Instagram. He positioned Snap on communication with a social angle - targeting the younger generations, and had to build on that. User growth and XP had to be top priority. If he started monetizing too early, it could have been a short-lived story.
$vcre $vico.st #vicore
Finally some action here, not unexpected with futility analysis out in a few months, they are sitting on a drug that can potentially make this a biotech heavyweight in Sweden. IPF is a USD 10bn market, with a PoS of say 25-50% (odds are good IMO / DYOD), and this stock is priced like an option with a very very low premium.


$canatu is a potential monster in the making this summer. CNT-pellicles will be key and is why $ASML and the industry is taking a hard look at it. A validation by ASML should give it a couple of baggers on the day.
I will be adding if it comes down more.
trendforce.com/news/2026/06/…


$aixa
Aixa CEO said, ”need” 80-100 new MOCVD systems for lasers per year. With installation and after sales, that’s €500m ish or more. That excludes refurbishment/upgrade of older MOCVD reactors.
Then we have the new 800V/1200V AI power racks roll out, starting in 2027 ramping to 2030, which will require thousands of reactors (SiC CVDs and GaN MOCVDs), that’s probably 100 new systems in 2027, 150 in 2028 and 200 in in 2029 (according to Gemini)… and also significant number of legacy systems that will need upgrading that are excluded.
Aixtron dominates this market, and this won’t happen without Aixtron’s tools.
Likely revenue, IMO, €1.2-1.4bn in 2027, scaling up until the end of the decade. Consensus estimates (Quartr) has Aixtron at €740m in 2027. Just saying, why waste time on $sive at that valuation when you have a steal in $aixa @aleabitoreddit
In Nacho We Trust retweeted

Rationale behind increased therapeutic index for $RVMD RM-055:
- Most RAS mutants are very resistant to GAP-mediated hydrolysis, and thus showing way slower rate of hydrolysis to WT RAS
- By restoring hydrolysis, you are making mutant RAS to function like WT RAS again
- And given WT RAS is already quite efficient in hydrolysis, RM-055 should have less impact on its downstream activities
This is a really genius way to bring us one step closer to a pan-mutant selective RAS inhibitor! (and to improve potency/selectivity on mutant-specific RASi)
Cheers to @RevMedicines!
Figure from Hunter 2015


$sive vs $aixa
Did great in $sive and may come back at some point, but there is more substance in $aixa and I really don’t understand the logic the Reddit crew has that - they don’t like equipment makers… They have 80-90% market dominance and true pricing power, clean balance sheet and an M&A warchest, ahead of a cycle that is historical. Great exposure to photonics and 800V power racks. They will jack up guidance every quarter.


In Nacho We Trust retweeted

GAN is the way forward … lets discuss some alpha in the Photonics Supercycle: Signals in AIXA earnings call
$AIXA had earnings call and popped up another +11%, bringing YTD upside to +130% and 1 yr upside to +288%.
You guys know that am already invested in Aixtron ($AIXA) and have written about this German champion in the past, framing it as a quintessential "hidden monopoly" within the semiconductor equipment space. I also think that this is early innings of a massive Photonics Supercycle. As AI clusters migrate from 800G to 1.6T and eventually 3.2T optical modules, the bottleneck for AI scaling has shifted from the H100/B200 compute engine to the interconnect fabric itself. You cannot run a frontier model if the data can’t move between the GPU and the memory stack fast enough. Aixtron sits at the very mouth of this funnel.
I would not regurgitate the numbers here, rather analyse and unpack the things I consider important with impact on overall AI and semisector.
The Great Divergence: GaN vs. SiC
One of the most tactical takeaways from the call was the stark contrast between Gallium Nitride (GaN) and Silicon Carbide (SiC).
🐊 SiC Overcapacity: Management was candid about Silicon Carbide being in a state of "substantial market overcapacity," with SiC expected to be only 10% of their revenue this year. This is a warning shot for pure-play SiC substrate and device makers who are still digesting inventory.
🐊 The GaN Opportunity: Conversely, GaN is entering a golden era. Management expects AI data centers to become the largest single application for GaN power semiconductors. Because GaN is significantly more efficient than traditional silicon at high frequencies, it is becoming the standard for the power supply units (PSUs) that feed power-hungry AI servers.
For those looking to play the GaN trend beyond the equipment layer, keep an eye on these players:
• Navitas Semiconductor ($NVTS) – A US-based pure-play leader in GaN power ICs.
• Infineon Technologies ($IFX.DE / $IFNNY) – A European giant with a massive, growing footprint in GaN following their acquisition of GaN Systems.
• STMicroelectronics ($STM) – Another European heavyweight with strong GaN-on-Silicon capabilities.
• BluGlass ($BLG.AX) – An Australian-listed speculative play involved in specialized
🐊 Datacom Doubling: Management is forecasting that demand for datacom lasers will more than double YoY in 2026. This is a massive green flag for the laser makers themselves, such as Lumentum ($LITE) and Coherent ($COHR), who are racing to expand Indium Phosphide (InP) capacity. (am invested in both)
🐊The "Tool of Record" for AI Interconnects
The standout signal from the call was the performance of the G10-AsP system. Management confirmed it has become the "tool of record" for the next generation of photonic components
🐊 Order Intake Explosion: Order intake hit €171 million, a ~30% YoY increase that blew past analyst expectations. Crucially, 65% of these orders came from the optoelectronics segment
🐊Implications for the Memory (HBM) Ecosystem
While we often view memory through the lens of SK Hynix or Micron $MU, the Aixtron update provides a critical "read-through" for how these chips will be connected in the future.
🐊 Structural Bottlenecks: For those holding SK Hynix, $DRAM or Micron ($MU), the shift toward optical interconnects is the solution to the "power wall" that threatens to limit HBM performance. Aixtron’s order backlog suggests the equipment for this transition is being installed now.
🐊 Near-Stack Integration: The acceleration of Co-Packaged Optics (CPO) means that optical engines will eventually sit directly on the package alongside High-Bandwidth Memory (HBM) stacks.
Look the "Photonics Supercycle" isn't a theory anymore it’s appearing in the capex cycles of the world's largest chipmakers.
And remember, none of this is financial advice. The crocodile can make errors. So do your own research.

$rvmd rmc-6236 likely on the shelf in 2-3 months (?), every oncologist with pdac patient will move over to 2L asap.