

Full time equity trader/investor mainly focused on resource companies. Fed up with executive greed in the micro-cap space - will challenge management directly.
London
Joined August 2012
- Tweets5.5K
- Following266
- Followers1.6K
- Likes177




Pinned Tweet
#SKA (2.9p) looks an outstanding value proposition :-
🔶Recent £900k raise at a premium (4p)
🔶Tight float
🔶 In ground resource value $4 billion
🔶Strategic investor takes 12% stake
🔶High grade Zinc/Lead project (Kabwe)
🔶Recent drilling - bonanza grades
🔶M/cap just £4.4m ?

Oilplayer2009 retweeted

#Hama Hamak Strategy's Akoko gold project 👇
⛏️ Total gold resource: 210,430oz
🟡 Average grade: 0.76g/t
With gold around $4,000/oz, that represents approximately $842m of contained gold value across the full resource.
A company valued at around £2.5m, with approximately $842m worth of gold in the ground at Akoko👀
The R:R here is undeniable
Keep an eye on #HAMA (.50p) just £2.5m m/cap but a swathe of material news is upcoming by end Q4 concerning their Akoko #GOLD project in Ghana - a low cost near surface licence
The in ground value of Akoko is circa $1 billion !
Shares traded at 7p last year
@hamakstrategy
#SKA (3.65p) more world class drill results announced - CEO implies 50%+ resource upgrade is nailed on - would be worth - in ground value circa $6 BILLION !!
Current @Shukaminerals_ m/cap just £4m ??
Another #EEE #GGP in the making ???
Oilplayer2009 retweeted

#PREM The 6-Month Timeline: Mapping PREM's Case Re-Rating Route.
1/ If the 15-day operational trial at Zulu proves successful, we aren’t just looking at a minor short term pop. We are looking at a structured, multi-phase re-rating path over the next two quarters. Measured from today's closing price baseline of 0.00435p, here is the exact math breakdown.
2/ Month 1 Target: 0.0080p – 0.0150p (+84% to +245% Gain) The initial de-risking catalyst. A successful 15-day campaign strips away the permanent "broken plant" discount. Short-term momentum chasers pile in on the back of confirmed plant stability and high-grade specifications.
3/ Month 2 Target: 0.0250p – 0.0400p (+475% to +820% Gain) The non-dilutive bridge. Proving out the grade allows management to officially unlock the commercial cash-flow framework under active offtake prepayment rules. The market finally realises the board doesn't need to print shares to survive.
4/ Month 3 Target: 0.0400p – 0.0600p (+820% to +1,279% Gain) Steady-state expansion. The plant builds multi-week consistency, climbing closer toward management's target of delivering 2,000 tonnes per month of spodumene concentrate to global markets.
5/ Month 4 Target: 0.0600p – 0.0800p (+1,279% to +1,739% Gain) The debt crunch. With active production revenues flowing, the looming $35M Canmax liability begins to get structurally addressed and reduced. Risk modelers start aggressively moving their price targets higher.
6/ Month 5 Target: 0.0800p – 0.1000p (+1,739% to +2,199% Gain) The Glencore Factor & RHA. Operational proof at Zulu triggers the progression of the active Letter of Interest (LOI) with Glencore into a binding offtake structure. Simultaneously, talks with ZMDC to restart care-and-maintenance operations at RHA Tungsten add double corporate momentum #GLEN
7/ Month 6 Target: 0.1000p (+2,199% Gain — Full Baseline Asset Value) The final destination. With Zulu delivering steady commercial cash flows and RHA's massive accumulated loan account leverage coming alive, the market finally values the company at its full £77M / $100M framework representing a massive 22x return from today's heavily discounted close.
@Premafrimin @Official_MMCZ @Glencore @MinistryMines @ZMDC @LSEplc
#PREM #Lithium #Tungsten #SmallCap #AIM #MiningStocks
🤖 Made with AI

No apology for pointing out #CNSL (1.75p) as an investment proposition ahead of their launch of new food testing products - will have 1st mover advantage into a market worth $1.5 billion
Valued at just £3.9m - cash £2.6m - no debt - current sales £7m
Fantastic entry point

Oilplayer2009 retweeted
#PREM Premier African Minerals.
1/ Let’s address the elephant in the room: Yes, $PREM heavily diluted on 5 October, printing 27.5B new shares to raise £1.2M. It hurt existing holders, but for new capital looking at the current valuation, that raise might just be the ultimate de-risking flush.
2/ Where did that cash go? It is specifically earmarked for the immediate remobilisation and processing restart at the Zulu lithium project in Zimbabwe. Instead of waiting to build a massive stockpile, #PREM is working through 13,000 tonnes of ore already sitting on the ROM pad.
3/ The 15-day operational campaign starting this October is the defining catalyst. It is a direct test of plant stability, throughput, and concentrate quality. If the Xinhai flotation plant proves it can hit steady state, the valuation gap closes fast.
4/ Remember the structural backdrop: PREM has an active offtake prepayment framework. The £1.2M equity raise provides the bridge to get the plant operational, allowing the company to tap into non-dilutive working capital from future product deliveries once specifications are met.
5/ Small-cap junior miners are binary bets. Most are stuck in years of drilling and permitting. $PREM has the plant built, the ore ready, and the cash to turn the keys this month. The dilution is priced in; steady production is not.
6/ The thesis here is strictly operational momentum. Watch the RNS feed for successful plant stability and firm timetables for first shipments. The risk is high-wire, but the post-dilution entry provides asymmetric upside if Zulu delivers.
7/ The Ultimate Prize: Once steady-state production is locked in, management's ultimate target is clear and highly lucrative: ramping the Zulu plant up to consistently deliver 2,000 tonnes per month of spodumene concentrate to the global market.
8/ The Trade Mechanics: The recent raise set a hard price floor at 0.00436p. Success clears the path for a re-rating toward the project's 0.10p theoretical baseline asset value(£77M / $100M framework). Recovering to that baseline represents a massive 2,172% rise (22 x gain) from today's heavily discounted entry, stripping away the "broken plant" discount.
9/ The Glencore Wildcard: A successful 15-day trial is the exact trigger needed to progress PREM’s active Letter of Interest (LOI) with commodities titan Glencore into a binding offtake agreement. A tier-1 major stepping in would completely de-risk the Canmax debt framework and spark a massive structural re-rating.
The execution of this restart lies squarely on the alignment between management, tier-1 off-takers, and national export frameworks.
How fast can the regulatory and off-take channels clear once production specification is locked?
@MinistryMines @edmnangagwa @Mining_Zimbabwe @COMZ1939 @InfoMinZW
#PREM #Lithium #SmallCap #AIM #MiningStocks @Premafrimin
🤖 Made with AI

#CNSL (1.6p) moving - do not miss the boat - materially undervalued & under radar - hideously low m/cap of just £3.8m
Growth is forecast into 2027 - reason - new regulations will benefit company - 1st mover advantage
Cash £2.6m - no debt - shares were 4.25p last year

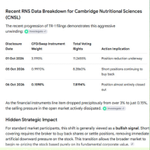
#CNSL (1.55p) do not miss the swing back to the 4p region - the long standing short has closed out over recent days !

#CNSL (1.55p) recent RNS's suggest the Spreadex short position is closing out
Shares are down from 4.25p - m/cap just £3.7m - cash £2.7m - sales £7m pa - no debt
Sales growth expected in 2027 due to regulatory changes
Expecting a strong SP rebound - the stock is illiquid

Oilplayer2009 retweeted

As part of our New 3G Fundraiser we would like to welcome you to the club on Saturday 10th October for free entry (and parking) to the Men’s First Team vs Gorleston ⚽ alongside music 🎶, ice creams 🍦, and a general feeling of fun, including Happy Hour 12-1pm (£1 off every hot food or alcoholic drink purchased) and a chance to see and hear more about the impact your donation will have and why we need this help.
Come on down and show your support. Please share this post far and wide and let’s try get a fantastic attendance!
#UpTheSuds 💛💙


Oilplayer2009 retweeted

#IGG
What a shambles.
Used to be the best in the business. They have ruined a great product and now they're losing big customers and their best staff...
Share price rightly down over 50% from June highs.
I was always loyal and thought they'd figure their shit out, but even I've now moved my trading elsewhere.
That's what happens when you have clueless idiots making decisions at the top.

#CNSL (1.55p) just £3.75m m/cap with circa £2.7m in cash !
First mover advantage under the new regulatory framework means their new food testing products will be 1st choice for buyers worldwide
Company is under radar and not followed - current sales of £7m pa could multiply !

One to watch is #CNSL (1.55p) - only £3.75m m/cap (cash £2.7m - no debt)
1st mover advantage new food testing standards mean sales could boom into 2027 - under radar and materially undervalued - looks a great opportunity - 4p to 8p is possible !
Shares traded at 4.25p

Oilplayer2009 retweeted

🚨 ShareTalk - Shuka Minerals Confirms High-Grade Zinc Intersections at Kabwe Pit 2 🚨
Read More:
share-talk.com/shuka-mineral…

Thanks for nothing @IGClientHelp @IGcom @IGTradingFloor - been 'migrated' over to their 'improved' platform - no say in the matter - totally useless - now expected to trade blind
No fixed prices (buy or sell) - only 'limit orders' placed directly with 'market makers'
Goodbye

Oilplayer2009 retweeted
🚨Kabwe Drilling (“KBDD01-05”) 🚨
ALS Laboratories Confirm Scale and High-Grade Drilling Results at Pit 2 of the Kabwe Project.
Read More:
shukaminerals.com/post/kabwe…
