
Semi analyst aiming for high yields and low defects
India
Joined June 2010
- Tweets3.5K
- Following2K
- Followers626
- Likes5.9K




$INTC Q3 2026 earning key takeaways:
1. Overall: Intel has more demand than it can supply. AI is driving strong server CPU sales, but the memory shortage it has caused is hurting PCs. Intel is still fixing its supply chain, so it can’t fully take advantage of the demand.
2. DCAI: Customers want more server CPUs than Intel can make. Intel 3 output and substrates cap 1H27 shipments, so growth depends on Ireland capacity arriving on time in 2H. Until AMD parity in 2028, capacity decides share.
3. Foundry: Intel 3 and 18A are getting cheaper and have better yields. Packaging will likely bring the first outside revenue, but substrates hold it back. Wafer foundry still needs a named customer for 18A-P or 14A.
4. Client Computing: Weaker consumer demand, higher DRAM/NAND prices and cautious OEM inventory drove the decline. Better CPU pricing and premium mix no longer offset lower volumes; commercial demand holds, but affordability is squeezing consumers. The downturn is effectively funding the server ramp.
Client (CCPG)Q3 revenue $8.1B −5% YoY. Operating profit $2.3B (28% GM). AI PC revenue grew +35% YoY, and edge/physical AI held up well.
1. Memory prices and availability triggered a sharp OEM inventory correction.
2. Q4 CCPG guided -20% QoQ, seasonal decline in Q1 27. The inventory correction runs through Q4–Q1, possibly Q2.
3. Intel expects the PC TAM to fall ~12% in 2026 and ~10% in 2027
PC correction and the Israel fab (Fab 28 adding about $300M) explain most of the weak Q4 guide. PC side is by far the larger of the two. Data center demand is still strong but limited by supply
1. Oregon 18A capacity planned for Panther Lake is being converted to Intel 3 for Xeon, with output in 2H27.
2. Client wafer starts have been cut to match demand. This is the main driver of the Q4 GM decline.
$MSFT Q1 FY27 summary:
Cloud: Azure +48% to $33.2B. Microsoft Cloud +30% to $63.9B at ~50% OM.
Backlog: RPO $677B, flat QoQ (+73% YoY), with ~30% converting within 12 months. Bookings fell 12% against the October 2025 comp, when OpenAI’s ~$250B commitment landed.
Capex: $45.2B including leases fell below the >$50B guide because some third-party GPU capacity slipped into H2. CY26 is now ~$170B, after moving $190B to $175B to $170B. About 75% of capex now goes to short-lived assets.
Silicon: The fleet is NVIDIA plus AMD plus Maia. GB300 is now the majority of deployments. Maia 200 still has no GA and no external lab customer.
FCF: $18.6B (–27%) as cash capex rose 103%. Microsoft says it stays FCF-positive in FY27. It will tap additional sources of funding when attractive.
Demand evidence: Copilot daily users +~50% QoQ and 5x YoY. Moving from seats counted to token consumed.
$GOOG Q3 26 earning summary:
Cloud: + 103% to $30.7B at a 36.2% margin, and the backlog is $561B (~$310B converts within 24 months). TPU sales were not sized, and 3rd party capacity only came online at the end of Q3, so its margin hit lands in Q4.
TPU economics: Contracts show up in backlog first, then inventory, then cash. Revenue ramp is 2027.
FCF and CAPEX: –$9.1B on $51.4B of capex. The 2026 capex guide is unchanged at $195–205B, and 2027 rises significantly.
ROI: it is stated as above the cost of capital, with no figure and no capacity-priority ranking. A 6-year life for hardware risks higher depreciation later.
Demand evidence: API tokens are up 40% quarter on quarter to about 32B per minute, Gemini 4 Argon ramped 3.5x faster than Gemini 3, and the Gemini app has 1B users.
Merchant TPU sales widen the market. Inventory precedes cash, and Broadcom and CoWoS supply, not demand, set the 2026 ceiling. $GOOG

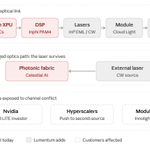
$MRVL $LITE deal end to end integration from silicon-to-light
1. Marvell owns the electrical end of the link. (Custom XPU and the DSP.) @Lumentum would provide optical end(laser, module and switch). Will make @MarvellTech the only vendor selling the full pluggable link.
2. In CPO, DSP and the pluggable module can disappear, but the external CW laser still needed. Pairing Celestial AI’s photonic fabric with Lumentum lasers keeps Marvell in the link whether the industry stays pluggable or moves to CPO.


Marvell is in advanced talks to buy data center optics maker Lumentum, according to sources, a potential megadeal amid the race to scale up in the artificial intelligence sector bloomberg.com/news/articles/…

Agentic AI is driving the DC CPU demand.
@Meta Muse: AMD EPYC 9D25, 126-core Turin, 2 vCPUs. A SKU with no public spec sheet, likely Meta-custom.
@OpenAI dots: AMD EPYC 9V74, 80-core Genoa, Azure-only part, 9 vCPUs.
@grok Bot: Intel Emerald Rapids (fam 6, model 207), 4 vCPUs.
@claudeai Duet: also model 207. It called itself Sapphire Rapids; Emerald Rapids?
This is the tool sandbox, not the inference hardware, and one VM ≠ a fleet (Meta has also signed up Graviton5, Arm AGI CPU and Grace for agents).
$AMD $INTC

$AMD $META
1: EPYC CPUs power Muse and Helios rackscale systems now in testing at Meta.
2: Instinct GPUs are currently used for training, ranking and recommendation engines at Meta.
3:AMD to invests $1B in META and expand to gigawatt scale.
share.google/fgWoHPs6bUoJLab…

$TSM 3Q26 beat expectations. Revenue $46.7B +16%QoQ 41% YoY. GM 66.4% dilution from the initial ramp of N2 . Growth driven by price and mix.
TSMC is evaluating a Texas fab. If it partners with Terafab, TSMC would run the fab. nitter.cf/Parv_S/status/21077528…
