

Mortgage Data Science. Authors of HMDAVision, MBS Pivot, and CensusVision.
- Tweets407
- Following120
- Followers66
- Likes178



ALT U.S. state map: share of 2026 agency purchase loans with LTV above 95%, YTD through May. Polygon Research MBS Pivot. Eight states at 50% or higher: Mississippi 61, Louisiana 57, Alaska 54, Alabama 54, Oklahoma 53, West Virginia 53, Texas 52, Arkansas 50. Lowest: New York 22, New Jersey 21, Massachusetts 20. Fannie Mae, Freddie Mac, and Ginnie Mae loan data.

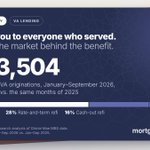
ALT A graphic shows VA lending statistics for Veterans Day. The main text states "Thank you to everyone who served. Here is the market behind the benefit." It highlights 433,504 VA originations from January to September 2026, a 12% increase compared to the same months in 2025. A horizontal bar graph indicates 56% purchase, 28% rate-and-term refinance, and 16% cash-out refinance. The data source is Polygon Research, and the graphic is branded with mortgagedata.ai.

ALT The image is an advertisement for mortgagedata.ai with the tagline "Your mortgage decisions are connected. Your market intelligence should be too." It mentions steps: Plan, Do, Check, and Act related to mortgages. The logo "Polygon Research" is at the bottom.

ALT Title How big was subprime in 2007?

ALT One in seven subrpime loans.

ALT Risk layering was common practice before the housing crisis but went undetected.

ALT Loan features are now available in HMDAVision for deep exploration and analysis to understand risky loan segments.


ALT A focused duo sits at a table reviewing documents, with the text: "See the whole market. Know where to act." and a list of actions: "Find, Compare, Understand, Connect, Watch." The image promotes Polygon Research's total mortgage market intelligence.

ALT Chart - increase in average purchase loan amounts from 2018 to 2026, $233,409 in 2018 and $360,320 in 2026 YTD. The line graph displays consistent growth with notable points in 2021 at $322,071. Source: Polygon Research - Polygon Pulse (MBS Pivot).

ALT Common Ground Issue - who held the mortgage on your house in 1890? by Polygon Research

ALT Individual investors supplied 70% of US mortgage dollars. Total mortgage debt outstanding was $6 Billion.

ALT The National Bank Act of 1864 barred national banks. Page 4 in Common Ground Issue No4 by Polygon Research.

ALT Lending has always been local. Polygon Research measures it - every originator, every market, down to the census tract, across all 3200 counties.

ALT The image is an infographic titled "How big is the multigenerational market?" It presents three sets of data: "Strict" with 5.1M households for 3 or more generations, The footer states data sources: Polygon Research and CensusVision (ACS 1-Year PUMS, 2024)


ALT A presentation slide with the title "How did 70,000 families buy a house from a catalog?" At the top, it reads "Common Ground: The structures behind housing, finance & community." The bottom mentions "Polygon Research" and "Housing & Mortgage Data."

ALT Large text stating, "It came by rail." Below, "A letter told you the house would reach the depot in three days. You went down and unloaded the boxcar yourself." At the bottom, "Polygon Research", along with "Housing & Mortgage Data"

ALT Title "The Loan From 1911" from Polygon Research. It states that Sears offered loans that did not consider race, gender, or ethnicity. A loan required a quarter down, five years, six percent interest. A graphic of a simple house outline is at the bottom.

ALT "Why It Still Matters" from Polygon Research. The costs of factory-built housing compared to site-built housing, highlighting lender reluctance to finance. Subheading states, "Building it cheap was never the hard part." Website: polygonresearch.com.


ALT The image is a line graph from Polygon Research showing monthly loan counts from January to December 2026, with actual data in yellow and projected data in dashed gray. The actual trend starts at approximately 100k and rises to just above 125k by Dec.

ALT Title slide from Polygon Research, discussing the topic 'How old is the homeownership rate?' with a prompt to swipe and continue through the presentation.

ALT Image with text on a grid background. Prominently displays "Since 1890" in bold - the year the census first asked about home ownership and outstanding debt. Bottom text includes "Polygon Research - Housing & Mortgage Data" and indicates page "02 / 05.

ALT Before 1890, homeownership rates weren't recorded. The census counted people, not tenure, leading to a lack of data on homeownership or mortgages. The image includes "Polygon Research" and "Housing & Mortgage Data". There is a dotted grid.

ALT Text discussing the census with a focus on housing data. A machine was used to count responses, referring to Herman Hollerith's punched cards. The company founded later became IBM. The design includes a sample punched card from 1890. By Polygon Research.


ALT Polygon Research How to Analyze a Lender's Non-QM Business." The layout consists of six sections: 1) Scale, 2) Specialization, 3) Footprint, 4) Production Mix, 5) Purchaser Patterns, and a box promoting free state reports with a website URL.
