

Sharing personal research & thoughts || 🇳🇴 || Trying to live like Fat Tony || Never Financial Advice
Joined January 2022
- Tweets1.6K
- Following207
- Followers694
- Likes2.2K

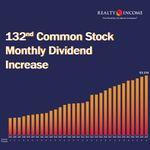





A small dividend increase just announced by $O. I'll take it. Several of these small increases every year, plus a big one every year or two - the compounding adds up.

Invitation Homes $INVH, the largest single-family residential REIT performed well in Q2. They have an impressive 5Y Div CAGR of 15.48%, beating most other REITs. On my radar.

Essex Property Trust $ESS Q2 looking stable and solid. Their focus on high-demand West Coast multifamily housing markets makes them appeal as a safe bet in the beaten down apartment sector.

Not alot of difference in 5Y total return in the multifamily REIT segment, with $AVB. Macro environment has compressed valuations in a 10Y perspective. I expect a significant increase if/when rates drop.

Stable projected FFO/sh growth from AvalonBay $AVB. Multifamily REITs valuations are very low looking back 10Y. Could be a great opportunity - or just the "new normal".


Alexandria $ARE overall portfolio occupancy has declined to 90.8%, a drop from 94.6% a year ago, while tenants are delaying leasing decisions. FFO/sh has also declined. Share price decline last year reflects this (-34.6%). Div payout ratio is still safe, though (57%).

American Homes 4 Rent $AMH, the single-family housing REIT, is showing impressive growth in Q2/25 - they also grew Core FFO per share 6.6% in 2024. Stock hasn't really moved since mid-2022. On my radar.

International expansion in Europe is seen as a catalyst for future resilience for Realty Income $O. Access to new markets give diversification benefits. If executed well, this strategy could reduce their dependence on U.S. economic cycles.

Federal Realty $FRT has the longest record of increasing dividends in the REIT industry. 7% CAGR since 1967, a dividend king. They've weathered many different economic environments. Not the fastest grower, but no doubt a safe spot to park cash.


Prologis $PLD Core FFO growth for Q2 2025 at 9% YoY, very impressive. Valuation at 18.22 P/FFO (TTM) isn't too bad either. Tenants seem cautious due to potential tariff effects. Might be a good buying opportunity - it's definitely on my radar.

The Lamar Advertising REIT $LAMR, recently picked up by Warren Buffett/Berkshire Hathaway, has an impressive track record. 8.5% div CAGR is solid, and following the S&P500 for 10Y is no small feat either.

When adjusting for the India divestment last year, American Tower $AMT AFFO/sh YoY grew 2.4% as of Q2 2025. Growth has slowed significantly, and I am staying away.

VICI Properties $VICI showing that Vegas is by no means dead. Money talks.

W.P. Carey $WPC reported strong Q2 2025 results, raising full-year AFFO guidance to $4.87–$4.95 per share, implying 4.5% year-over-year growth at the midpoint. Their shift to more industrial might pay off even more ahead, if valuations close in on peers.

Realty Income $O Q2/25 staying the course. No surprises up or down - the AFFO/sh guidance up was no big surprise. Their original guidance was very defensive. Looking good for rate cuts ahead!

Realty Income $O Q2 earnings tomorrow. I expect European expansion to continue. Interesting to see if they can revise 2025 AFFO/sh guidance up a notch.
