

@Signal_Sigma
Account based inRomania!
About this account
- Account based in
- Romania
- Connected via
- United States App Store
X says this location may be affected by a proxy or VPN.
Account-level information from X, not a live location or the device used for a specific post.
Invest Smarter with Signal Sigma: Professional-grade strategies, automated insights, and risk tools. Try free at https://nitter.cf/t.co/Ng2smTsc6F No card required.
Bucharest, Romania
Joined January 2013
- Tweets3.5K
- Following272
- Followers6.1K
- Likes30K


Pinned Tweet
Agent Sigma is online!
Merging the power of AI with our expansive datasets and tools, this new functionality will supercharge your workflow!
Agent Sigma can do everything you can do in the app:
Set up a Stock Screener or Market Study ☑️
Launch a Backtest ☑️
Create a Ranking Model ☑️
Add Tickers to a Watchlist and configure it ☑️
Group Assets in a Portfolio ☑️
...or really just about anything you can think of!
The use cases are so broad that we really need your help to improve here -- just give us a thumbs up or thumbs down after an answer and let us know if the Agent is doing a good job for you! Enjoy!
Just a reminder institutions have been loading up on Tech stocks since early August across all market cap cohorts.
It’s what’s been propping up the headline indices, and the flows stand in stark contrast to general investor sentiment (and dollar volume, which has since subsided).

The correlation between oil and long bonds ($USO - $TLT) has hit an all-time inverted extreme. Up until now, it would have been reasonable to expect higher oil = higher yields.
But that trade may have just run out of steam, as this series is highly mean reverting.
A breakdown in correlation between oil and bonds can play out in one of two ways:
- Oil moves lower but yields remain stubbornly high; this is the bullish setup, as it argues yields are high because growth is strong (arguable, but that’s a different discussion);
- Oil rises, but yields move lower; this is the bearish scenario, as it suggests growth is contracting due to higher oil prices;
The way this plays out is the key to the path forward for equities.

The Options Structure dataset is live in Signal Sigma API!
Besides the very popular call / put walls and our aggregated GEX figures, this dataset will give you a per expiration view for:
- All First and Higher Order Greeks (Delta, Gamma, Theta, Vega + Vanna, Charm etc,)
- Call / Put Open Interest, Premium, IV
- Expected move, Max Pain, Wing and ATM metrics
Just scratching the surface with this article, but it's a starter:
signal-sigma.com/public-rese…
The API Guide explains the usage for each metric and the calculation methodology: signal-sigma.com/s/Options_S…
Historical data is available to 2020 for now, but more is being rendered as we speak.
And we will eventually integrate these metrics in our app's frontend, for more intuitive (and AI-assisted) analysis.


For those of you interested in the upcoming options structure metrics we are about to publish.
The documentation / user guide is ready and can be found here: signal-sigma.com/s/Options_S…
More details soon, as we go live with this update.

For those of you interested in the upcoming options structure metrics we are about to publish.
The documentation / user guide is ready and can be found here: signal-sigma.com/s/Options_S…
More details soon, as we go live with this update.
First and Higher Order Greeks are coming to Signal Sigma very soon. Data will be de-aggregated, and viewable per expiration date for each ticker. 90+ new metrics.
This will be an API exclusive for now, but already working on the way we'll display it in-app.
Example: that spike in $SPY put / call ratio happens on October 30, the last expiration before the US midterms. This is where de-aggregation per expiry date becomes very useful.
For compatibility with our larger database, we will eventually aggregate these in the usual short / medium / long term horizons.


Judging by our sentiment reading, it's fair to say the majority of investors are not positioned for upside in the equity market.
Sentiment can turn even more bearish, as the lower graph demonstrates.
Investing during these regimes has led to around double the historical returns. Any upside catalyst will inevitably coincide with at least a partial reversal in yields. This will also trigger a reversal in the $RSP / $SPY ratio, as the broad market will be favored once more.
That's the bull case at least.

A reversal which came right on cue. The $RSP / $SPY ratio has favored mega-caps in September, as weak breadth took its toll on the equal weighted version of the index.
The good news is that the market hasn't cracked so far and sentiment is quite bearish for where we're trading at.
This leaves the median stock plenty of room to catch up, when the ratio inevitably turns up again.

Enterprise, our core asset allocation model, has been showing us for a while that the only viable long-only hedge to equities are no longer bonds, but commodities.
Today's rebalance keeps the same profile (45% commodities / 36% stocks).


Thanks Doc! Putting the final touches on this as we speak!

Tue Sep 29
I feel the need for speed.
Andrei ... you platform coding beast. (@Signal_Sigma, signal-sigma.com/main-nxt)
Looks really good.
And in the context of what I'm seeing in the financial research literature ... surrounding AI-enhanced trading ... your cause is just.
Take, for example, this quote from a paper on the reflexivity effect: "When institutional hedging flows and fast algorithmic reactive strategies coincide, they artificially amplify intraday momentum or suppress realized volatility, conditions often followed by sharp mean-reversion."
Oh yeah ... trade that with your eyes following OHLC and your hand on a mouse.
The need to go to where the ball will be ... as opposed to chasing the ball ... becomes even more urgent.
The Red Queen Hypothesis: "In modern options markets, you have to run faster and build smarter models just to stay in the exact same place, because the collective intelligence of the ecosystem keeps raising the efficiency bar."

At 5.26%, the 10-Year will have gained +20% in 3 Months and trigger our signal.
It's also where the 3M rate of change has flatlined since 2023 (+1 STD, lower panel).
Yes, we have seen higher changes in the past, but those were coming off extremely low rates to begin with (sub 1% as the starting point).
Over the next 3 Months, the median change in rates is expected to be +0.5%, so we're going to 5.28%... eventually.
Study link: live.signal-sigma.com/invita…

Remember, it’s not the absolute level of rates that matters to markets, it’s the rate of change in interest rates.
We’ve seen far larger yield moves than today on a rolling 3M basis (lower panel). Those regimes produced above-average $SPY returns at every horizon from 1M on.
That said, falling yields still tend to precede far better market outcomes.
Full study here: live.signal-sigma.com/invita…

First and Higher Order Greeks are coming to Signal Sigma very soon. Data will be de-aggregated, and viewable per expiration date for each ticker. 90+ new metrics.
This will be an API exclusive for now, but already working on the way we'll display it in-app.
Example: that spike in $SPY put / call ratio happens on October 30, the last expiration before the US midterms. This is where de-aggregation per expiry date becomes very useful.
For compatibility with our larger database, we will eventually aggregate these in the usual short / medium / long term horizons.
Looking only at market breadth, you'd be excused to think we're in the middle of a significant pullback.
During the past 2 years, breadth has only been worse in 2 instances: March - April 2025 and March 2026.
I've been trying to find a relevant analog where $SPY sits this close to ATH values AND breadth is this bad. There is none.

Remember, it’s not the absolute level of rates that matters to markets, it’s the rate of change in interest rates.
We’ve seen far larger yield moves than today on a rolling 3M basis (lower panel). Those regimes produced above-average $SPY returns at every horizon from 1M on.
That said, falling yields still tend to precede far better market outcomes.
Full study here: live.signal-sigma.com/invita…
Though far less spectacular on absolute returns, Enterprise proves why it belongs at the core of our systematic asset allocation stack.
Boring, but foundational.

As we prepare to wrap up Q3, Vision stands out as the strategy to watch, while Millennium Alpha and Momentum still lag.
Vision selected two standout stocks ahead of their earnings and news-driven breakouts: $MRNA and $TEAM.
The model had only 3 rebalancing events so far in 2026. Proof that you don't need a lot of trading in order to outperform.
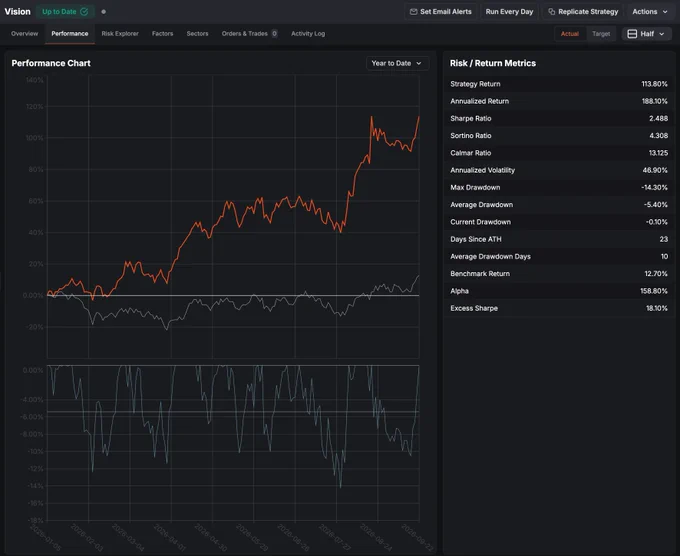
As we prepare to wrap up Q3, Vision stands out as the strategy to watch, while Millennium Alpha and Momentum still lag.
Vision selected two standout stocks ahead of their earnings and news-driven breakouts: $MRNA and $TEAM.
The model had only 3 rebalancing events so far in 2026. Proof that you don't need a lot of trading in order to outperform.
Building on yesterday's observation, using completely different tools: the current rally is not a buying opportunity (yet).
Our newly released Enterprise Regime study corroborates Agent Sigma's analysis. The regime is color coded "yellow", meaning:
- selective exposure
- long but hedged
- trimmed expectations for the near term
The structure since June has shifted through all regimes in a short amount of time, denoting an inability for the market to clearly decide on the direction of the next leg. This continues to persist.
For reference:
Green = Risk-ON
Yellow = Caution
Red = Risk-OFF
live.signal-sigma.com/invita…

Despite $SPY trading near record highs, market breadth remains weak and well below the levels seen at the previous peak on August 13.
Quite a staggering difference, actually. A recovery is needed here if we are to have sustainable higher highs.

Agent Sigma's take on the rally is lukewarm:
Tactical caution on upside momentum. SPY's +1.55% rally yesterday looks like an institutional liquidity event rather than the start of a sustained breakout.
Couldn't have said it better myself.

