

Freight trader. Views are my own and not investment advice.
Geneva
Joined October 2025
- Tweets1.2K
- Following10
- Followers2.1K
- Likes459

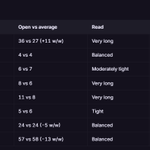


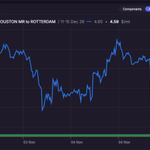



TC14 spot has come off 30 points to WS 397 since Wednesday and the arb board is already responding. Houston to Rotterdam diesel has improved $15.25/mt to -$20.75/mt for November, with January now just -$0.75/mt from opening. Three November arbs are open against one on Wednesday. Supply is still long at 24 ships in the seven day ahead window against a 90 day average of 18 and the model forecasts WS 366 against WS 397 spot for the 18 to 27 November window, so the correction is not finished. Watch December Houston to Rotterdam diesel at -$10.75/mt as it approaches neutral. That's the TC14 buy signal.

Houston → Rotterdam diesel arb · $/mt · 11 Nov 26
Nov 26 -36.00
Dec 26 -14.25
Jan 27 -2.50
Feb 27 +10.25
Only February is open, and November is the big mover at -$22.00/mt lower on the week. The FSD model forecasts TC14 at WS 385 against WS 427 spot for the 16 to 25 November window. 7-day Houston MR tonnage is long at 26 vs 18 avg. TC14 to soften further.
5
1,090
The Panama Canal Authority (ACP) has raised daily transit capacity to 34 slots with effect from 12 November, citing improved water conditions, in an advisory issued on 9 November. The increase comes from an additional daily slot for Super category vessels at the Panamax locks, taking that allocation to 19 from 18. The ACP has also lifted the maximum allowable draft at the Neopanamax locks to 15.24 m, or 50 feet, from 14.94 m, or 49 feet. Both follow the move to 33 slots on 15 October. Less congestion, less inefficiency.
9
1,052
Since 6 October, spot TD25 has fallen from WS 1,000 to WS 324, and over exactly the same period the Sparta Crude Grade RBI on WTI Midland into NWE on an Aframax has moved from -$11.60/bbl to +$3.04/bbl. Spot USGC Aframax freight has had an incredible WS 676 point selloff, and WTI still became materially less competitive into Europe. The delivered cost of a WTI cargo collapsed and the crude RBI econs moved $14.64/bbl against it anyway. It’s a rare opposite move, and TD22 shows the same decoupling into Asia. WTI is simply not attractive globally, and until this improves, USGC DPP incremental vessel demand will stagnate. WTI/Brent needs to widen.
USGC VLGC tonnage closed out last week tight at 3 ships against a 90-day average of 6, but every Houston to Chiba propane window is currently shut. The 25 December loader is the least negative at -$30.64/mt. With a Mont Belvieu to FEI spread of $344.75/mt, a FOB of 7.25 cpg and $308.54/mt of freight, a fall of roughly 10% in VLGC freight rates opens it on its own. Cracker econs don’t support propane at these levels. Replacing 10% of a cracker’s feed on landed cost puts Houston propane at -$15.49/mt for 26 to 31 January delivery into Chiba against Fujairah OSN naphtha at -$0.46/mt, so propane is losing the marginal barrel to AG LRs, where LR2 counts are 15 against an average of 9. Spot has to weaken materially before propane competes with naphtha again.
Michael Ryan retweeted

USGC MR earnings are now more than double the Continent. Houston to Amsterdam returns $73,515 a day against $23,441 on Rotterdam to New York.
Only one Houston November arb window is still open. December demand is shifting to LatAm.
Read the full analysis, by @SpartaFreight: spartacommodities.com/market…
Try Leonidas AI now: spartacommodities.com/leonid…
#oott #oilmarkets

USGC MR supply is 9 ships in the seven-day ahead window against a 90-day average of 18, and the earnings spread across the Atlantic is wide. Houston to Amsterdam returns $73,515 a day against $23,441 on Rotterdam to New York, so TC14 is paying three times TC2. The problem is the arb board has turned more bearish. Three of the eight Houston November windows were open last Monday and only one is today, with Houston to Rotterdam diesel going from +$18.50/mt to -$14.00/mt. US clean product stocks at 350.0 MMbbl are 13.5 MMbbl below the five-year average and 1.0 MMbbl off the floor of the range, firming FOBs and narrowing margins. December demand has rotated to LatAm, with Buenos Aires diesel at +$12.45 cpg against Rotterdam at -$13.50/mt. December TC14 at WS 409 looks overvalued against that.
Michael Ryan retweeted

Our podcast is back! My team dissects the impact of the midterms to the war, oil and freight markets.
Meanwhile we have launched LPG in Sparta! Prices, VLGC freight rates and tonnage, LPG arbs and petchem margins.
Do reach out for more info. 😊
#oott

Brent has shed about 20% in a week. Is the Iran risk really fading?
The midterms, Hormuz and a stranded WTI barrel are all in play. Aaron Kildow, @SpartaFreight, Jay Maroo and James Noel-Beswick break it down on Trade with Conviction.
Inside this episode:
▸ Midterms: what a Democratic Congress could do to the war before January 3.
▸ Freight: dirty rates have crashed and tonnage is building in the Gulf.
▸ Fuel oil and diesel: the East-West trade, and why US diesel still won’t build.
▸ Crude: why WTI is stranded, and what Brent’s spread is signalling.
Watch the full episode here: spartacommodities.com/market…
Try Leonidas AI: spartacommodities.com/leonid…
#oott #oilmarkets #crudeoil #freight #oiltrading

WAF TD20 spot is at WS 430 with Suezmax tonnage at 10 ships in the 14-day ahead window against a 90-day average of 8. Spot has followed a similar selloff to TD25, but the forward curve has weakened even more. December settled at WS 350 last night and traded down to WS 325 after the print. TD20 paper shows the same lack of conviction as traders work to figure out the post-midterm market direction, with balmo trading from WS 426.17 down to WS 400 yesterday and December ranging from WS 290 to WS 340 before last trading at WS 325. Price action, the curve and tonnage supply are bearish.
TD25 spot has fallen from WS 1,000 on 6 October to WS 398 last night. Aframax tonnage is 26 ships in the 14-day ahead window against a 90-day average of 24, and the Sparta Crude Grade RBI on WTI Midland into NWE on an Aframax remains overvalued at +$2.01/bbl. US barrels are uncompetitive and vessel demand is suffering with it, even after this historic selloff. Paper action has no conviction as traders work to figure out the post-midterm market direction, with balmo trading from WS 465 down to WS 350 and back to WS 430 yesterday, and December paper ranging from WS 465 to WS 375 before closing back at WS 430. Charterers, wait for the dust to settle and fix into the weakness.
17
1,711
Houston → Rotterdam diesel arb · $/mt · 6 Nov 26
Nov 26 +14.75
Dec 26 +0.50
Jan 27 +22.75
Feb 27 +24.25
All four windows open. December is the outlier, effectively flat and down 7.50 on the week. 7-day Houston MR tonnage tight at 12 vs 18 avg.
6
742
Houston → Rotterdam diesel arb · $/mt · 6 Nov 26
Nov 26 +14.75
Dec 26 +0.50
Jan 27 +22.75
Feb 27 +24.25
All four windows open. December is the outlier, effectively flat and down 7.50 on the week.
5
671
The European diesel arbs did their job and pulled fixtures west. Yanbu to Rotterdam on an LR2 opened on 21 October and is wide open at +$31.87/mt for 1 to 5 December delivery, while Sikka to Rotterdam opened on 28 October and has already shut again at -$0.96/mt for 16 to 20 December after a single fixture. The past week of regional Red Sea/AG/WCI fixing is those LR2 arbs getting locked in: Expedition Sohar to Rotterdam with diesel at $10.0m LS for a 10 November laycan, Asp Luna Yanbu to UKC with diesel for 19 November and Sea Jewel on subs Sikka west with diesel for 18 to 19 November loading. AG LR2 open tonnage is 19 vessels against a 90-day average of 9, up from 2 on 2 October, even with the demand pull from the west. Spot TC20 rates have weakened accordingly, down $30/mt since last week to $214/mt. Owners, lock in a long-haul voyage if you can; excess tonnage will weigh on rates.
USGC VLGC supply is 3 ships in the 35-day ahead window against a 90-day average of 6, down from 9 last week. Spot BLPG3 has firmed around $5/mt on the tighter lists to $322/mt, but December paper keeps selling off, marked at $277/mt and down $10/mt yesterday. Houston to Chiba propane is shut at -$35.39/mt for 11 to 15 January and worsens to -$77.64/mt by 16 to 20 February. FOBs coming off $3.50 cpg over the past week helps the spot margin, but the arb still needs freight lower to work. That is a tough ask with VLGC counts this tight.
ARA to New York gasoline margins have improved dramatically this week, the 26 to 30 November window up from around -13.5 cpg on Monday to -6.80 cpg on a blender basis, but every window is still shut. On an NWE refinery basis that same window sits at -1.80 cpg. Under 2 cents and the late November dates open. TC2 would need to drop to WS 175 to open refiner margin arbs. The graph is blender margin.

6
665

The mid-December delivery Houston to Rotterdam diesel arb continues to be incredibly volatile. The arb is open with a margin of +$4.60/mt on an MR.

10
763
TD3c December paper has sold off hard, trading at WS 1,025 on Tuesday and at WS 850 yesterday, with the rolling M+1 contract now WS 450 points lower against a mid-October high near WS 1,300. The US midterm result accelerated the weakness. The risk is that the de-escalation trade doesn't play out this way. The electoral constraint that held President Trump back through October has disappeared. December TD3c paper is being sold into what feels like a coin-flip set of odds on an escalation risk.

AG LR1 supply is 17 ships in the seven-day ahead window against a 90-day average of 7, the longest count since 1 July. The count has not drawn down over the past two sessions. Incremental demand is negative now, and the Freight Supply and Demand (FSD) model forecasts TC5 at WS 1,009 against WS 1,043 spot. The pace of enquiry and fixing has slowed. Hafnia Excel fixed Sohar to Japan with naphtha at WS 480 for a 10 November laycan, illustrating that eastbound naphtha arbs are currently the main demand driver, with Jubail to Yeosu at +$65.25/mt for November. Charterers, rates are coming your way.