

Build your own automated, data driven portfolio.
Joined April 2021
- Tweets6.9K
- Following32
- Followers6.7K
- Likes2.9K





SK hynix ($SKHY) just turned 80% of its sales into operating profit.
Revenue: 104.6 trillion won, up 328% in a year. And the US-listed shares are still 27% below their September high.
The Korean memory chipmaker reported Q3 results on Oct 28 (Seoul time). Its HBM chips (high-bandwidth memory) sit next to AI processors and feed them data. It is the first quarter in company history with revenue above 100 trillion won.
💰 Revenue: 104.6T won (about $78B), up 328% vs Q3 2025
📈 Operating profit: 83.3T won, up 632%
🎯 Operating margin: 80%, up from 47% a year ago and 76% last quarter
🔁 2026 payouts: about 100T won in dividends and buybacks
📉 $SKHY: $145.36 on Oct 27, down 26.8% from $198.63 on Sep 9
Out of every 100 won of chips sold, 80 won was left after paying for factories, staff and research. The company expects its newest chip, HBM4, to outsell the older HBM3E in Q4.
Net income fell 58% from Q2 even as operating profit rose. And memory has always been a cycle: prices rise when supply is tight and fall when new factories come online.
A great quarter and a great stock are two different things. Rules-based investors decide in advance what they act on, like profits, price trend or valuation, so one headline does not make the call.
Does an 80% margin make you more or less nervous about memory chips?

Record quarters and falling stocks can happen at the same time. See how rules-based strategies handle cycles like this: surmount.ai/strategies?utm_s…
Not investment advice.

$META spent $26.26 billion buying back its own stock last year.
Now it plans to sell up to $95 billion of new stock.
On Monday, Meta launched about $35B of stock sales: roughly $22.5B of common shares plus $12.5B of preferred shares that turn into common stock in August 2029. Another $60B is planned as an "at the market" sale, meaning shares sold bit by bit at market prices, starting in early 2027.
Meta expects to spend $135B to $145B on buildings, chips and power this year. Its operating cash flow was $97B in the first nine months. The gap has to come from somewhere.
• $95B: the most new stock Meta plans to sell
• $26.26B: stock Meta bought back in 2025
• About 6%: $95B compared with Meta's total value at Monday's close
• 37%: drop in Q3 operating income, to $13B
• $630.56: Monday close, down 1.9% on the day and 19% below its Sep 24 high
When a company sells new shares, each existing share owns a slightly smaller slice. Buybacks did the reverse. Meta is betting the AI payoff is worth more than the slice it gives up.
Is this the moment Big Tech's AI bill lands on shareholders?

Big AI bills, bigger questions. If you would rather invest by rules than react to headlines, browse automated strategies on Surmount: surmount.ai/strategies?utm_s…
Elon Musk says more than 200 AI cloud companies face "guppy-level death."
Their stocks were already falling. CoreWeave ($CRWV) is down 60% in a year.
WHAT HE SAID
On X on Sunday, Musk wrote that debt markets have "almost entirely shut off" money for companies whose revenue depends on AI data centers. He said SpaceX closed $40B of debt for GPUs because it has Starlink and launch revenue behind it.
WHAT IS A NEOCLOUD
A company that rents out AI computing power (GPUs) to other businesses, often funded with debt and using the chips as collateral.
BY THE NUMBERS (1 year to Friday's close)
📉 CoreWeave $CRWV: -60.1%, at a 1-year low of $54.24
📉 IREN $IREN: -61.7%, at a 1-year low of $24.91
📈 Nebius $NBIS: +26.6%
Monday premarket: CRWV -4.3%, NBIS -3.4%, IREN -3.1%
THE CAVEAT
Musk's SpaceX is itself a big buyer of AI chips, so he is not a neutral observer. And balance sheets differ: Nebius is still up over the year.
THE TAKEAWAY
When a whole industry leans on the same source of money, its stocks tend to fall together. A rule that caps how much you hold in any one theme does its work before the headline arrives.
Would you still hold a neocloud stock after this?

Like the idea of setting your rules before the headlines hit? Browse automated, rules-based strategies on Surmount: surmount.ai/strategies?utm_s…
Not investment advice.
Tesla ($TSLA) just cut its 2026 spending plan by $5 billion.
Investors wanted it to spend more. The stock fell 3.9% before the open.
WHAT HAPPENED
Tesla reported Q3 results after the close on Oct 21. On the call, CFO Vaibhav Taneja lowered 2026 capital spending to about $20B, from "more than $25B." Capital spending (capex) is money for factories, chips and equipment.
THE NUMBERS
💰 Revenue: $28.05B, flat vs a year ago
📉 Operating profit: $718M, down 56%
🔬 Research spending: $2.76B, up 69% (AI, Optimus robots, Cybercab)
🏗️ Q3 capex: $4.73B, more than double last year's $2.25B
💵 Free cash flow: $1.53B
WHY THE CUT HURT
Spending less usually reads as good news. But many investors value Tesla as an AI and robotics company, and capex is the clearest sign of how fast it is building robotaxis and robots. Tesla also said Optimus sales to outside companies are now expected around the end of 2027.
THE BIGGER PICTURE
Meta reported the same night and plans to spend $135B to $145B this year. The same number, spending, can read as good or bad depending on the story a stock is priced on.
That's a reason rules-based investors decide what they measure before the headline hits, instead of after.
Would you rather a company spend big on AI, or hand the cash back to you?

Tesla, Meta and the rest of earnings week, explained in plain English. Join 10,000+ investors who read Surmount Markets every Friday:
surmount-investing.beehiiv.c…
Not investment advice.

Elon Musk says he will give one SpaceX ($SPCX) share to every kid in America next year.
That's about 73 million shares. At Monday's close of $147.96, roughly $10.8 billion.
WHAT HAPPENED
Musk posted on X on Monday: "Next year, I will give one of my SpaceX shares to every kid in America." He added it would be "the first of many."
THE NUMBERS
👶 About 73M Americans under 18 (Census)
💰 About $10.8B at $147.96 a share
📊 Roughly 1.2% of Musk's $908.5B net worth
📈 $SPCX: $135 IPO in June, $211.39 high close, $147.96 now
THE LIKELY ROUTE
Musk hinted at Trump Accounts, the new accounts for kids that launched July 4. Kids born 2025 to 2028 get a $1,000 seed from the Treasury. The money has to sit in low-cost funds that track broad US stock indexes, families can add up to $5,000 a year, and nothing comes out before age 18.
THE CATCH
So far there is only a post. No formal plan has been announced. Nobody knows yet who qualifies, how kids would claim a share, or when they could sell. Donated shares in these accounts can't be sold for 5 years.
THE TAKEAWAY
The accounts are really a set of rules: own the broad market, add on a schedule, wait. A single stock swings a lot (SpaceX has moved more than 30% since June). Rules are what keep a plan steady while the headlines move.
SpaceX reports earnings tonight after the close. Would you rather your kid get one SpaceX share, or $148 in an S&P 500 index fund?
Like the idea of investing by rules instead of headlines? Browse automated, rules-based strategies you can run in a brokerage account you already have: surmount.ai/strategies?utm_s…
Not investment advice.
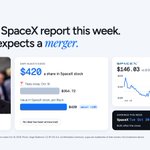
Tesla ($TSLA) and SpaceX ($SPCX) both report earnings this week. One well-known Tesla bull thinks the bigger news comes after.
Gary Black of Future Fund posted that he expects SpaceX to announce it is buying Tesla for $420 a share, paid in SpaceX stock, in the "next few weeks."
WHAT HAPPENED
Last Thursday Tesla showed its new Roadster in a livestream that Elon Musk shared with the caption "Tesla x SpaceX." Black wrote that the event's purpose was to make the case for a merger.
Neither company has announced anything. This is one investor's guess.
THE NUMBERS
🚀 $SPCX closed at $146.03 on Oct 16, vs a $135 IPO price in June
🚗 $TSLA closed at $354.72 on Oct 16, down 21% this year
🎯 $420 would be about 18% above Tesla's Friday close
📊 SpaceX last quarter: $7.8B revenue (up 92%), $541M net loss
📅 SpaceX reports Tuesday after the close. Tesla reports Wednesday after the close.
WHY IT MATTERS
A deal paid in stock would turn Tesla shareholders into SpaceX shareholders. Headlines like this can move both stocks before anything is confirmed, and Black himself says he is still cautious on Tesla's valuation.
THE TAKEAWAY
Rumors make great headlines and poor plans. Systematic investors set their rules (what to own, how much, when to sell) before the news, so one post on X does not rewrite the portfolio.
Would you rather own Tesla on its own, or as part of SpaceX?

Surmount Markets breaks down both earnings reports in plain English this Friday. Free:
surmount-investing.beehiiv.c…
Not investment advice.
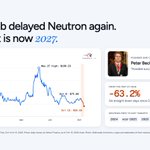
Rocket Lab ($RKLB) just pushed its Neutron rocket to 2027. That's the fourth delay since 2021, and the stock has closed lower six days in a row.
WHAT HAPPENED
On Oct 14, Rocket Lab said Neutron's first flight won't happen until 2027. Engineers found microscopic air voids in the first stage's propellant dome, so a new dome is being built and inspected before the end of Q1.
CEO Peter Beck: "Possible success isn't our standard."
THE SLIPS
🚀 2021: Neutron unveiled, targeting 2024
📅 Then mid 2025
📅 Then 2026
📅 Then Q4 2026, after a tank ruptured in testing in January
⏳ Now 2027
THE NUMBERS
📉 $75.06 on Oct 6 to $55.25 on Oct 15 (-26.4%)
📉 63.2% below its May 27 close of $150.23
📉 About 21% lower this year
WHY IT MATTERS
Neutron is Rocket Lab's bigger rocket, built to take on SpaceX for larger launches. Story stocks often trade on their next big milestone, and this one just moved out again.
THE TAKEAWAY
When one high-conviction stock is a big slice of your portfolio, a single engineering update can set the pace for everything you own. Rules for position size and rebalancing make that call before the headline does.
Would a fourth delay change how much of a story stock you'd hold?

Peter Beck on Neutron, from Bloomberg in August, before this delay: youtube.com/watch?v=CUZ49csv…
Prefer rules you set ahead of time? Run automated, rules-based strategies in the brokerage you already use with Surmount: surmount.ai/strategies?utm_s…
Not investment advice.
Surmount retweeted

Most investing apps either tell you what to buy or make you manage everything yourself.
@surmountinvest sits somewhere in between.
Pick a strategy. Connect your brokerage.
Let the rules handle execution, rebalancing, and position management automatically.
You stay in control. The repetitive work does not.

Michael Burry shorted Micron (solana:MUxEsUKSMACyw5fZf68wxf5FLnZVhtU9CwH8uNNGay1 ) at $1,051.87 in July.
Yesterday it closed at $914.13, down 13% from his entry.
Plot twist: he wasn't holding that short anymore. Here's what the Big Short guy did instead 👇
WHAT HAPPENED
📅 Jul 1: Burry tells his Substack readers he shorted Micron at $1,051.87
📅 Sep 28: He covers the short and swaps it for put options with strikes around $500, expiring in June. Micron closed at $1,053.98 that day, so the short itself ended roughly flat.
📅 Oct 11: In a post called "Consolidating the Big Short," he rolls most of his bets into puts on the Nasdaq-100 and the VanEck Semiconductor ETF ($SMH)
📉 Meanwhile, Micron fell 16% in five trading days, from $1,088.00 on Oct 7 to $914.13 on Oct 14
Quick translation: a short profits if a stock falls, with no deadline. A put is a contract that pays off if the stock falls below a set price (the strike) before it expires. Puts cap what you can lose at the price you paid, but the clock is always running.
WHY BURRY IS BEARISH
He argued memory chips are a boom and bust business: Micron has had 34 drawdowns of more than 30% in 42 years. He also pointed to the stock trading further above its 200 day average than at any point since 1984.
THE OTHER SIDE
Micron just reported record quarterly revenue of $54.23B and guided to about $61.5B for the next quarter. Management has said demand is running well above what it can supply through 2028.
And his Micron puts were struck around $500, about 45% below Wednesday's close.
WHY IT MATTERS
The most famous short seller on Wall Street went from betting on single names to betting mostly on baskets: the Nasdaq-100 and a chip ETF where Micron is about 5% of the holdings. He still kept a few single name puts, including Oracle and Palantir.
When he first swapped to puts, he said he was "moving timelines up" and wanted more leverage. Whatever the reason, a single stock bet asks you to be right three times: on the company, the price, and the timing. A basket only asks you to be right about the group.
THE TAKEAWAY
Systematic investors make these choices before the headline hits: how much goes into any one name, when a position gets cut, and when to spread risk across a basket instead. Rules don't make you right, but they keep one stock from deciding your whole year.
One stock or the whole basket: which would you rather be right about? 👇

Prefer rules over hunches? Browse automated, rules-based strategies that run on the brokerage you already use: surmount.ai/strategies?utm_s…
Not investment advice.
Berkshire Hathaway just bought $330M more of Bending Spoons ($BSP), the company behind Evernote, Vimeo and AOL.
It paid $33 a share. Tuesday's close: $37.86.
By midday, the stock was up about 35%. Here's the deal, the catch, and what it means for everyday investors.
WHAT HAPPENED
Berkshire is buying 10 million new shares directly from Bending Spoons in a private placement at $33 each. It already put $600M into the company's July IPO at $29 a share. Together that's about $930M and a roughly 4% stake.
It's also a window into Berkshire under Greg Abel, who took over as CEO from Warren Buffett at the start of this year. Reuters notes Berkshire has been adding tech exposure under Abel.
THE NUMBERS
💰 $330M new investment, 10M shares at $33
📄 $600M invested at the July IPO ($29/share)
🎯 About 4% total ownership
📉 -40%: BSP's slide from its Aug 11 close ($53.44) to its Oct 2 close ($32.03)
📈 About $51 intraday today vs. Berkshire's $33
WHAT BENDING SPOONS DOES
It buys established apps that have stalled (Evernote, WeTransfer, Vimeo, Eventbrite, AOL), cuts costs, rebuilds them, and puts the cash toward the next acquisition. So far it keeps what it buys instead of reselling.
Revenue grew 126% last quarter, mostly from acquisitions. Organic growth (from businesses it already owned) was 3%. The company says Berkshire's cash adds flexibility for more deals, and it agreed to buy Miro for $1.36B in September.
THE CAVEAT
After today's jump, The Motley Fool puts BSP at more than 16x sales and 130x earnings. Net debt was about $4.1B at the end of Q2, and BofA rates the stock Underperform. Famous investors can be wrong, and one big buy doesn't predict future returns.
THE TAKEAWAY
Berkshire got its shares at $33 in a private deal the public couldn't join. Anyone buying after today's headline paid roughly 55% more.
When a famous investor's move becomes news, the price can move before most people can act. That's why systematic investors decide their rules ahead of time: what to buy, when, and how much, so a headline doesn't make the decision for them.
Would you buy a stock right after a famous investor does, or wait for the dust to settle?
Want your portfolio to follow rules you set ahead of time? Browse automated, data-driven strategies on the Surmount marketplace: surmount.ai/strategies?utm_s…
Not investment advice.