

GS/J. Aron➡Canyon➡Akanthos➡Kao Family Office➡https://nitter.cf/t.co/6Us4owom5j📊Globetrotter✈ Headbanger🤘Star Wars Fan🌌 Mixologist🍸Diver🤿NO INVESTMENT ADVICE
Los Angeles, CA
Joined March 2009
- Tweets35.3K
- Following2.4K
- Followers116K
- Likes42.1K



Pinned Tweet
Re: Mental Models - Wile E. Coyote Equities & The Vanishing Bond Floor.
The backup in long-end rates has pulled the “Bond Floor” out from under Equities, and the only thing keeping the longest-duration names aloft is Growth. Wile E. Coyote better not look down!
Anyone who grew up on Saturday-morning Looney Tunes knows the rules. Wile E. Coyote chases the Road Runner straight off the edge of a cliff, and for a long, absurd moment nothing happens: his legs keep churning, he keeps running on pure air, and he hangs there in defiance of physics. Gravity only takes hold at the moment he looks down. Then comes the forlorn little wave to the camera, the long whistle, and the tiny puff of dust at the bottom of the canyon.
Longtime readers know that Wile E. Coyote is an old friend of mine. Back in February 2021 I asked whether “Risk assets marching higher while the 30-yr takes a dirt nap” meant Wile E. Coyote was running off the cliff before he discovered Gravity. The setup today rhymes uncomfortably well with that one.
On Monday I posted a Musing of the Day that has been rattling around in my head all week: “It’s a bizarre tape when Rate Angst dominates ‘rate sensitive sectors,’ yet some of the longest duration Equities still seem impervious to Rates... If growth prospects even suffer a whiff of disappointment, look out below.”
With the long end continuing to get crushed (the 30-year printing its highest level since 2004 and the 5-year clearing 5% for the first time since 2007), I want to lay out why I think the gap between where these Equities trade and where Gravity says they belong keeps getting wider.
This piece ties together many of my past Mental Models and will show you why I think long-duration Equities are behaving like Wile E. Coyote spinning his legs in mid-air before realizing that he is no longer on terra firma.
This is a FREE post, because I think the whole world needs to heed this warning.
urbankaoboy.com/p/re-mental-…


Michael Kao retweeted

Neoclouds: Credible Bearish Caution
@UrbanKaoboy understands commodities cycles and overbuilds better than almost anyone on X. He doesn't put out bear FUD unlike other ex-wall street big names and very clearly states what to look for on buildout cycles.
Michael Kao states that the rest of the supply chain will move on a second or third derivative speed of GPU pricing and will not wait for the slope to turn negative. Meaning sensitivity is high which is why we are seeing this pullback. This pullback doesn't necessary mean that it's the end of the AI buildout but illustrates well the sensitivity of markets to the downstream suppliers.
As an investor, I'm watching AI demand from the application and research layer to forerun actual AI demand in revenue of Frontier Labs.

Musings of the Day, 10/28/26
Lots of polarized takes on the Anthropic S-1.
I am not smart enough to know how this all plays out, but here are my concerns:
1. When you’re upstream in a supply chain (as data centers are in the AI ecosystem), you are subject to the Bullwhip Effect:
It describes how relatively small fluctuations in consumer demand become progressively amplified as they propagate upstream through the supply chain — from retailers to wholesalers, manufacturers, and raw material suppliers.
For example, a 5% increase in consumer demand might trigger a 10% increase in retailer orders, a 20% increase in distributor orders, and a 40% increase in factory production.
2. Right now, everyone is frothing at the mouth over Anthropic’s parabolic ARR growth and straight-lining tangents off of this trajectory but forgetting that Anthropic is relatively close to the FRONT of the Bullwhip, while data centers, GPUs, and power infrastructure sit further UPSTREAM. Anthropic entering into MASSIVE FIXED UPSTREAM COMMITMENTS could be an example of BYOBSS (Believe Your Own BS Syndrome).
3. Between the Debt Governor (which I have written extensively about) and the increasing popularity of Open Source models, what happens when consumer demand (at the FRONT of the Bullwhip) even hiccups, much less declines?? Indeed, demand doesn’t even have to decline — merely growing slower than anticipated could trigger a massive upstream correction, and Anthropic could be on the hook in a serious way if that happens.
Michael Kao retweeted

Looking forward to hosting @UrbanKaoboy on the @BuchalterLaw AI for Business Podcast next week, covering his takeaways from the Anthropic IPO youtube.com/post/UgkxJPmoA_U…

Musings of the Day, 10/28/26
Lots of polarized takes on the Anthropic S-1.
I am not smart enough to know how this all plays out, but here are my concerns:
1. When you’re upstream in a supply chain (as data centers are in the AI ecosystem), you are subject to the Bullwhip Effect:
It describes how relatively small fluctuations in consumer demand become progressively amplified as they propagate upstream through the supply chain — from retailers to wholesalers, manufacturers, and raw material suppliers.
For example, a 5% increase in consumer demand might trigger a 10% increase in retailer orders, a 20% increase in distributor orders, and a 40% increase in factory production.
2. Right now, everyone is frothing at the mouth over Anthropic’s parabolic ARR growth and straight-lining tangents off of this trajectory but forgetting that Anthropic is relatively close to the FRONT of the Bullwhip, while data centers, GPUs, and power infrastructure sit further UPSTREAM. Anthropic entering into MASSIVE FIXED UPSTREAM COMMITMENTS could be an example of BYOBSS (Believe Your Own BS Syndrome).
3. Between the Debt Governor (which I have written extensively about) and the increasing popularity of Open Source models, what happens when consumer demand (at the FRONT of the Bullwhip) even hiccups, much less declines?? Indeed, demand doesn’t even have to decline — merely growing slower than anticipated could trigger a massive upstream correction, and Anthropic could be on the hook in a serious way if that happens.
Musings of the Day, 10/27/26
Eye-opening. 👀
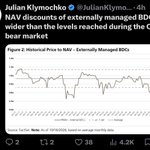
This is making me think that these CLO equity CEFs are ripe for acquisition as well by PE/SPAC to just acquire and liquidate.
When things trade to 40-50% discounts to already discounted NAVs for no underlying fundamental reason, Vultures (and Pelicans!) eventually show up.

Musings of the Day, 10/26/26
Crazy what a disconnect there is between what CLO equity CEFs are implying and what is actually happening in BSL.


Musings of the Day, 10/25/26
Two great questions presented by @bpmehlman that everyone should ponder. For me, they elicit two reactions:
On the former, this AI buildout reminds me of the dark fiber overbuild of the Dot Com Era where apparent short term PARABOLIC demand for compute leads to massively wrong LINEAR extrapolations, akin to drawing linear tangents off the very steep part of a parabola only to have that parabola turn out to be an S-Curve.
On the latter, I have written ad infinitum about how China’s Runaway Assembly Line was never predicated on Supply/Demand and Comparative Advantage and why this Faux Globalism is unsustainable. Any country that doesn’t protect itself from this Runaway Assembly Line inevitably becomes de-industrialized.


Weekly KAOS - The AI Crack, the Hot Print, and the Debt Governor
The AI trade finally cracked and bonds rallied into a hot CPI, which reads to me as a growth scare with the Debt Governor on the throttle
Welcome to the Weekly KAOS — UrbanKaoboy’s end-of-week roundup covering Macro and Geopolitics, where I try and tease out the most impactful bits of the week.
Themes of the Week
The AI trade finally started cracking, and what gave it away was the Bond market rallying straight into a hot CPI, which reads to me as a growth scare more than Inflation, with the Debt Governor and not a Fiscal reckoning on the throttle.
This week the Credit market and the Equity market looked at the same company and could not agree on whether it was still breathing. CoreWeave’s five-year CDS blew out to levels implying better-than-even odds of default, while its stock still carries a roughly $35B price tag. That gap is a microcosmic look at the whole AI story, because the buildout has shifted from running on Equity “funny money” to running on Debt, and Debt comes with a governor of real cash interest payments and refinancing risks that Equity does not have.
The rest of the tape rhymed. Semiconductors fell for eight straight sessions, Character.AI filed for bankruptcy, and a line of data-center IPOs got pulled, even as September CPI ran hot at 3.7% and the 10-year yield still FELL on the week. TLT turned without anyone needing to intervene, and as I posted, that worries me far more about growth than it reassures me about rates.
I read this the way I have since last December. It is the Debt Governor at work, the AI buildout saturating the capital markets with paper and competing ferociously for capital, and it is the single biggest threat to my hoped-for Goldilocks denouement of Disinflationary Growth. None of it is a verdict on AI’s long-run Deflationary productivity, which I still believe in.
Oil presented a renewed Macro wildcard, ripping to five-month highs as Houthi strikes hit Saudi Aramco and Washington drew up fresh plans for Iran, French yields blew out to their widest spread over Bunds since the 2011 Eurozone crisis.
If it’s not evident already, this global yield repricing is hardly idiosyncratic to America. It’s also worth remembering that this repricing, however painful the adjustment, is restoring us to the long-term normal and that it was the extended period of ZIRP (Zero Interest Rate Policy) that was the true aberration.
urbankaoboy.com/p/weekly-kao…
🤖 Made with AI

Musings of the Day, 10/22/26:
Earnings season is once again upon us, and despite the rosy headlines from some of the Tech bellwethers (after all, Nothing Else Matters 🤘 besides Big Tech these days), Macro sentiment has decidedly turned wobbly as the Wile E. Coyote Equity market finally looked down and pondered the impact of gravity and much lower implied "bond floors."
As I explained in my piece several weeks ago before the tape turned, rapidly receding "bond floors" due to the Debt Governor blowing yields out meant that implied growth rates were getting higher and higher -- unless equity valuations adjusted sharply lower.
Now we are seeing the beginnings of this adjustment even as long bonds are finding their footing on economic growth concerns and flight-to-quality fears.
The problem for Wile E. Coyote Equities is that the implied growth rates are so extreme in many cases that the fall off the proverbial cliff will be extremely steep before equilibrium is reached.
This is why I've been saying that the path to a 2-3% Fed Funds likely comes from an Economic/Market BUST, so be careful what you wish for.
Happy Early Halloween! ☠️
seehttps://nitter.cf/UrbanKaoboy/status/2106371325271171086?s=20


CLO Equity CEF peeps, 10/19/26:
I've finally made the CLO CEF Dashboard available to paid subs.
Check out the Subscriber Apps section of UrbanKaoberg.com!

Musings of the Day, 10/18/26
As I bask in the afterglow of Show #22, it dawned on me that all guitarists experience the same shared hallucination that elicits this common facial expression. 🤘🤘🤘


Weekly KAOS - The Monkey's Paw, the Hawkish Fed, and the Debt Governor
Many bellyache about the backup in yields to pre-GFC levels, but be careful what you wish for, because the most likely road to significantly lower rates runs through an economic and market BUST.
Welcome to the Weekly KAOS — UrbanKaoboy’s end-of-week roundup covering Macro and Geopolitics, where I try and tease out the most impactful bits of the week.
Themes of the Week
The Warsh Fed's recent hawkish lurch has caused many to bellyache about the backup in yields to levels last seen before the Global Financial Crisis, but the most likely road back to significantly lower rates runs straight through a potential economic and stock market Bust.
In the old W.W. Jacobs horror story, a family comes into a mummified Monkey’s Paw that grants three wishes, and the terror is that it grants each one in the cruelest way imaginable: they wish for money, and it arrives as the compensation check for their son, freshly killed in the machinery at the mill. I could not stop thinking about that this week, because the whole market seems to be quietly wishing the Warsh Fed back toward two or three percent Fed Funds, and as I posted on X, be careful what you wish for, because the likeliest path to rates that low is not a gentle glide but a brutal economic and market BUST. The Debt Governor is in charge now, and it’s the biggest threat to my hoped for Disinflationary Growth Goldilocks.
The tape handed the hawks the microphone through midweek: the September minutes leaned hawkish, Governor Waller called for more hikes, and the market priced a December move near certainty, with the long end ripping to multi-decade highs. Then the AI trade cracked wide open, the Wile E. Coyote Equity market finally looked down, Warsh signaled no rush to hike this month, and the long end rallied hard, turning $TLT around without any intervention, which worries me far more about growth than it reassures me about rates.
The Debt Governor is finally throttling growth, because of a higher neutral rate (a Cyclical phenomenon) rather than any Fiscal reckoning. The fact that French and Japanese yields punched through their own multi-decade highs alongside ours shows this is not idiosyncratic to America. The US is still the cleanest dirty shirt, and a selloff in Treasuries reprices GLOBAL yields.
Given the Debt Governor dynamic in particular, I don’t think the economy can handle Fed Funds approaching 5% percent. I think Bessent and Warsh both know this and will adjust accordingly, which still keeps the Benign Gravity of Disinflationary Growth as my base case even before Oil and China add their noise.
urbankaoboy.com/p/weekly-kao…


Now you know my inspiration for this piece:
open.substack.com/pub/urbank…

