

The financial dashboard for Canadians. See everything you have, know if you're on track.
Get started here →
Joined May 2025
- Tweets103
- Following1
- Followers15
- Likes337

Greenline retweeted

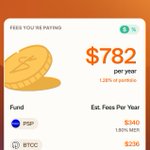
0.4% on a $180K portfolio = $720/year
0.9% on a $180K portfolio = $1,620/year
Under 1%, lots of people don't bother checking the difference.
But that's still $900 a year walking out the door.
That's why @useGreenline displays your portfolio's fees in dollars, not percentages.

Greenline retweeted
It's actually nearly guaranteed that you can become a millionaire in your lifetime.
Invest steadily in index funds and the math checks out.
You can backtest it.
It just sounds so unbelievable that it feels like there should be a catch.
There really isn't one, except that you can't interrupt your own compounding.
Greenline retweeted
The TFSA might be the most underused wealth-building tool in Canada. Tax-free growth, no lifetime cap on gains, and most people still haven't maxed theirs out.
Greenline retweeted
$BMO has been paying a dividend, uninterrupted, since 1829. 197 years. Through world wars, depressions, and financial crises. Hard to bet against that kind of track record.

Greenline retweeted
Nobody talked about money in my house growing up. I didn't know what a GIC was until a bank teller asked why I was leaving everything in chequing. Most people's financial education starts the same way: accidentally.
Greenline retweeted
Dark Mode now available for @UseGreenline. Perfect for doomscrolling your portfolio late at night.
Greenline retweeted
And the Canadian version of this 🇨🇦
1. TFSA
Money goes in post-tax. Grows tax-free. Comes out tax-free. No age restriction on withdrawals. Can re-contribute anything withdrawn the next Jan 1.
2. RRSP
Money goes in with a tax deduction if you claim the contribution. Grows tax-deferred. Taxed as income when you withdraw.
3. Non-registered
Money goes in post-tax. Interest, dividends are taxed yearly, capital gains in year of disposition.

Most people do not understand how their investments are taxed by account type:
1. Roth
Funds go in post tax
No tax on interest, dividends, capitals gains, etc.
You can get funds out tax free post 59.6
2. Pre-tax
Funds go in pre-tax
No tax on interest, dividends, capitals gains, etc.
Pay income tax when funds come out post 59.5
3. Taxable
Funds go in post tax
Taxed on interest, dividends, capitals gains, etc. generated yearly
No tax on taking the funds out
Greenline retweeted
People imagine a crash as something they’ll observe from a distance and act on rationally. But you don’t observe a crash. You live through it.
usegreenline.com/articles/if…
Greenline retweeted
Couldn’t agree more. Too many investors have no idea what’s in their portfolio.
That’s why we’re building @UseGreenline

Greenline retweeted
If you’re early in your career and not yet earning a high salary, maxing out your TFSA is almost always the better first move.
Where the RRSP shines: if your income is high today and you expect it to be lower in retirement.
usegreenline.com/articles/tf…