

There are two kinds of people. Those who are humble and those who are about to be.
Noida
Joined June 2021
- Tweets4K
- Following173
- Followers7.4K
- Likes2.9K





Pinned Tweet
Simple thesis: Buy well run, well financed, efficient capital allocators, market leaders that are available cheap at the trough of the market cycles.
How often do you find this combination? Frequent buying/selling makes very little sense.

Unknown Market Wizards retweeted
Dee Development Engineers raised 300 Cr though preferential issue at 502 rs/share where promoter as well as domestic and foreign investors participated (allotment date 8th July 2026).
Purpose: to reduce debt and strengthen the balance sheet.
Added the thesis and key risks below 👇


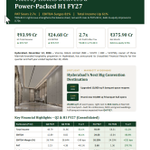
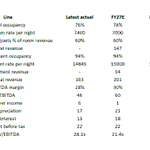
Viceroy Hotels Q2 FY27: Strong set, not comparable YoY though. Marriott executive apartments numbers weren't there previous year.
Courtyard occupancy increased from 31.5% to 87.4% YoY. Ongoing renovation caused 2 Cr EBITDA loss in Q2 that caused 20% dip in hotel F&B sales.


Viceroy Hotels: From bankruptcy to turnaround?
Background: Viceroy went into insolvency in 2018. In 2023, Anirudh Agro Farms won the company with a 168.5 Cr resolution plan against 768 Cr of admitted claims and bought these two Hyderabad hotels with ~460 rooms (for ~37 lakh/room) :
-Marriott Hotel & Convention Centre
-Courtyard by Marriott
In January new management added another asset: Marriott Executive Apartments. Before the deal, ownership was split between 2 parties. One owned the land + building and another party called SLN Terminus leased the property and ran the apartments under Marriott brand. Viceroy bought both pieces, land & SLN as a subsidiary for a combined 206 Cr at less than 10x EBITDA.
Why Q1 looks big: Sales up 77%, EBITDA up 144% YoY. MEA added ~12 Cr, Courtyard was under renovation a year ago. Like for like hotel part grew 30% YoY. MEA purchase was funded with ~200 Cr debt. Interest cost & depreciation ate profits.
Rights issue: Promoters were holding 84%. Viceroy did a 105 Cr rights issue at 115 Rs/share, promoters gave up the entitlement and have now come down to 74%. Money goes to:
-Repaying MEA acquisition debt (41.35 Cr)
-Repaying subsidiary loans (38.9 Cr)
-General purpose (25.6 Cr)
80 Cr of debt repayment saves ~7 Cr interest cost.
Zerodha founders Kamath brothers acquired 6.72% in the September, same quarter when rights issue came.
40% margin aspiration: Management guides 30% margins for full year and targeting 40% in the long term. Q1 is generally the weakest for city hotels, H2 is the stronger (Q4 FY26 margins ~31%). MEA might lift the margins as about 72% of sales comes from rooms, which earn 80-85% gross margins vs 45-50% for food and banquets.
(Negative: Convention centre stays shut until December so hotel misses the wedding season. Long term 40% target needs convention centre back + higher room rates.)
With convention center shut, hotel took lower paying bookings to keep occupancy up. Given convention center will be there in H2 onwards and renovated courtyard rooms could sell higher, margins could inch up going forward.
FY27 and FY28 earnings build: Screener shows TTM EV as 1396 Cr which takes pre-rights level debt. Adjusting for rights money, EV would be ~1290 Cr.
Closest peers are business hotels like Brigade that hand operations to Marriott, Hyatt or IHG. Brigade trades at half the valuation, however its a recent listing with a heavy capex pipeline to FY31 that will need more spending and debt.
Just a study, no recommendations.

6
832
Unknown Market Wizards retweeted
A few months later...
Also Motilal Oswal😀
DCB Bank was a potential 100 bagger in 2014.


A few months later...
Also Motilal Oswal😀
DCB Bank was a potential 100 bagger in 2014.
Dee Development Engineers raised 300 Cr though preferential issue at 502 rs/share where promoter as well as domestic and foreign investors participated (allotment date 8th July 2026).
Purpose: to reduce debt and strengthen the balance sheet.
Added the thesis and key risks below 👇

FY21 was a depressed base. In next 5 years, pre-tax ROIC went from 9% to 17%, drove a massive rerating and stock returned 35% cagr.
Reinvesting ~90% of operating profits, business earned 15% incremental ROIC in an unusually favourable period (also historical best) which implies 13-14% sustainable growth potential.
What multiple would you pay for this? For me, to justify materially higher growth, incremental returns must improve.


Sometimes stocks can de-rate without any reason or just because of lack of market interest.
One eg recently is that of Time technoplast where the co has consistently delivered 20%+ PAT growth, deleveraged and the volumes have grown in double digits.
Yet, the PE multiple has de-rated from 30x to 15x and stock has effectively gone through a time correction of 2 years. In the most recent Quarter as well they have delivered nearly 25%+ PAT growth.
The more one spends time in markets, the more one gets to learn about different situations. Time correction or just lack of interest is something that can happen in smallcaps.
Disc: no reco to buy or sell. Pure idea is to share the mental model of time corrections in small caps.

11
1,335
Been lazy on the posting front but keeping track of the results. Q2 FY27 has been pretty strong, hardly any disappointments so far.
Some of the results/calls/business trajectories I liked:
Orient Electric
Sterlite Tech
Garware Hi Tech
Coforge
SG Finserve
Tips Music
The Indian Hotels Company
International Gemological Institute
Steel Strips Wheels
Jayaswal Neco

Unknown Market Wizards retweeted
Dhanteras trivia: People used to worship lord Dhanvantari (the God of well-being) on 13th day of Kartik month as per lunar cycle. The day is called trayodashi.
Deliver stellar results, only to get hammered next day. 😅
As if global uncertainties were not enough, leverage is adding another layer of complexity to the market. Price action is becoming increasingly disconnected from the underlying operating performance.
Unknown Market Wizards retweeted

How can democrats slow down AI progress unilaterally by slowing build out of data centres- what about China?
Do they cede their number 1 rank to China in this field?
You cannot put the genie back in the bottle.


Unknown Market Wizards retweeted
One week of bounce, and entire narrative on IT Service companies have changed
Meanwhile, these are the QoQ earnings print of top 7 IT Service companies
(this is after many inorganic acquisitions in last several qtrs)
Are they oversold? Yes
Are they cheap? Yes
Can they grow at high rates this year? No

Unknown Market Wizards retweeted

You can now listen to live Concalls directly from Screener. Just click and join, no need to dial any number.
This one was really fun to develop as we didn’t know the iPBX in our office was capable of doing this.


Indian IT Q2 numbers so far:
- CC growth in low single digit
- Core services demand is muted
- AI revenue is rising but not large enough to offset deflationary impact
- Guidance isn't encouraging
Numbers dont really back the enthusiasm the market is showing, so maybe the bottom is in. But you're looking at 4-5% div yield + low single digit growth as of now. Best case 9-10% returns before any rerating.
Viceroy Hotels: From bankruptcy to turnaround?
Background: Viceroy went into insolvency in 2018. In 2023, Anirudh Agro Farms won the company with a 168.5 Cr resolution plan against 768 Cr of admitted claims and bought these two Hyderabad hotels with ~460 rooms (for ~37 lakh/room) :
-Marriott Hotel & Convention Centre
-Courtyard by Marriott
In January new management added another asset: Marriott Executive Apartments. Before the deal, ownership was split between 2 parties. One owned the land + building and another party called SLN Terminus leased the property and ran the apartments under Marriott brand. Viceroy bought both pieces, land & SLN as a subsidiary for a combined 206 Cr at less than 10x EBITDA.
Why Q1 looks big: Sales up 77%, EBITDA up 144% YoY. MEA added ~12 Cr, Courtyard was under renovation a year ago. Like for like hotel part grew 30% YoY. MEA purchase was funded with ~200 Cr debt. Interest cost & depreciation ate profits.
Rights issue: Promoters were holding 84%. Viceroy did a 105 Cr rights issue at 115 Rs/share, promoters gave up the entitlement and have now come down to 74%. Money goes to:
-Repaying MEA acquisition debt (41.35 Cr)
-Repaying subsidiary loans (38.9 Cr)
-General purpose (25.6 Cr)
80 Cr of debt repayment saves ~7 Cr interest cost.
Zerodha founders Kamath brothers acquired 6.72% in the September, same quarter when rights issue came.
40% margin aspiration: Management guides 30% margins for full year and targeting 40% in the long term. Q1 is generally the weakest for city hotels, H2 is the stronger (Q4 FY26 margins ~31%). MEA might lift the margins as about 72% of sales comes from rooms, which earn 80-85% gross margins vs 45-50% for food and banquets.
(Negative: Convention centre stays shut until December so hotel misses the wedding season. Long term 40% target needs convention centre back + higher room rates.)
With convention center shut, hotel took lower paying bookings to keep occupancy up. Given convention center will be there in H2 onwards and renovated courtyard rooms could sell higher, margins could inch up going forward.
FY27 and FY28 earnings build: Screener shows TTM EV as 1396 Cr which takes pre-rights level debt. Adjusting for rights money, EV would be ~1290 Cr.
Closest peers are business hotels like Brigade that hand operations to Marriott, Hyatt or IHG. Brigade trades at half the valuation, however its a recent listing with a heavy capex pipeline to FY31 that will need more spending and debt.
Just a study, no recommendations.
Unknown Market Wizards retweeted

“Most textbooks advise asset liability match so your assets and liabilities have to match but money is made by doing an asset liability mismatch.”
That was August 2017, the year the best-known housing finance stocks nearly doubled. They went on to fall 92% from their peak.
By the time everyone is talking about a theme, most of the money has been made. We went back over the sixteen that led the Indian market between 2015 and 2023, and looked at what happened if you bought each one once it was popular. For a year or so, it worked.
Three years in, 13 of the 16 had lagged the NSE500, and the typical theme had fallen 40% from its peak along the way. We’ve pitched a few of these names at the wrong time ourselves. The deck ends with five questions we ask before buying into a hot theme. The one for this platform: would we invest in this theme if it was not popular on X?
The full deck is accessible in .pdf format here: docsend.com/view/g3vkigu8v8i…
