






What moved overnight:
1. The S&P 500 fell 1.9% Monday, its third straight down day, and the Nasdaq Composite lost 2.5%. Chips fell about twice as hard as the Nasdaq: the VanEck Semiconductor ETF $SMH dropped 5.1%, with SanDisk $SNDK -8.6%, Micron $MU -7.6%, Intel $INTC -7.0% and TSMC's US-listed shares $TSM -6.3%. The VIX volatility index jumped 18.7% to 22.91. Nvidia $NVDA lost 4.1%, less than the chip ETF, but the cloud operators it backs fell further: IREN $IREN -9.8%, Nebius $NBIS -7.6%, CoreWeave $CRWV -6.1%.
2. The Commerce Department moved to close the remote-access route around US chip restrictions. Under a new interim final rule, overseas data centers supplying significant computing power to companies headquartered in China or Macau will need a US license. Those already doing so have 90 days from the effective date to get one or face future export restrictions. Exporting advanced AI chips to Indonesia, Malaysia, Singapore, Thailand and Brazil will also require a license, except for chips going to US-headquartered companies that meet reporting requirements. The rule scraps the worldwide license requirement from the January 2025 "AI Diffusion" rule, and it takes effect when it publishes in the Federal Register on Nov 19. In Hong Kong, China's own chipmakers are jumping, with SMIC +8.7% and Hua Hong Semiconductor +9.3%, reportedly on expectations the rule speeds the push for homegrown alternatives. Alibaba is down 4.9% and Tencent 3.0%, as Chinese AI developers and data center operators reportedly slide on worries about access to computing power.
3. Asia is extending Monday's slide. Taiwan's Taiex is down 2.1% after a 6.0% drop Monday, Korea's Kospi is down 1.8% after a 3.6% fall, and Japan's Nikkei 225 is off 1.2% after losing 2.4%. In Tokyo, Kioxia is down 6.7%, Advantest 4.9% and SoftBank Group 4.4%. Samsung Electronics is down 2.6% in Seoul and TSMC 1.4% in Taipei. The Taiwan Stock Exchange reportedly said late Monday it would take necessary stabilisation measures, with the market reportedly down nearly 15% over the past month.
4. Nvidia $NVDA reports after today's close, with results around 4:20 pm ET and the call at 5 pm. It is the first report without Jensen Huang as CEO, and interim CEO Colette Kress is in charge. Analysts expect about $108.7B in revenue for the quarter ended Oct 25. That is a bit above the midpoint of the company's own $108.0B forecast, plus or minus 2%, which assumed no China data center compute revenue. They expect $2.47 in earnings per share. Kress is reportedly expected to rein in Nvidia's financing of its own customers, the cloud operators and AI startups. The board is reportedly focused on its investigation and not discussing a Huang return, though Trump reportedly said Monday he would welcome Huang being reinstated. Bessent's 10-day deadline for the board on export compliance falls around Nov 25. An unconfirmed rumor that Vera Rubin volume production will slip to 2027 remains unaddressed by Nvidia.
5. Yields and oil eased. The 10-year Treasury yield closed Monday around 5.12%, down from 5.15% Friday. Brent is near $91.8, about 4.2% below Friday's $95.84, and WTI is near $85.1. Separately, the IEA reportedly now expects the oil market to swing to a surplus in the fourth quarter. US futures are mixed: S&P 500 flat, Nasdaq 100 +0.3%, Dow -0.3%.
6. Crypto stocks and funds fell Monday: iShares Bitcoin Trust $IBIT -5.5%, Strategy $MSTR -7.7%, Coinbase $COIN -6.1%. Bitcoin is around $64,900, down 0.6% over 24 hours. MSCI removes Strategy from its indexes on Nov 30.
7. Molina Healthcare $MOH jumped 11.3%. The move is reportedly tied to CMS letting states apply a grace period on Medicaid work requirements through the end of June 2027. Peers rose less: Centene $CNC +4.9%, Elevance $ELV +3.9%. Summit Therapeutics $SMMT fell 16.5% in its first session after Sunday's FDA Complete Response Letter for ivonescimab in EGFR-mutant lung cancer.
8. Insider buying in Monday's Form 4 filings: HubSpot $HUBS CEO Brian Halligan bought about $5.0M of stock. Atlassian $TEAM's CEO and co-founder bought about $2.0M under a pre-arranged Rule 10b5-1 trading plan. A Sonos $SONO director bought about $1.87M in the open market. Kura Oncology $KURA's CEO bought about $1.5M, and four Forgent Power Solutions $FPS insiders, including the CEO and CFO, bought about $1.08M combined.
9. Still ahead: Fed Governor Waller speaks on payments at 9:10 am ET today. On Wednesday, minutes of the Fed's Oct 27-28 meeting come out at 2:00 pm ET, and Palo Alto Networks $PANW reports. Anthropic is reportedly set to price its IPO Wednesday, in a reported $70-78 range for 825M shares, and reportedly starts trading Thursday under ANT. Walmart $WMT reports Thursday.
Eyes on the open.
1
46
What moved overnight:
1. Asian chip stocks sold off hard to start the week. With sessions still trading, Taiwan's Taiex is down 4.9%, Korea's Kospi 3.0% and Japan's Nikkei 225 1.9%. In Tokyo, Lasertec is down 11.3% and Advantest 10.6%. In Taiwan, TSMC $TSM is down 4.0% on its home listing and Alchip 8.3%. Commerzbank reportedly calls the Nvidia fallout the main driver of sentiment, with investors rethinking the whole AI trade, Nvidia's rivals included. Taiwan also has an unconfirmed rumor, first out Nov 12, that volume production of Nvidia's Vera Rubin slips from late 2026 to the first half of 2027. Nvidia has not confirmed it. Taiwan's circuit-board laminate and substrate makers fell at or near the 10% daily limit. US futures are softer: Nasdaq 100 -0.4%, S&P 500 -0.2%, Dow flat.
2. Nvidia $NVDA got a deadline from Washington. Treasury Secretary Scott Bessent said Sunday that the board should look outside the company for its next CEO. He gave the board, working with outside counsel, 10 days to show Nvidia complies with chip export rules, which puts the deadline around Nov 25. He also asked whether Nvidia pushed questionable sales to hit its revenue and earnings numbers. Separately, Jensen Huang has reportedly discussed a return with people close to him. Nvidia has not confirmed it. The board is continuing its independent investigation and says it has not formally engaged any candidates. Tuesday's earnings after the close bring the first public remarks from interim CEO Colette Kress.
3. The FDA issued a Complete Response Letter to Summit Therapeutics $SMMT, declining to approve ivonescimab plus platinum chemo for EGFR-mutant lung cancer after earlier EGFR-targeted treatment. The FDA said that without a statistically significant improvement in overall survival, substantial evidence of effectiveness was not established. It added that delaying cancer progression alone does not support a positive benefit-risk profile. Summit gave no timeline to resubmit and is continuing its other programs, including first-line lung and colorectal cancer. Monday is the stock's first session since the letter.
4. Iran's Revolutionary Guards said they hit Bahrain's Riffa air base with six drones on Sunday. That is their second attack on Bahrain in three days, after about two months of quiet. Bahrain said it intercepted the attacks, and US Central Command reported no damage to US forces. Iran's earlier claim that three tankers hit mines is still unconfirmed by any maritime body or insurer. Oil is lower anyway: Brent is down 0.5% from Friday at $95.39 and WTI is down 0.2% at $88.43.
5. China and Japan both came in below expectations. China's October retail sales grew 0.4% from a year earlier, against roughly 0.8% expected, slowing from 1.1% in September. Industrial output rose 4.8% against roughly 5.3% expected. Japan's economy shrank at a 0.1% annualized pace in Q3 on the first estimate, against expectations for roughly 0.3% growth. It is the first contraction in four quarters, and private consumption fell 0.3% from the prior quarter. The yen is around 159.7 per dollar, close to the 160 level where Tokyo has warned it could intervene.
6. Silver futures dropped 3.4% to about $47.5, and gold eased 0.3% to about $3,874. Bitcoin is near $64,900, down 0.6% overnight and roughly 5% below Friday's ~$68,250. For Strategy $MSTR, MSCI's removal from its indexes, announced Nov 11, takes effect Nov 30.
7. Form 4: no insider buys were filed this window, since the SEC does not accept filings on weekends.
8. The week ahead: Fed Chair Kevin Warsh opens a Fed conference today at 12:00 ET. Tuesday brings US retail sales at 8:30 ET and Home Depot $HD earnings. Wednesday has FOMC minutes at 2:00 ET, Palo Alto Networks $PANW earnings and, reportedly, Anthropic's IPO pricing, with a reported range of $70-78 on 825M shares. Anthropic is reportedly set to start trading Thursday under the ticker ANT, the same day Walmart $WMT reports.
Eyes on the open.
146
What moved overnight:
1. Nvidia $NVDA flipped from a 2.2% gain at the open to a 2.0% loss at the close. That put its market value back below $4T and left the stock down about 13% for the week. The leadership question is still open. Colette Kress is interim CEO after Jensen Huang's departure earlier this week. The board reportedly approached Arm $ARM CEO Rene Haas as one of several candidates, and shareholders including Altimeter and Atreides reportedly asked the board not to rush a permanent pick. HSBC reportedly downgraded the stock to hold. Treasury Secretary Bessent reportedly said blacklisting Megaspeed, the Nvidia customer at the center of the China scandal, is in the Commerce Department's hands.
2. AI hardware stocks fell broadly. The chip ETF $SMH dropped 3.0%. AMD $AMD fell 8.8% after gaining about 19% earlier in the week, and Broadcom $AVGO fell 4.8% a day after rising 5.5%. Dell $DELL lost 7.2%, Credo $CRDO 5.9%, Marvell $MRVL 4.7% and Arm $ARM 4.6%. Cerebras $CBRS went the other way, up 11.2% after its earnings. The Nasdaq fell 0.9% and the S&P 500 0.4%, while the Dow edged up 0.1%. The Nasdaq still finished the week up about 2%.
3. Cisco $CSCO reported record quarterly revenue of $18.5B, up 24% from a year ago. It raised its full-year revenue outlook to $74.8B-$75.8B. It also lifted its forecast for AI infrastructure revenue from hyperscalers to $9B this fiscal year, more than double last year's. The weak spot was margin: non-GAAP gross margin fell to 65.6% from 68.1% a year ago, so Cisco is selling a lot more but keeping less of each dollar as gross profit. The stock fell 6.2% Friday, a drop reportedly tied to margin pressure from a lower-margin AI hardware mix and costlier memory.
4. AI cloud stocks fell hard. Nebius $NBIS dropped 9.9% and is down about 25% over two days. In a shareholder letter earlier this week, it said it expects 2026 revenue at the low end of its guidance, with capex of about $27B and some site deliveries pushed into 2027. CoreWeave $CRWV fell 6.1%, IREN $IREN 6.7% and Applied Digital $APLD 5.8%. CoreWeave is reportedly seeking a loan of more than $4B secured by its Meta $META contracts at about 7%-7.5%, less than half the roughly 16% on its unsecured bonds.
5. October producer prices rose 0.3% on the month, a sharp slowdown from September's 1.4%. They are still up 6.5% from a year earlier, the biggest 12-month rise since November 2022. Prices excluding food, energy and trade services rose a faster 0.5% on the month. The 10-year Treasury yield closed at 5.15%, up 5 basis points, and a December rate hike is reportedly almost fully priced in. The yen briefly weakened past 160 per dollar, and Japan's finance minister called the move one-sided and too fast.
6. Bitcoin broke below $70K on Friday and trades near $66,730, down from about $71.3K at Thursday's close.
7. A nationwide FAA ground stop reportedly halted departures for more than five hours Friday and led to over 5,000 flight cancellations, with disruption spilling into the weekend and Monday. Officials reportedly cite a communications failure, not an attack.
8. Insider buying this week: At Starwood Property Trust $STWD, the CEO and chairman bought about $14.7M of stock and a director added about $2.0M. Three MP Materials $MP insiders, including the COO and CFO, bought about $3.35M combined. Akamai $AKAM's CEO bought about $2.55M and Coherent $COHR's CEO about $1.0M, both after insider selling at their companies earlier this year.
9. Next week: Fed Chair Kevin Warsh speaks Monday at noon New York time. Nvidia $NVDA reports Tuesday, its first results since Huang's departure. Minutes from the Fed's October meeting come out Wednesday at 2pm New York time. Anthropic's IPO is reportedly expected to price the same day and start trading Thursday.
1
2
277
What moved overnight:
1) Nvidia $NVDA said Jensen Huang resigned as President, CEO and board member, effective immediately, and gave no reason. CFO Colette Kress is interim CEO while staying CFO, former Synopsys CEO Harvey C. Jones becomes the board's first-ever Chair, and the board is searching internal and external candidates for a permanent CEO. The stock opened down 13.1% and closed down 4.3% at $166.19, and earnings stay on Tuesday, Nov 17, the first results under Kress.
2) The board says it has "full confidence in Colette" and expects operations, customer commitments and the product roadmap to continue without interruption. Market commentators, who describe Nvidia as the "bank of AI" for AI-focused cloud providers by guaranteeing debt, investing in customers and securing TSMC capacity, question whether that role continues without Huang.
3) The exit has reportedly been linked to Huang's relationships, including one with a woman US agencies reportedly suspect of working for China. The DOJ also reportedly has three separate probes touching Nvidia, Megaspeed and Super Micro, with no sign of a criminal case against Nvidia or Huang.
4) Super Micro $SMCI fell 11.3% to $26.99. Manhattan prosecutors are reportedly examining whether entities tied to that woman helped move its servers to China; the company is reportedly not a defendant and says it is cooperating. Alibaba fell 6.8% in Hong Kong on reported fears that Chinese clouds renting Nvidia chips through Megaspeed could lose access.
5) Nebius $NBIS now expects 2026 revenue at the low end of its $3.0-3.4B range because delivery dates at several third-party colocation sites, including the remaining New Jersey tranches for Microsoft, moved into the first half of 2027. Its annual recurring revenue goal also slipped about two months, from $7-9B by December to above $7B for February; the company says the contracts remain in place and the delay is "not structural." Q3 revenue rose 571% year over year to $980.8M, including about $325M of non-recurring revenue, and the stock fell 16.8% to $128.64.
6) Nebius raised its 2026 capital spending plan to about $27B from a prior $20-25B range and sees $40-45B in 2027 against $12-13B of revenue, with pre-tax breakeven in Q4 2027. Prepayments covered more than 100% of capital spending tied to Q3 deals, up from 50-60% in Q2. The company expects prepayments plus asset-backed financing to cover 75-85% of 2027 capital spending.
7) Elsewhere in AI-linked stocks, AMD $AMD rose 5.9%, Broadcom $AVGO 5.5% and Alphabet $GOOGL 1.8%, while Micron $MU fell 1.6% and SanDisk $SNDK 4.1%. CoreWeave $CRWV fell 6.9% a day after a 24.7% gain.
8) Cisco $CSCO raised its fiscal 2027 outlook to revenue of $74.8-75.8B and non-GAAP EPS of $5.47-5.53, and lifted its expected AI infrastructure revenue from the largest cloud companies to $9B, more than double fiscal 2026. Fiscal Q1 revenue rose 24% year over year to $18.5B, with networking product revenue up 43%, and non-GAAP EPS rose 40% to $1.40. Shares closed up 1.2% at $102.01 and slipped 0.3% after hours.
9) Applied Materials $AMAT grew fiscal Q4 revenue 53% year over year to $10.41B and non-GAAP EPS 92% to $4.16, and the CEO expects its Semiconductor Systems business to grow more than 40% in calendar 2026. It guided fiscal Q1 revenue to $11.1B plus or minus $0.5B and non-GAAP EPS to $4.35 plus or minus $0.20, and the low end of that guidance was reportedly below expectations. Shares closed down 3.6% at $380.95 and rose 0.7% after hours.
10) The 10-year Treasury yield rose 10 basis points to 5.10%, and the $25B 30-year auction reportedly tailed, a sign of weak demand, in what was reportedly the third soft auction in a row. Futures reportedly price about 90% odds of a Fed rate hike at the Dec 8-9 meeting, which puts today's 8:30 AM ET producer price index (PPI) in focus.
1
172
11) Brent rose 3% Thursday to about $95.5 after Trump reportedly posted that the US does not need an Iran deal, and is flat overnight. Gold futures fell 2.9% to settle at $3,885.30, their lowest settle since September 2025. Bitcoin is near $68,800, down 3.6% over 24 hours and reportedly at its lowest since August; Strategy $MSTR fell 6.5%, and MSCI reportedly removes Strategy from its indexes effective Nov 30.
12) Modine $MOD rose 27% after hours to about $135. Bloomberg reports Samsung Electronics is in talks to buy the data-center cooling maker, with a deal possible in the coming weeks, though the talks could fall apart and Samsung could not confirm. Cerebras $CBRS rose 18% after hours after its results and a Microsoft deal.
13) Anthropic set an IPO price range of $70-78 in its SEC filing, under the ticker $ANT. Pricing is reportedly set for Nov 18 and trading for Nov 19, with the book reportedly already covered within the range.
14) Form 4 filings show open-market insider buying at six companies. At Hudson Pacific $HPP, a director bought about $680K and the CEO about $182K, and at Alnylam $ALNY two directors bought about $0.54M combined after insiders had been net sellers for ten straight quarters. The CEOs of Bloomin' Brands $BLMN and Flagstar $FLG each bought about $0.5M, the CFO of Boot Barn $BOOT bought about $271K in a first purchase in three years of data, and the founder and CEO of EquipmentShare $EQPT bought about $250K.
15) On Thursday, the S&P 500 fell 0.4% to 7,592 and the Russell 2000 fell 1.7%, with the VIX at 18.7. As of about 11:30 PM ET, S&P 500 futures are up 0.1% and Nasdaq 100 futures down 0.1%, after trading about 0.3% higher earlier in the Asian session. In Asia, Taiwan is up 1.4% and the Nikkei 0.9%, while the Hang Seng is down 0.9% and the Kospi 0.7%; USD/JPY is at 159.9.
Eyes on the open.
135
What moved overnight:
1) Nvidia $NVDA: The WSJ reported after Wednesday's close that the board is preparing to oust CEO Jensen Huang. Bloomberg reported the board is working with an outside firm on replacements and weighing an interim CEO, and Reuters reported it was meeting Wednesday to decide Huang's future. That would reverse the board's position from Sunday. That day Huang admitted to an affair with an executive at Megaspeed, one of Nvidia's large Southeast Asian customers and reportedly under US investigation over possible chip smuggling, and the board opened an independent investigation, saying it had "no reason to believe" national security or Nvidia secrets were compromised and that it "has confidence in Jensen." The New York Times said Wednesday that Huang also had a relationship with Nvidia's VP of healthcare, who reported to Huang. As of 11:45 PM ET there is no board decision, new company statement or named successor, with earnings reportedly due Nov 17. Shares rose 2.9% in the regular session and were down about 8.6% after hours.
2) CoreWeave $CRWV reported Q3 revenue of $3.661B, up from $1.365B a year ago, with a backlog of about $132.5B, and raised its 2026 guidance. Revenue is now guided to $13.0-13.3B and adjusted operating income to $1.275-1.375B, up 26% at the midpoint from the prior range. Capex is now $37-39B versus $35-39B before. The guidance came with a funding plan: CoreWeave expects about $9B of customer prepayments and deposits over the next three months and closed a $2.6B loan facility designed for shorter-duration customer contracts. Reportedly, customer prepayments and equipment-backed loans eased market fears that the AI build-out could not be funded with yields near 5%. Interest expense rose to $846M from $310M a year ago, the net loss was $709M, and the company also raised about $4.2B in convertible notes and set up an at-the-market program for up to 35M shares. Shares rose 24.7% Wednesday and were down 6.4% after hours.
3) Chip and AI infrastructure stocks rallied Wednesday. The chip ETF $SMH rose 4.8%, SanDisk $SNDK 13.7%, Micron $MU 11.9%, Oracle $ORCL 8.8%, AMD $AMD 7.3% and Broadcom $AVGO 4.0%, while the S&P 500 gained 1.3% and the VIX fell 10% to 17.5. The big platforms went the other way, with Microsoft $MSFT down 2.3%, Meta $META 2.0% and Amazon $AMZN 1.7%.
4) Chip stocks gave back part of those gains after hours, with $SMH down 2.7% and Micron down 2.8%, while AMD added another 4.3%. As of 11:45 PM ET, Nasdaq 100 futures are down 0.9% and S&P 500 futures are down 0.3%. In Asia, the Nikkei and Kospi gave up opening gains of about 0.8-0.9% to trade flat, while Taiwan is down 1.1% and the Hang Seng 0.9%. Gold futures are down 0.5% at $3,980, below $4,000, Brent is down 1.6% at $91.29, the dollar index is at 103.0 and USD/JPY at 159.7.
5) Fed Governor Bowman said in a speech that "the benefit of additional policy tightening has to be carefully weighed against its costs for interest-rate-sensitive sectors" and that "monetary policy is not on a preset course." Governor Waller and the Dallas Fed's Logan are reportedly ready to hike ahead of the Dec 8-9 meeting, and producer prices are due Friday. The 10-year Treasury yield is about 5.00% after the US bond market closed Wednesday for Veterans Day, and the Treasury auctions $25B of 30-year bonds at 1:00 PM ET.
6) Anthropic set a $70-78 per share range for its IPO in an SEC filing and plans to list on Nasdaq as ANT. Bloomberg reports the order book is already covered several times, meaning orders exceed the shares on offer. Pricing is reportedly set for Nov 18, with first trade on Nov 19.
7) MSCI will reportedly drop Strategy $MSTR from its indexes after the Nov 30 close under a new rule for "non-operating" companies, which would require index funds tracking them to sell the stock. Shares fell 2.6% after hours.
1
1
317
8) Flowco $FLOC President and CEO Joseph Edwards bought 20,000 shares on Nov 5 at an average $19.49, about $390K, according to a Form 4, and holds 315,920 shares directly after the purchase. The buy follows roughly $197M of insider sales across Q4 2025 and Q1 2026. Shares closed Wednesday at $20.89.
9) Nebius $NBIS reports before the open after rising 15.4% Wednesday and slipping 4.0% after hours. Cisco $CSCO and Applied Materials $AMAT report after the close.
Eyes on the open.
1
25
What moved overnight:
1) October CPI +0.4% m/m vs +0.3% expected, core +0.3% vs +0.2%. The 10-year yield jumped 0.12 point to 4.98%. S&P 500 -0.4% to 7,521, Nasdaq -0.7%, gold miners $GDX -5.4%.
2) Before the print, Fed Governor Waller said he backs a 0.25 point December hike regardless, and that 0.5 should be considered if core ran about 0.3% or more. It did, so a bigger hike is now a live option for Dec 8-9.
3) $NVDA -5.5% to $168.89 while the chip index slipped only 0.8%, about -10% in two days. The selling stayed with Nvidia itself: $AVGO +3.9%, $AMD +1.3%.
4) Anthropic filed its IPO range: 825M shares at $70-78, up to $64.35B at the top end. It will list on Nasdaq as ANT.
5) CoreWeave $CRWV beat after the close: Q3 revenue $3.66B vs $3.55B expected, 2026 guide raised to $13.0-13.3B, +7.9% after hours. Interest expense $846M, up from $310M. In the session $IREN -7.8%, $GEV -3.9%.
6) TSMC $TSM posted record October revenue of NT$586.9B, +59.7% year over year. By midday Wednesday Taiwan +2.4%, Kospi +2.2%, Nikkei +1.2%, Hang Seng -0.8%.
7) Six Flags $FUN director Rehan Jaffer bought $14.9M of stock, lifting his stake 22.8%. Prospect Capital $PSEC CEO John Barry added $1.73M, Magnachip $MX director Cristiano Amoruso $1.37M.
8) S&P futures +0.6%, Nasdaq futures +1.4%, Brent $92.36. Applied Materials and Cisco report Thursday, PPI lands Friday.
Eyes on the open.
1
148
KD87 retweeted

Again, people have this unrealistic fetish for closing exact tops, or buying exact bottoms. They imagine the pro trader who never loses and times everything perfectly.
Reality is far from it.
Trading is a game of averages.
If my average purchase price is lower, and my average sell is higher I will out-compound you.
Timing the exact bottom is a fools errand, shorting is for risk management, not for PnL.
You short and close in profit so you have more cash on days like today. Would I have loved to be short into it? Sure, it would have been an extra +7% or so on our book. That doesn't matter as much as NOT LOSING money, managing your risk and preserving optionality. The sooner you understand this, the more profitable you'll become.

We've decided to close nearly all of our equity shorts into last nights emotional selling. One of our most profitable months ever. Thank you to our counterparties on those trades.
While the next year looks challenging for equity markets, I don't think it continues to make sense to be directionally short.
While sitting nearly 50% cash, we continue to hold large HYPE and Bitcoin positions.
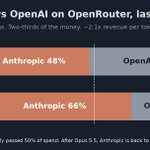
Anthropic vs OpenAI on OpenRouter, last week:
Tokens: 48% vs 52%
Spend: 66% vs 34%
Anthropic earns ~2.1x more per token.
In early Sept OpenAI briefly passed 50% of spend. After Opus 5.5, Anthropic is back to two-thirds.
Tokens aren't revenue. Pricing power is.
Data: @PeterJ_Walker / OpenRouter

2
63
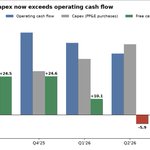
Q3 earnings settled one question: Big Tech's AI capex is no longer paid out of operating cash.
Capex as % of operating cash flow:
Amazon 125% (TTM)
Alphabet 121%
Meta 106%
Microsoft 68%
Apple ~11% (FY25)
Three of four hyperscalers now borrow to build. Where the debt shows up

1
1
55
Off the balance sheet, the chip vendor becomes the guarantor.
Anthropic: a $63B SPV buys Broadcom chips and leases them to the lab. ~$43.5B is first-lien, and Broadcom gives lenders residual value support. Before that: a $35B deal with a Broadcom backstop of up to $29B.
Moody's: risk rises if these deals stack up fast.
1
14
October, sorted by layer of the AI trade:
Defensives (XLP, XLU): +10% to +11%
Apple +3.5%, Microsoft +1.8%
Hyperscalers: −4% to −19%
Accelerators: −7% to −17%
Memory: −17% to −34%
PC/edge: −10% to −45%
Neoclouds: −35% to −37%
Nvidia (−10%) held up better than the companies that buy its chips with borrowed money.

35
Next week's AI calendar:
Mon: Apple, Palantir
Tue: AMD, Arista, Astera Labs (+ US midterms)
Wed: Arm, Qualcomm, Coherent
Thu: Lumentum, Cloudflare
Fri: October jobs report
Apple goes in +3.5% for October, AMD −17.5%. Same week, opposite questions: who gets paid for not spending vs who gets paid for selling.
49
FCC transceiver ban headline: "Innolight out."
The detail that matters: the carve-out MS reportedly heard in DC lets China-built 3.2T in if 65%+ of BOM is from US firms. Marvell DSP + LITE/COHR lasers gets close.
Real loser: Chinese lasers. Winner: US lasers, not assemblers.
76
