

Managing Partner, BluBird Capital Engineer - xApple | xQualcomm | xIntel | Startup exits, Tennis player🎾, JohnsHopkins alumni
San Diego, CA
Joined January 2015
- Tweets12.7K
- Following320
- Followers14.7K
- Likes25.2K






Pinned Tweet
My interview on FOX BUSINESS with Charles Payne live.
@cvpayne talking CXMT Memory($MU) and few other picks.
Chinese chipmaker CXMT soars after blockbuster IPO | video.foxbusiness.com/v/6402…

The Week Ahead:
$APPL is up 27% this year by doing the one thing nobody else would: not spending on AI capex. That’s why it’s the refuge.The refuge isn’t cheap. Apple trades at 37x forward earnings, a record. The discipline is already priced in. Ternus does his first earnings call tomorrow. I will be hearing the call live and sharing my thoughts.
$GOOGL Google Search went from 19% growth to 12% in two quarters. Cloud went the way other to 103% YoY growth.I try to infer Google long term revenue mix.
$INTC - The Problem Child
I’m holding Intel. But foundries don’t turn around overnight. Break-even in 2027 isn’t the finish line. External wafer orders in 2028 and 2029 ?
MIDTERMS: Gridlock is not a rally It removes the risk of policy surprises and guarantees next two years of budget fights. Crude still high.
Bottom Line: The AI buildout isn’t over. The market is clearing up some fluff.

My two cents for PE Sponsor’s
Private Equity can Blow up in this era of high rates and longer exit window’s and their CEOs are often the problem
I was reading this WSJ article on PE CEOs. Public CEO turnover is down. Private equity CEO turnover is up. And a lot of it is because of higher rates.
Higher rates mean a longer time to exit. PEs are usually leveraged, and nobody is going to leverage at a higher interest rate .So you wait.
Now the part a lot of people miss. A lot of these PE CEOs do not deserve to be in their jobs. I know a few specifically, and I have experienced it firsthand.
These CEOs got there by greasing the wheels. Friends got them jobs. Some went from a consulting firm straight to CEO. Never built anything. Had a string of failures in the past, and still got hired.
Now that rates are stuck, they are screwed.
PE sponsors have to look at their individual companies. They should question these CEOs and their past and see if a change is needed. Because if your revenues are flat, your EBITDA is negative, and you're looking at another four years of paying interest on that debt, you need to change the CEO.

$GOOGL I had sometime to go through Google search numbers again. First let me tell you what WS analysts think and what I think.
Google Search grew 12% last quarter. Two quarters ago it was growing 19%. Revenue was flat from Q2 to Q3. The Street is calling it a pause.
KeyBanc called it an "air pocket" and says the headwinds are transitory. Citi says AI Mode monetization is just beginning. Deutsche Bank compares it to Meta's Reels, which pulled engagement from the core feed before it paid off.
I see the logic, and query growth is the strongest in five years. But the problem is harder.
Every AI answer that resolves a question replaces search ads that already work. The AI Mode ad sits at the bottom of the answer, not at the top of the page, and only went multi-turn this week.
Each AI query also burns far more compute than ten blue links. So Google gets lower revenue per query and higher cost per query, while OpenAI sells ads against the same intent. Reels had none of those problems.
Does Google place ads all over its AI mode. Will users be deterred? How effectively they monetize AI mode is the solution to their search growth.
Then there is the elephant CAPEX.
My view is monetization will come. The open question is whether it comes fast enough to fund $200 billion a year in capex.
From the large number of Chinese language reposts of this, am I to assume Chinese investors like $INTC over $TSM?

An a former $INTC Intel engineer I wrote my thoughts on the company back in December, 2024.
I advocated investors against Intel.
Have my views changed?
I never owned Intel. Not when the stock ran. I worked there. I knew the failures were never about demand. They were about management and execution.
Lately I bought a small number of 2028 calls. I talked to former colleagues. Under Lip-Bu Tan, the company was focused on profits. The old, inefficient guard was being cleared out. The fab was doing better. 18A yields were improving.
I've always been skeptical about yields. Not just at Intel, but at any US fab, given how much talent we've lost over the years. That skepticism is starting to ease.
Yesterday's call was rough. Supply is the ceiling. Substrates are short. A tragic accident shut Fab 28. The stock fell 21%.
After a lot of angst, I'm holding. Here's why.
Intel is two very different businesses. One designs CPUs for servers and PCs. The other is a fab that drains capex. Demand isn't the problem for either one. Execution is.
Intel still shows wear and tear. But it has a better CEO than it has had in a decade, and the US government owns a stake. It's more able to fix its mistakes today than at any point I've watched.Demand is robust.
And there's the bigger picture. Intel is the only leading-edge US fab, and the only one showing real signs of change.
China is ahead in many ways. Depending on Taiwan is not a long-term plan. Trillions of dollars of US tech run on chips made on an island Beijing claims as part of One China.
Intel can't fail.
So I'll give it a chance. Call me foolish.
An a former $INTC Intel engineer I wrote my thoughts on the company back in December, 2024.
I advocated investors against Intel.
Have my views changed?
I never owned Intel. Not when the stock ran. I worked there. I knew the failures were never about demand. They were about management and execution.
Lately I bought a small number of 2028 calls. I talked to former colleagues. Under Lip-Bu Tan, the company was focused on profits. The old, inefficient guard was being cleared out. The fab was doing better. 18A yields were improving.
I've always been skeptical about yields. Not just at Intel, but at any US fab, given how much talent we've lost over the years. That skepticism is starting to ease.
Yesterday's call was rough. Supply is the ceiling. Substrates are short. A tragic accident shut Fab 28. The stock fell 21%.
After a lot of angst, I'm holding. Here's why.
Intel is two very different businesses. One designs CPUs for servers and PCs. The other is a fab that drains capex. Demand isn't the problem for either one. Execution is.
Intel still shows wear and tear. But it has a better CEO than it has had in a decade, and the US government owns a stake. It's more able to fix its mistakes today than at any point I've watched.Demand is robust.
And there's the bigger picture. Intel is the only leading-edge US fab, and the only one showing real signs of change.
China is ahead in many ways. Depending on Taiwan is not a long-term plan. Trillions of dollars of US tech run on chips made on an island Beijing claims as part of One China.
Intel can't fail.
So I'll give it a chance. Call me foolish.
$INTC I worked at Intel during transition of Brian Krzanich to its then CFO Bob Swan. Swan took care of closing loss making divisions but did little for innovation at Intel. Between inept management, work culture, lack of competitive moat, it was a broken company.
In 2019 Intels revenue hit 71B and FCF ~14B. It squandered that loot into hiring more inefficient leaders like Murthy from $QCOM.
Gelsinger from VMWare was a good leader but inherited a company so behind in CPU processor architecture, unable to keep up in the AI compute race.
They had good engineers, sufficient capital but lack of vision, in effective management, paying up for mediocre tech at high valuations from MobilEye to Altera to some AI outfits drained it’s resources
Except Hock Tan, few non tech CEOs have successfully run big tech.
I hope they will find a dynamic CEO to lead them, there’s a market out there in the AI compute race.
They can learn from Hock Tan and aggregate good tech into a tech holding company with focus on vertical value chain like enterprise software.
Oh and definitely spin out the FAB.
Two cents from an former Intel engineer
$INTC Intel Deep Dive: The Server Story Is Real. The Guide not Pretty.
Intel beat Q3 and still fell 21% after hours. Data center revenue grew 78%, the best in 15 years. DCAI now earns more than the PC business. 18A costs are down 40% since Q1.
Q4 came in $1.8B below the Street. A tragic accident at Fab 28 in Israel cost $300M. PCs are in freefall because AI is eating the world’s memory supply. And 2027 won’t be a free cash flow year.
I break down the numbers, the bull and bear case, what the stock prices in, and the five catalysts I’m watching before I buy.
🤖 Made with AI


Oh $AAPL How the tables have turned
THEN
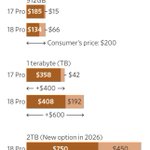
“Apple bullied flash makers into opening their books so it could monitor sales, making sure no one else got a better deal.”
NOW
Flash memory suppliers and their sales teams privately expressed their glee at Apple’s comeuppance during chitchat at the industry’s largest conference this summer in Santa Clara, Calif. AI deals have given Kioxia sales executives and other flash suppliers new leverage to charge Apple higher prices. -WSJ

Sundar needs to announce a big cost reduction roadmap similar to $MSFT.
Take out 30% headcount.
I got an offer at Google in late 2022. They have plenty of slack at the company. They can do a 1/5 in every group and still run operations smoothly.
$GOOGL report ready!
Alphabet dropped about 10% after hours. The headline said EPS of $2.12 against a $3.00 estimate. Most of that gap was an $11 billion mark-to-market loss on Alphabet's SpaceX stake.
Strip that out and the quarter still missed. Just by less. Here's how I read the print,and why the supply chain matters more than the stock tonight.
The real problem isn't SpaceX. It's the bill for the AI build. Capex hit $51 billion in a single quarter. Free cash flow went negative again. Buybacks went to zero. The one thing paying for it: Cloud, up 103%.

$GOOGL report ready!
Alphabet dropped about 10% after hours. The headline said EPS of $2.12 against a $3.00 estimate. Most of that gap was an $11 billion mark-to-market loss on Alphabet's SpaceX stake.
Strip that out and the quarter still missed. Just by less. Here's how I read the print,and why the supply chain matters more than the stock tonight.
The real problem isn't SpaceX. It's the bill for the AI build. Capex hit $51 billion in a single quarter. Free cash flow went negative again. Buybacks went to zero. The one thing paying for it: Cloud, up 103%.
Agree $AAOI “can” go nuts if this buyout news is legit. You don’t have to be the best InP laser manufacturer. You just have to be the last 2 left along w $COHR.
US has to find a domestic InP source and wean off China.
$LITE acquisition is the start of that journey.

$GOOG capex for full year reiterated. $MSFT likely does the same even though both q3 #s were soft. Prob just waiting for Rubin and turning down more blackwell shipments in q3.
$MRVL buying $LITE rumor-wow. Been nibbling LITE below 900.
If MRVL really pays up over 100b for LITE, $AAOI CAN go to 200 within a quarter or two IMO. Shows just how valuable having laser capacity is.
$CBRS hit piece-gift if msft capex reitertated(likely)-VICR would've fell hard if this hit piece was real-it held up like the champ it is. Own both, but more VICR, way more VICR, like 30x more.
Fun day.
I said was buying $MU at $800 and I did and today it’s at $980.
Watch the clip towards end, no ads.
youtu.be/unzjRYf0fM8?is=PY7J…