



Baddieinvestor retweeted

我翻完梁文锋26岁写的微博才明白DeepSeek的成功,跟技术路线半毛钱关系都没有。
梁文锋26岁那年,一个人开着菲亚特进了西藏阿里无人区。
深入400公里,
被困了一周,
人走出来了,
车永远留在了那里。
12年后他做了DeepSeek,
你要是读过这个故事,就一点都不意外。
2011年底,他开一辆破菲亚特去西藏,
同行的人到了拉萨玩完就飞回去了,
他没回。
一个人继续往西,羊卓雍措,珠峰,希夏邦马,一直扎进阿里无人区400公里。
用的是入门级尼康D50,套头,
但他能等大半天就为了一束光,
拍出来的照片像专业摄影师的。
配文写的是"风萧萧兮易水寒",写的是"古道西风瘦马",写的是"一骑走天下"。
最后一条微博:
被困无人区一个星期,所幸我出来了。但我的菲亚特没有出来。它永远地留在了那片漫无边际的高山草原。That's the END。
就这么个事,
我们回头看DeepSeek,全是同一个人的同一个打法。
别人到拉萨就回去了,
他一个人再往里走400公里。
像不像现在?
大家都在做应用、做商业化、做能快速变现的事情,
他一个人往里走,做基础模型,做AGI,很长时间都不融资,不社交,不出来参加各种大会。
入门级相机,但等半天光线,拍到最好,
像不像DeepSeek?
不堆资源,不烧钱,但把效率做到极致,用别人十分之一的成本做出匹敌的东西。
车扔在无人区了,人走出来了,写一句That's the END。
像不像他的风格?
敢赌,敢输,输了认,然后继续走。
开源就开源,被制裁就被制裁,模型放出去就放出去,车没了但人出来了,下一趟再来。
所有人都在分析DeepSeek的技术路线、成本结构、国运加持,
但你看看这个人26岁干的事,答案全在那。
一个敢独自把车开进无人区400公里的人,他做公司就不会跟在别人后面。
一个把车扔在高原走出来还能写That's the END的人,他不会在乎短期股价和融资新闻。
一个用入门相机等半天光线的人,他做模型就会把每一分算力都榨干。
所以这些都不是什么商业策略,
这就是一个人的性格,
DeepSeek不是一份商业计划书的结果,
是一个人的本性,在12年后,自然长出来的东西。
那个在无人区里走了一周的年轻人,和那个把全球AI行业搅翻天的人,是同一个人,一直以来都是。


DeepSeek V4这波绝对称得上DeepSeek 2.0时刻了,
难怪大家都叫梁文峰梁圣,
还有说梁圣的恩情还不完,
以及最近有DeepSeek斩杀线的说法,
之前还有点不太理解,现在想想好像有点意思,
完成同样一个完整的Agent任务,
DeepSeek比Anthropic最好的Fable 5要便宜105倍🤯。。。
注意兄弟们,不是token单价便宜105倍,
是真刀真枪跑完一整个任务,
从开始到结束,所有轮次所有工具调用加起来,
DeepSeek花3美分,
Fable 5花3.15美元,
damn,太离谱了!
上一次是2025年初,它证明开源模型能追平闭源,
这一次它证明,可用级别的智能,
成本已经低到几乎可以忽略不计。
很多人没意识到105倍这个数字意味着什么,
这不是简单的打个折,或者说性能优化了20%,
就是一个数量级的差异,
大白话就是,你跑一个任务花3块钱,别人花3分钱的差异。
以前你跑Agent,
每多一轮调用都在心疼token,
要做缓存,要剪枝,要想尽办法省调用,
现在你完全可以让Agent随便跑,
跑十轮二十轮,
成本还不到以前的零头。
我觉得这样肯定会直接催生一整代以前根本不可能存在的产品,
那些需要大规模、长程、多轮Agent调用的应用,
以前算下来ROI根本不成立,
现在突然就全部成立了。
Cline那个开源编码Agent为什么第一个跳出来喊,
因为他们最清楚,
用户之前不敢大规模跑自动编码,
根本不是能力不够,是账单太吓人,
现在这个枷锁直接被砸碎了。
当然差距还是存在的,
顶尖模型在最难的任务上还是更强,
但日常80%的工作,
3美分和3美元做出来的东西,
大多数人根本分不出区别。
接下来会发生什么,
闭源厂商会被迫继续降价,
开发者会重新分层使用模型,
高频日常任务全用Flash级别的模型,
只有最关键的决策才用最贵的模型。
但最深远的影响其实是,
智能本身正在变成大宗商品,
就像电力,就像带宽,
当它便宜到一定程度,
就没有人再去讨论它的价格了,
大家只会讨论用它来造什么。
而这一天,可能比我们所有人预想的都要来得快。


Baddieinvestor retweeted

看到一句话,
人类往往高估了一年内的变化,
同时也低估了10年后的变化。
最近亏到迷茫和自我怀疑,
存储真是盈亏同源的一波,
今年赚钱是因为存储,
亏钱还是因为存储。
巴菲特真是太牛逼,
他能在资本市场活这么久,肉体也能活这么久,跟他没杠杆,一直没满仓的操作风格肯定多少有关系,像我们普通人可能为了暴富上杠杆焦虑得睡不着觉,或者富了以后一直带杠杆亏盈都焦虑。
看他公司股价历史也无数次腰斩过,
但过几年还是能不断新高。
亏成这样,事已至此,
我在想以后我应该以什么样心态炒股票,
我应该以什么样眼光再看待未来,
去年的时候跟朋友一起抄底过300左右联合健康,拿了小半年毫无反应跑了,最近每次想到巴菲特的时候都想起来他在任时候最后也抄了联合健康,再去看的时候已经400多。什么样的心态才能做到他这种耐心愿意等待非常久获得收益。
对我们散户青春宝贵,
每次大幅回撤我都有一种时间的蹉跎感,
即使以后涨回来,除了劫后余生的轻松,
我总感觉有一部分的我在承受亏损的过程中死了,少了少年气。
但巴菲特面对回撤暴跌可能是真的兴奋,他的闲置仓位太多了全是货币资金,可能闲钱足够多就是他耐心和长寿的主因。

Baddieinvestor retweeted

Feels bad, -49.4% drawdown this month after the recent crash.
My portfolio is mainly AI chokepoints and bottlenecks.
In the memory, photonics, robotics, and upstream semis, (on margin) which all tend to be higher beta than others. But reduced leverage recently from the crash.
I see a lot of people making fun of the drop or AI names, saying it’s obvious that:
- “AI is a bubble”
- “memory/kospi is a bubble”
- “photonics is a bubble”
- “humanoids won’t get anywhere”
- “neoclouds will get replaced by hyperscalers like Meta”
And a bunch of retail + bots saying “sell everything, it’s never going to recover”.
But I have conviction that all these themes are backed by structural revenue growth or technological shifts.
And I’ve had similar drawdowns back when there admin threatened global tariffs, before markets pulled off a recovery.
I personally have a longer horizon + higher tolerance for volatility than others, to see how this plays out.
Especially considering a lot of retail view things on a week to week basis: no, my thesis isn’t wrong yet if I project revenue inflection in H2 2027 and it’s 2026 now.
Anyway, feels bad short term just wanted to share anyway for transparency.


Agreed! It’s nice to remember your thesis during a market crash.
From my own personal thesis, if $AAOI hits $1.4B quarterly revenue start of Q3 2027. Which is annualized $5.6B off a $8B MC.
Is it “over” for the company if that revenue ramp hasn’t even shown up in the quarterly earnings… when it’s 2026?
Same applies to my CPO sector exposure like $SIVE, an architecture shift led by $NVDA.
If scale out volume ramps from H2 2026 into 2027, and scale up heavily volume ramps into 2028.
Is it “over” that $0 -> $91B TAM expansion (per GS) hasn’t even hit yet?
With robotics like Agility, is it over in 2026 if the listing hasn’t even happened yet and humanoids haven’t ramped?
I personally think current market conditions are a reflection of liquidity and leverage, not individual fundamentals.
It’s brutal for everyone to see KOSPI, TW, Nikkei, and AI, space, robotics sector stocks crash recently.
Especially when there’s a lot of irrational behavior stemming from those leverage.
In the end, we can’t tell you what stocks to buy, what timeframe you should sell, how to size your positions, or what you should do.
Only share personal thoughts or research and track if they get validated over time.
So it’s extremely important to build your own thesis, since everyone has unique risk tolerance or investing timeframes.
And that usually leads to having higher conviction during crashes.
Baddieinvestor retweeted
Risk/reward seems attractive again.
Lots of cheap stocks with durable competitive advantages that are going to crush numbers for the next 6-12 quarters.
Time will tell!


Baddieinvestor retweeted
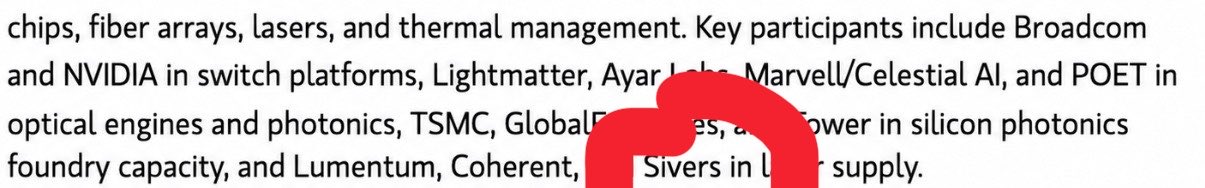
Morgan Stanley note on CPO today. Key participants include:
- $SIVE, $COHR, and $LITE in laser supply
- Broadcom and Nvidia in switch platforms
- Lightmatter, Ayar Labs, Marvell/Celestial, and POET in optical engines and photonics,
- $TSM, $GFS, and $TSEM in silicon photonics foundry capacity
I’ve covered all of these before, like Tower Semi.
But I’m especially happy that Morgan Stanley validated my research that $SIVE is one of the critical global players in CPO.
A small $1.5B laser company next to your two leading $60B+ companies…
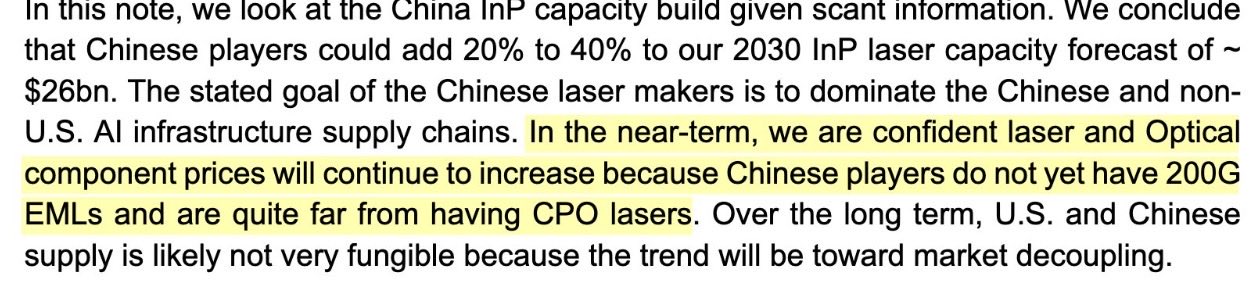
If you also synthesize Rosenblatt Securities recent note that China laser suppliers were quite far from having CPO lasers.
This kinda magnifies importance of the three Western leaders of that laser chokepoint.
Baddieinvestor retweeted

HSBC最新把Intel的目标价从100美元直接上调到200美元
这是目前华尔街最激进的目标价之一。我觉得接下来可以多一点耐心,把目光放到今年年底和明年,不要每天盯着股价波动。
最近几份机构报告都在关注同一件事:Intel Foundry的进展明显加快。18A良率问题基本解决,18A-P已经开始风险试产,14A研发也在持续推进。随着台积电先进制程和CoWoS产能持续紧张,越来越多客户开始考虑第二供应商,Intel的EMIB先进封装也因此获得更多关注。目前公开信息显示,Terafab(SpaceX、Tesla和xAI联合项目)、Google、Apple、Amazon、Microsoft都与Intel Foundry有不同程度的合作或项目推进,NVIDIA也仍在评估Intel的先进封装方案。
另外,Intel最近还上调了Core Ultra处理器的官方建议售价,侧面反映出公司对产品竞争力和需求的信心有所提升。接下来真正值得关注的还是财报,看看管理层会不会披露更多关于Foundry、18A、14A以及外部客户的最新进展。
根据之前公开披露的信息,Pelosi近期也买入了2027年3月到期的Intel长期看涨期权(LEAP Call)。
重点关注的还是公司未来几个季度业务兑现的情况,我看好未来几个季度Intel的财报。
Baddieinvestor retweeted
Photonics is backed by actual revenue numbers and it's an architectural shift championed by $NVDA.
Quantum barely has any revenue.
$LITE is completely sold out for the next 2 years (per $POET AGM) likely starting into 2029. Lumentum is so strained that they buy CW lasers off competitors (earnings transcript)
$COHR is bottlenecked, so they buy EML off Lumentum.
Then, $AAOI is coming in with Made-in-America independent CW capacity, are projecting $1.4B/quarterly revenue ending H1 2027 of a stupid $9.3B MC today.
So all the CW capacity from independent players who have it now like $AAOI or $SIVE are likely to become scarce resources.
Many other hyperscalers have already started LTA discussions (per Trendforce). And players like $AMD are currently talking with players such as $AAOI (Rosenblatt channel checks).
Thematically, next 2 years is 9x TAM to US$154B per GS reports, especially with 16x/45x dollar content increase in scale out/scale up.
Then there's the overall thematic AI drop from $META, which is widely misunderstood because people conflate what "excess capacity" means. And as UBS mentioned, Meta planning a cloud offering is NOT NEW NEWS.
Bloomberg just has a tendency to publish information that causes doom drops across the semi sector like Nvidia export controls a few months back.
But I'm familiar with what I'm holding so I'm confident in these numbers playing out.
Especially when all the major players are sold out, the fundamentals catch up eventually.


Let’s goooo
$SIVE: "Intent to complete the [NASDAQ] listing process over the next few quarters"
This statement was largely missed by many screeners.
Very material improvement from evaluation, to formal confirmation of timelines.

Baddieinvestor retweeted
I told you making the robots look hot might be a bottleneck:
Today, UBTech has now announced its first full-size hyper realistic humanoid robot girlfriend.
For adults only to purchase for only ~$145,717.90.
-"The U1 series emphasizes attractive appearance and is only available for adults to purchase."
- "It Can Imitate Most Human Movements and Expressions, and Also Has Long-Term Memory"
- "U1’s surface uses bionic materials and a gel structure to simulate skin texture, elasticity, and a warm touch."
UBTECH founder, chairman, and CEO Zhou Jian said on stage that just before going up, he learned that orders had exceeded 11,000 units.
Half an hour later, UBtech said the number had been updated to more than 13,361 units.
Demand for attractive robots is uncomfortably high.


I wonder if humanoids is going to spark a new bottleneck/industry for robot cosmetics.
Like a skin bottleneck. Or Aespa KPOP robot makeover as a service.
So if $TSLA Optimus makes tens of millions of humanoids:
Who’s going to make them all look hot?
Baddieinvestor retweeted
Congrats to $SIVE, they have now raised an upside round of 700m SEK from institutional investors.
The round was “Multiple Times Oversubscribed” and slightly upsided.
Validating immense institutional demand around current market prices.
This raise was specifically for "expanding manufacturing capacity for InP lasers and optical amplifiers" (volume ramping with fab-light model).
Hinting Sivers has reached the inflection point for scale.
The round was at 57 SEK (current prices are 63 SEK), which I’m personally very happy about as it’s around current market prices, which typically sets a floor.
Instituional money has now de-risked the balance sheet, and funded Sivers transition to HVM.


Great news with a Direct share issue that was oversubscribed multiple time.
What started as a planned SEK 600M (+$61m) raise was upsized to SEK 700M ($73m) thanks to strong institutional investor demand. That's a clear vote of confidence in $SIVE and the ramping within AI photonics, SATCOM and defense.
SEK 700M is roughly US$73M in fresh capital, providing even greater financial flexibility to accelerate execution and scale the business.
Strong demand. Strong balance sheet. Exciting times ahead.
Great work by the Sivers team! Congratulations!
$SIVE #AI #Photonics
sivers-semiconductors.com/pr…


Baddieinvestor retweeted
For robotics companies, I have a favorable view on Unitree and Agility Robotics, two humanoid players.
And I have largest concentration in Agility Robotics, since I personally prefer US humanoid players.
For upstream component exposure, I currently own:
- Harmonic Drive (6324) given high content BOM on things like harmonic reduction gear.
- Vishay Precision for sensors and a possible candidate for Telsa Optimus.
LeaderDrive (688017) and Schaeffler I have favorable views on but don't own personally.
Many of the other AI DC players, I have indirect exposure to robotics like memory.
Don't recommend anyone to copy, just sharing personal positions/thoughts.
Humanoid sector is large, and as seen with Goldman Sachs report that "Korean companies will command a 30% direct and indirect share of global humanoid robot production".
Lot of players out there globally. This was an older report but just linking it again since you see all of them pop up in GS institutional reports + what they cover.
Agility Robotics is my personal favorite as of now.


Baddieinvestor retweeted
So fun.
I watched this talk today lol
Personally, I love $GLW


GlobalFoundries and Corning jointly demonstrated an optical interconnect solution that combines a silicon photonics (SiPh) chip with a detachable GLASSBRIDGE™ connector. For the first time, they achieved a fully detachable GLASSBRIDGE™ connector capable of handling up to 280 mW of optical power.
The optical interface integrates GF’s silicon photonics platform, featuring SiN spot-size converters (SSCs) and a V-groove edge-coupling structure, with Corning’s GLASSBRIDGE™ connector technology, which utilizes low-loss ion-exchanged glass waveguides. The GF PIC expands the optical mode to match the 9 µm mode field diameter of the glass waveguide, while Corning’s waveguide routes the light to a connector interface compatible with standard MT ferrule connectors.

Baddieinvestor retweeted
Just some notes on $POET AGM and read through on optical markets:
- "The top three laser suppliers control 68% of the market, and they’re completely sold out for the next two years"
$LITE CEO said into 2028, so POET implicitly confirms laser shortage is going into 2029 now.
- NRE with a new customer, building on POET’s interposer for high-power external light source.
This is high confidence $SIVE as laser supplier given the Sept 29, 2025 PR on ELS, and new customer qualification would be material for revenue if it goes into volume ramp.
- Poet expects Lumilens commercial agreement to scale to over $500 million over the next 5 years.
Lumilens claimed a top-3 hyperscaler was their initial customer (Linkedin OSINT)
- $830M cash on hand on balance sheet (this is more for Poet fundamentals).
- "The entire optical components industry today is facing a severe shortage of critical components."
Reaffirming what we know already regarding optical bottlenecks.
- "Production ramp in the second half of 2026 this year."
Just production timelines H2.
In terms of $POET volumes:
- existing capacity around 1 million optical engines per year
- projected demand exiting 2027 around 1 million optical engines per month
- roughly 10x capacity expansion
I don't own Poet, but if management delivers on these projections it directionally looks very positive.
However something to note is that unlike other suppliers that have named hyperscaler customers to to back up capacity revenues like $AAOI: $POET seems more questionable.
But this does look like a very positive outlook for $POET if they match projections.

Baddieinvestor retweeted

"The Laser Bottleneck: Mesh, Marvell, and the CW DFB Supply Chain That’s About to Get Very Expensive" by nexusfinance
open.substack.com/pub/nexusf…
