

Seasoned quant researcher.
New York, NY
Joined July 2015
- Tweets237
- Following337
- Followers2.6K
- Likes571



Coastal Quant retweeted

As observed through June, July, and August of 26' while the index itself was relatively stable the dispersion of returns of stocks within the index was quite high. I've seen all manner of explanations for this but the tldr is that this is precisely where having a quality factor model is useful! If you were to only look at the index performance as your indicator of risk for the market you would have been quite surprised by the performance of your portfolio if you had any meaningful style factor tilts during this time period! This is why index or index future hedging on its own is not a sufficient tool for controlling the risk in a portfolio! While many Tiger-style L/S managers stick to this index-only approach the below observation is precisely why it is no longer able to be relied upon on its own when constructing portfolios.


VCs and terrible public market takes, name a more iconic duo

AI stocks will drop 10%+ on Monday morning
Brace for impact folks
@DarioAmodei just unwound the AI trade with a blog post

Coastal Quant retweeted

If you hold a levered portfolio of ~7 stocks for a long time, chances are that you will look like a genius or like an idiot, whichever comes first. Kelly, Information Coefficient, etc. are not useless concepts.
Many such cases these days.
Coastal Quant retweeted

@bobaissoup and I launched a project today called caratrank.com/
find the lowest price on any diamond across 20+ retailers. We’re the only site where this is possible!
you can also search by certificate number (never been possible before) and style.

Quick demonstration of weak signals that independent don't make money crossing the spread can combine to be profitable H/T @0xfdf
Each signal is on a cross section of 100 stocks, IC 0.01, stock vol is 1%, bid/ask spread is 2%. Averaging features increases IC, overcoming spread


For the quant finance crowd: let's say you have a signal with high IC forecasting 1-day returns and high in-sample Sharpe ignoring costs. However bid/ask spreads are large so simulating a strategy including fees leads to very negative performance. How do you decide whether to:
- Switch to maker instead of taker orders
- Subset your signal to only tail positions
- Slow down your signal / slow down your trading
- Find longer term signals and use this faster one as an excution overlay
- ... something else?
Coastal Quant retweeted
today, i've launched an Open-Source project called SecurePrompt that sanitizes LLM input and output
it covers most instances of prompt injection in input and leakages of sensitive data/API keys in output
launch article here: nitter.cf/thejaikannan/status/20…
secureprompt.dev


Coastal Quant retweeted
I'm hiring for a 4-8yrs exp SWE or Quant Dev to come work with me building out infrastructure for our quantitative overlay effort at a multibillion dollar fundamental HF that I've been working on for ~2 years. Strong preference is for somebody with buy side or prop firm tech experience so context around the tools we are building is understood. Our stack is still in its nascency but is a combination of Python and Rust with infra on AWS and GCP, so experience with all the devops stuffs like CI/CD, Docker, Terraform, cloud security is useful. Preferably you are in or will move to SF. If the heavy hitters @bennpeifert @KrisAbdelmessih @systematicls @moreproteinbars wouldn't mind sharing with their networks, I'm excited to bring a person on board that I can learn from and can learn from me while we kick ass and make some money.

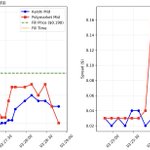
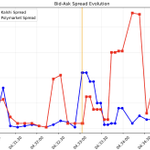
If anyone else was wondering why some of their features for predicting fair price of a sports market derived from Polymarket data were utterly useless…

Been quiet on here a while - but getting seriously into trading on prediction markets so going to document my journey and learn from the more HFT-minded folks on here.
As a start, here's me getting adversely selected on a sell order in a LA Dodgers game (you're welcome SIG)

As a mid-freq equities quant by training my only thought about an orderbook before this was the spread term in my t-cost model, so working on building intution around how to think about quoting from the maker side 🙏

Coastal Quant retweeted
The screenshot from the book are below. Remember that you can still download the draft at linktr.ee/paleologo. Pls repost so that all can rejoice in the pleasures of diversification.
(6/n=6)


