

Quality & Growth Investing at Expanse Stocks. Ride them with conviction. Links 👇
Spain
Joined February 2021
- Tweets3.6K
- Following314
- Followers1K
- Likes9.6K




Nikotes retweeted
Problem with just taking $CSU.TO consolidated numbers at face value is that PEMS bypasses those numbers and therefore there’s a “mismatch” between capital deployment and growth
The Asseco investment is not consolidated in Topicus’ numbers, so it isn’t consolidated either on CSU
Nikotes retweeted

Have been thinking about this as well. We've all had a front-row seat to the discussions and debates around the buildout, but once you get to use cases, the debate is fixated on coding and personal agents and drops off thereafter. Not as much around where broader enterprise adoption is. Found that surprising, especially because you need real enterprise adoption for any of this stuff to matter 5 years from now.
I picked up coverage of software, compute, and, power earlier this year and it was pretty jarring how far apart the software company debates were from and compute/power/semis/labs discourse.
If you follow the traditional SaaS businesses, especially the big system-of-record guys, it's clear that for most, real adoption and usage of AI products sold by the SaaS space is a late 2027 event at the earliest. $NOW and $TEAM are quickly realizing that they need to deploy engineers to customer sites like $PLTR. Both are telling investors to expect little to no revenue upside from customers using enough tokens to generate an overage beyond contracts. The "AI benefits" are contract expansions/upselling to plans that include it, an effort that companies seemingly believe must precede driving usage. Messy/noisy.
Then, if one looks at the infra SaaS players ($SNOW etc.), most of them aren't "benefitting from AI" the way you're thinking - they've just found new customers that spend at lot of money with them today. On the enterprise side, what you're seeing is not a big wave of AI usage demand, it's a big acceleration in cloud migrations that enterprises believe make them more "AI-ready". Migrations are often multi-year in nature. Cyber has elements of this as well.
Taken together, the logical reaction is "this means air pocket in 2027", but it's not like labs/the current apps aren't still growing rapidly, it's not 100% clear we're out of the woods on scarcity/buildout just yet, and some companies are farther along with their AI product launches than others.
That said, "air pocket" sounds scarier than it is. Think that's mostly because it implies deceleration, and it today like 80%+ of tech companies across both software + semis have a decelerating topline (most from growth rates that are attractive) and markets are punishing that right now.
In SW, it seems to be creating a lot of GARP-y profiles that are attractive in cases where one believes that terminal value is not going to 0. Patience while holding something cheap + durably growthy for a year gets rewarded in 2028+ with the benefits of acceleration etc.


Nikotes retweeted

$CSU.TO mothership earnings are out:
- Revenue +19% YoY
- Recurring organic growth +4% (CC)
- Acquistions: $609M (including deferred payments)
- Commitments: $673M 💪
Organic growth would be ~200 bps higher ex-Altera
Let's goooo!


Nikotes retweeted

Total Specific Solutions (Topicus) CFO Rob Eijbergen stepped in front of investors for the very first time at our client dinner, spending over an hour answering all of our questions.
How does Topicus’s decentralized acquisition model actually work from the inside? What’s their real-world playbook for AI? How do they view newcomers like Bending Spoons, and are there any plans for a TSX listing?
Read our exclusive report covering the key insights, audience Q&A, and our take: tresorcapitalnieuws.nl/en/de…
$TOI.V $CSU.TO


Nikotes retweeted

Had a night to sleep on $AXON earnings.
Thought Brian’s take was a good framing for how to see things.
Again my bias is to give management the benefit of the doubt (respect if others see it differently)
At a base level, management has made several moves that involve a bit of trust but also info out there to support what they are saying. At a macro level, CEO Rick Smith has “skated to where the puck is going” for a long time.
Josh talks about “building out inventory”. There’s lot of public info showing most PDs are ramping up orders, especially Dedrone. Plus complex deployments like to Bulgaria and other NATO members seem to offer some support for building it out. Also, building out inventory and supply chains also makes a long term resilient company, so that has long term benefits (beyond the line of sight on crazy demand).
Josh talks about lumpiness in Federal deals. Makes sense to me given shifting Congress and it’s not like the threat from UAVs has remotely subsided. Really not fun but they are trying to smooth out how they tell investors about this.
Josh talked about Skydio investment. There are so many articles about Axon doing small seed funding for companies in Ukraine and exploring the growing UAV ecosystem. Really seems they’ve done their homework. My research on Skydio seems to support this is the leader. So I can see the rationale for the investment.
All amidst the backdrop of the “good as gold” company earnings was not the same this quarter.
So where does this leave us?
PTs are going to come down (Needham today from $750 to $500… oof). Pain and maybe lack of catalyst until next earnings. And a make or break Q4 earnings that I feel Axon is taking as their Super Bowl and will rise to the occasion. Then seems 2027 will be a big year for their moat and whatever Rick has up his sleeve. Will continue to watch this one as I always do. 👊🔥

Pretty much everything with $AXON goes to how much you trust management.
If you DO trust this was really just about 3 delayed contracts, rev would've been 30% this quarter, a whopping 38% next quarter.
If you DON'T you probably shouldn't own the stock


Nikotes retweeted

Hello Claude,
I am down 70 percent in AI stocks that Leopold and Chamath and CNBCq recommended
I need you to make that back by Tuesday, leverage and perps are fine.
go.


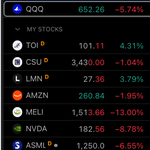
No way anyone could have imagined this price action today when, earlier this year, semis were rallying hard while quality / software was getting gutted... Or could we? 👀


I've got this one almost ready, but I'll be publishing it tomorrow morning.
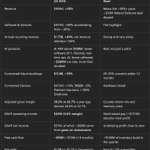
$MELI Q3 2026. A little preview of what's inside.

$MELI
My earnings digest will be published later today.
The flywheel they’re building across LATAM is undeniable. However, this time I’m taking a more critical look at the margin path and some of the risks that deserve greater attention and should be reflected in our models.


