

Presidential Fiscal Policy and Tax Reforms Committee
Nigeria
Joined August 2023
- Tweets357
- Following1
- Followers6.2K
- Likes149




Pinned Tweet
𝐒𝐭𝐚𝐲 𝐈𝐧𝐟𝐨𝐫𝐦𝐞𝐝, 𝐒𝐭𝐚𝐲 𝐀𝐡𝐞𝐚𝐝!
Get regular updates on Nigeria’s fiscal policy and tax reforms, and information on the activities of the Presidential Fiscal Policy and Tax Reforms Committee.
𝐒𝐜𝐚𝐧 𝐭𝐡𝐞 𝐐𝐑 𝐜𝐨𝐝𝐞 or click the link below 𝐭𝐨 𝐣𝐨𝐢𝐧 𝐨𝐮𝐫 𝐨𝐟𝐟𝐢𝐜𝐢𝐚𝐥 𝐖𝐡𝐚𝐭𝐬𝐀𝐩𝐩 𝐂𝐡𝐚𝐧𝐧𝐞𝐥 and be part of the conversation shaping Nigeria’s fiscal future.
whatsapp.com/channel/0029VaG…
#FiscalReforms #TaxReforms #Nigeria #PFPTRC #PublicFinance #EconomicGrowth

Fiscal Reforms Nigeria retweeted

𝐄𝐧𝐠𝐚𝐠𝐞𝐦𝐞𝐧𝐭𝐬 𝐰𝐢𝐭𝐡 𝐆𝐥𝐨𝐛𝐚𝐥 𝐈𝐧𝐯𝐞𝐬𝐭𝐨𝐫𝐬 𝐢𝐧 𝐏𝐚𝐫𝐢𝐬
"We will not bring back fuel subsidy because it creates distortions for the economy, and we won't introduce price control because we believe in the market... the situation in Iran presents new opportunities for us as the world looks to diversify sources of energy and invest in new markets."
"Nigeria recorded a strong GDP growth rate of 11.2% in US dollar terms in 2025 reinforcing the country's ambition to achieve a $1 trillion economy by 2030."
-𝘛𝘢𝘪𝘸𝘰 𝘖𝘺𝘦𝘥𝘦𝘭𝘦, 𝘔𝘪𝘯𝘪𝘴𝘵𝘦𝘳 𝘰𝘧 𝘍𝘪𝘯𝘢𝘯𝘤𝘦 𝘢𝘯𝘥 𝘊𝘰𝘰𝘳𝘥𝘪𝘯𝘢𝘵𝘪𝘯𝘨 𝘔𝘪𝘯𝘪𝘴𝘵𝘦𝘳 𝘰𝘧 𝘵𝘩𝘦 𝘌𝘤𝘰𝘯𝘰𝘮𝘺

Fiscal Reforms Nigeria retweeted
FEDERAL MINISTRY OF FINANCE PRESS STATEMENT
FALSE ALLEGATION OF HIDDEN SPENDING AND DIVERSION OF FEDERATION REVENUE
The attention of the Federal Ministry of Finance has been drawn to recent media reports and commentaries that misrepresent the findings of the latest Nigeria Development Update by the World Bank, particularly claims suggesting that a significant portion of federation earnings is being “diverted” or constitutes “hidden spending.”
These interpretations misrepresent the World Bank’s analysis and reflect a misunderstanding of the fiscal system.
MISINTERPRETATION OF FAAC DEDUCTIONS
The misreporting in question incorrectly characterises Federation Account Allocation Committee (FAAC) deductions as “waste” or missing funds. This is incorrect.
FAAC deductions, as presented in the World Bank report, include:
Statutory transfers,
Savings and investments,
Security-related expenditures,
Cost-of-collection charges,
Refunds to Ministries, Departments and Agencies (MDAs),
Transfers and interventions benefiting subnational governments.
It is important to emphasise that refunds and transfers to states and other tiers of government are not leakages. They represent legitimate fiscal flows, including repayments of obligations and statutorily backed allocations.
SELECTIVE USE OF OUTDATED DATA
Some commentaries selectively relied on past data while ignoring the forward-looking analysis and ongoing public financial management reforms highlighted in the report.
The World Bank explicitly notes that reforms implemented in early 2026, including the recently signed Executive Order to safeguard remittance of petroleum revenues, are already addressing concerns around deductions, and are expected to improve transparency while increasing revenues available to all tiers of government by about 0.4% of GDP annually.
Misinterpreting one aspect of the analysis without acknowledging the progressive reforms and measures already introduced to enhance distributable federation revenues gives a distorted picture.
STRONGER MACROECONOMIC FUNDAMENTALS
The broader message of the World Bank report is positive and forward-looking:
Economic growth is becoming more broad-based across sectors.
Inflation, while still elevated, is declining due to deliberate policy actions.
Nigeria’s external position has strengthened significantly, with improved reserves and a current account surplus.
Debt indicators have improved, including a decline in the debt-to-GDP ratio, the first in over a decade.
These developments reflect the outcomes of the current administration's ongoing macroeconomic policies and public financial management reforms.
THE REAL MESSAGE OF THE REPORT
The World Bank does not conclude that Nigeria’s fiscal system is collapsing or that reforms have failed. Rather, it states that reforms are working, and they must be sustained and deepened to translate macroeconomic gains into inclusive growth.
CONCLUSION
The Federal Government remains committed to strengthening fiscal transparency, improving revenue mobilisation, ensuring efficient public spending, and deepening reforms to support inclusive economic growth.
An accurate understanding and responsible reporting of fiscal information are critical to maintaining confidence in Nigeria’s reform trajectory and economic outlook.
We urge stakeholders, media organisations, and the public to engage constructively with fiscal information and avoid twisted interpretations that may undermine reform efforts and fuel public discord.
Signed
Taiwo Oyedele
Honourable Minister of State for Finance,
Federal Republic of Nigeria
April 19, 2026
”𝐅𝐀𝐊𝐄 𝐍𝐄𝐖𝐒 𝐀𝐋𝐄𝐑𝐓: “𝐓𝐀𝐈𝐖𝐎 𝐎𝐘𝐄𝐃𝐄𝐋𝐄 𝐅𝐈𝐍𝐀𝐋𝐋𝐘 𝐀𝐃𝐌𝐈𝐓𝐒 𝐄𝐑𝐑𝐎𝐑𝐒 𝐈𝐍 𝐓𝐇𝐄 𝐍𝐄𝐖 𝐓𝐀𝐗 𝐋𝐀𝐖𝐒”
Our attention has been drawn to misleading media reports claiming that the Honourable Minister of State for Finance, Mr. Taiwo Oyedele has "finally admitted errors in the new tax laws." These publications misrepresent the Minister's statements, falsely alleging that he urged Nigerians to await the outcome of a "legislative probe", a process that has long been concluded and the gazetted copies certified by the National Assembly published since early January 2026.
This twisted narrative is unhelpful as it risks distorting public understanding and misleading the very people the reforms were designed to benefit.
The Minister, during a recent fireside chat at the NBA SLP conference in Lagos, highlighted the early positive impact of the new tax laws, including thousands of informal businesses now seeking CAC registration daily while the number of individuals registered for tax purposes nationwide has increased from barely 10 million before the reform to over 100 million.
These impressive results stem from the robust design and progressive nature of the new laws, which include:
- Exemption of small companies from tax.
- Increased exemption thresholds for low-income earners.
- Tax exemptions on basic consumption items like food, education, healthcare, transportation, and rent.
- Introduction of the Tax Ombud to protect taxpayer right.
The Minister contrasted the transformative changes in the new laws with the regressive provisions in the old laws. He however emphasised that no law is perfect. Therefore, ongoing stakeholder engagement is essential to identify and address any errors or gaps for appropriate legislative updates through Finance Bills as part of a continuous improvement process.
We urge members of the public to disregard sensational headlines and twisted narratives and rely exclusively on official sources and credible media organisations for accurate information regarding the tax reform and other government policies.
God bless Nigeria!
-𝑷𝒓𝒆𝒔𝒊𝒅𝒆𝒏𝒕𝒊𝒂𝒍 𝑭𝒊𝒔𝒄𝒂𝒍 𝑷𝒐𝒍𝒊𝒄𝒚 & 𝑻𝒂𝒙 𝑹𝒆𝒇𝒐𝒓𝒎𝒔 𝑪𝒐𝒎𝒎𝒊𝒕𝒕𝒆𝒆


Enforcement of Tax Law Won’t Be Random, Says Taiwo Oyedele
Minister of State for Finance, Taiwo Oyedele, assured that enforcing Nigeria’s new tax laws will not be arbitrary, emphasizing that reforms are rooted in clear policy intent, transparency, and fairness.
Speaking during a fireside chat at the 2026 Annual Conference of the Nigerian Bar Association Section on Legal Practice, the theme was: “From Policy to Practice: Making Sense of Nigeria’s New Tax Reforms.”
Oyedele stressed the importance of understanding the rationale behind tax laws rather than focusing solely on their provisions.
According to him, many professionals often overlook the underlying purpose of tax legislation, noting that policy intent should guide both interpretation and implementation.
Oyedele highlighted inconsistencies in Nigeria’s previous tax regime, particularly the disparity between personal and corporate tax burdens, which discouraged business formalisation.
“Under the old system, an individual could pay an effective tax rate of about 19 per cent, but registering the same business as a company pushed the burden above 40 per cent. This was the opposite of global best practice,” he said.
He explained that the reform process prioritised creating incentives for businesses to formalise, while ensuring policy consistency and reducing discretion in tax administration.
Reflecting on past challenges, Oyedele recounted instances where policy inconsistencies discouraged foreign investment, including abrupt proposals to significantly increase taxes on gas companies.
“If policies can change overnight, it sends the wrong signal to investors. Consistency is critical,” he noted.
On inclusivity, Oyedele said the new tax framework deliberately protects low-income earners and small businesses.
He revealed that individuals earning around ₦1 million annually and a large portion of small businesses, estimated at 30 to 40 million, have limited capacity to pay taxes and are therefore shielded under the reforms.
“Nearly half of working Nigerians earn less than ₦70,000 monthly. Taxing them aggressively would be unjust,” he said.
The reforms also eliminate practices such as minimum tax payments on loss-making businesses, which he described as effectively taxing capital rather than profit.
Oyedele noted that essential goods and services, including food, education, and healthcare, have been exempted from Value Added Tax (VAT), making the system more progressive.
He further explained that the reforms consolidated multiple tax laws into four major pieces of legislation, including the Nigeria Tax Act and the Nigeria Tax Administration Act, aimed at simplifying compliance and improving coordination among tax authorities.
Addressing concerns about discrepancies in the law-making process, Oyedele acknowledged that errors occurred due to manual processes and multiple stages of review.
He said steps are underway to correct identified issues through a proposed finance bill.
“What we need is a more transparent and reliable legislative process where every version of a law is publicly available,” he stated.
Oyedele also underscored the critical role of legal practitioners in shaping economic outcomes through tax advisory and compliance.
“The decisions lawyers help businesses make will determine investment, job creation, and revenue generation,” he said.
While acknowledging improvements in public revenue utilisation, he called for greater impact and efficiency, noting that Nigeria still lags behind countries like South Africa in tax collection.
“If we improve collection, we can significantly increase funding for infrastructure, education, and healthcare,” he added.
He urged lawyers to focus on effective implementation, stressing that the success of the reforms ultimately depends on how well they are applied in practice.

Honouring Excellence in Public Finance 🇳🇬
Over the weekend, the Honourable Minister of State for Finance @taiwoyedele was hosted to a distinguished dinner reception by the Association of Chartered Certified Accountants (ACCA) Nigeria, a globally recognised professional body for accountants.
An evening of meaningful engagements, shared vision, and continued collaboration towards strengthening Nigeria’s economic and fiscal future.
Footage credit: Arise News
#ACCA #PublicFinance #Leadership #Nigeria #FiscalPolicy #EconomicDevelopment #TaxReforms
Fiscal Reforms Nigeria retweeted
Today, I had the honour of being sworn in as Minister of State for Finance of the Federal Republic of Nigeria.
I am sincerely grateful to President Bola Ahmed Tinubu, GCFR, for the trust and confidence placed in me, and to the Senate for confirming my nomination.
This appointment is not merely a personal milestone; it is a call to greater service. Nigeria faces important fiscal challenges, but also immense opportunities. The decisions we make in public finance today will shape the prosperity, stability, and well-being of our country for generations to come.
In my new role, I will focus on supporting efforts to strengthen revenue mobilisation, promote fiscal discipline, and ensure that public resources translate into real improvements in the lives of Nigerians.
I look forward to working more closely with the Honourable Minister of Finance and Coordinating Minister of the Economy, colleagues across government, the National Assembly, private sector, and development partners to advance the mission of financing Nigeria for sustainable development.
Public service demands integrity, humility, and dedication. I step into this responsibility with a deep sense of duty and commitment to Nigeria and the Nigerian people.
Thank you to everyone who has supported and encouraged me along this journey. I will be counting on your continued support.
The work begins. God bless Nigeria.
#MinistryofFinance #FiscalReform #Nigeria #SustainableDevelopment


Fiscal Reforms Nigeria retweeted
𝐂𝐥𝐚𝐫𝐢𝐟𝐢𝐜𝐚𝐭𝐢𝐨𝐧: 𝐓𝐡𝐞 𝐍𝐢𝐠𝐞𝐫𝐢𝐚 𝐓𝐚𝐱 𝐀𝐜𝐭 2025 𝐡𝐚𝐬 𝐂𝐨𝐦𝐦𝐞𝐧𝐜𝐞𝐝 𝐚𝐧𝐝 𝐃𝐨𝐞𝐬 𝐍𝐎𝐓 𝐈𝐦𝐩𝐨𝐬𝐞 𝐚 25% 𝐓𝐚𝐱 𝐨𝐧 𝐁𝐮𝐢𝐥𝐝𝐢𝐧𝐠 𝐌𝐚𝐭𝐞𝐫𝐢𝐚𝐥𝐬 𝐨𝐫 𝐅𝐮𝐧𝐝𝐬
We are aware of a recent video claiming that the new tax laws will commence in 2027 and alleging the imposition of a 25% tax on funds for building materials and other transactions.
Both claims are incorrect. Contrary to the misinformation seeking to create fear, panic and disaffection, the Nigeria Tax Act 2025 has already commenced and does not impose a 25% tax on construction funds, bank balances, or business expenses. Instead, it contains provisions specifically designed to reduce the cost of housing, rent and real estate development.
𝐊𝐞𝐲 𝐏𝐫𝐨𝐯𝐢𝐬𝐢𝐨𝐧𝐬 𝐨𝐟 𝐭𝐡𝐞 𝐍𝐢𝐠𝐞𝐫𝐢𝐚 𝐓𝐚𝐱 𝐀𝐜𝐭, 2025
Relevant provisions to make housing more affordable, encourage real estate development, and support small business property contractors and low-income renters include:
1. 𝑳𝒐𝒘𝒆𝒓 𝑪𝒐𝒔𝒕 𝒐𝒇 𝑩𝒖𝒊𝒍𝒅𝒊𝒏𝒈 𝒂𝒏𝒅 𝑷𝒓𝒐𝒑𝒆𝒓𝒕𝒚 𝑫𝒆𝒗𝒆𝒍𝒐𝒑𝒎𝒆𝒏𝒕
𝘝𝘈𝘛 𝘌𝘹𝘦𝘮𝘱𝘵𝘪𝘰𝘯 𝘰𝘯 𝘓𝘢𝘯𝘥 𝘢𝘯𝘥 𝘉𝘶𝘪𝘭𝘥𝘪𝘯𝘨𝘴 (𝘚.185(𝘭)): Land and buildings are now specifically exempt from Value Added Tax (VAT).
𝘐𝘯𝘱𝘶𝘵 𝘝𝘈𝘛 𝘊𝘳𝘦𝘥𝘪𝘵𝘴 𝘧𝘰𝘳 𝘊𝘰𝘯𝘵𝘳𝘢𝘤𝘵𝘰𝘳𝘴: Where VAT is chargeable on any materials or service, contractors can now recover VAT on their assets and overhead costs, which lowers overall construction costs.
𝘙𝘦𝘥𝘶𝘤𝘦𝘥 𝘞𝘪𝘵𝘩𝘩𝘰𝘭𝘥𝘪𝘯𝘨 𝘛𝘢𝘹 (𝘞𝘏𝘛): A lower 2% WHT rate is applicable on construction contracts, helping to conserve cash flow and reduce financing pressure on developers.
𝘓𝘰𝘢𝘯 𝘐𝘯𝘵𝘦𝘳𝘦𝘴𝘵 𝘋𝘦𝘥𝘶𝘤𝘵𝘪𝘰𝘯 (𝘚.30(2)(𝘪𝘷)): Mortgage interest is tax-deductible for individuals developing an owner-occupied residential house.
𝘋𝘦𝘥𝘶𝘤𝘵𝘪𝘣𝘭𝘦 𝘙𝘦𝘯𝘵𝘢𝘭 𝘌𝘹𝘱𝘦𝘯𝘴𝘦𝘴 (𝘚.20): Property owners who earn rental income can deduct related costs such as repairs, insurance, and agency fees.
2. 𝑫𝒊𝒓𝒆𝒄𝒕 𝑹𝒆𝒍𝒊𝒆𝒇 𝒇𝒐𝒓 𝑹𝒆𝒏𝒕𝒆𝒓𝒔 𝒂𝒏𝒅 𝑻𝒆𝒏𝒂𝒏𝒕𝒔
𝘙𝘦𝘯𝘵 𝘙𝘦𝘭𝘪𝘦𝘧 (𝘚.30(2)(𝘷𝘪)): Individuals can claim relief up to ₦500,000 (20% of annual rent), increasing disposable income for low-income earners.
𝘝𝘈𝘛 𝘌𝘹𝘦𝘮𝘱𝘵𝘪𝘰𝘯 𝘰𝘯 𝘙𝘦𝘯𝘵 (𝘚.185(𝘭)): The VAT exemption on land and buildings also covers rent which is fully exempt from Value Added Tax.
𝘚𝘵𝘢𝘮𝘱 𝘋𝘶𝘵𝘺 𝘙𝘦𝘭𝘪𝘦𝘧 (𝘚.134): Lease agreements with an annual value below ₦10,000,000 (or 10 times the annual minimum wage) are exempt from stamp duty.
3. 𝑰𝒏𝒄𝒆𝒏𝒕𝒊𝒗𝒆𝒔 𝒇𝒐𝒓 𝑰𝒏𝒗𝒆𝒔𝒕𝒐𝒓𝒔 𝒂𝒏𝒅 𝑫𝒆𝒗𝒆𝒍𝒐𝒑𝒆𝒓𝒔
𝘊𝘢𝘱𝘪𝘵𝘢𝘭 𝘎𝘢𝘪𝘯𝘴 𝘛𝘢𝘹 𝘌𝘹𝘦𝘮𝘱𝘵𝘪𝘰𝘯 (𝘚.51(1)): Individuals pay no Capital Gains Tax (CGT) when disposing of a dwelling house or an interest in one.
𝘙𝘌𝘐𝘛 𝘐𝘯𝘤𝘦𝘯𝘵𝘪𝘷𝘦𝘴 (𝘚.162(𝘤)): Real Estate Investment Trusts (REITs) are exempt from Companies Income Tax (CIT) when distributing at least 75% of their dividend or rental income within 12 months after the financial year-end.
𝘗𝘳𝘪𝘰𝘳𝘪𝘵𝘺 𝘚𝘦𝘤𝘵𝘰𝘳 𝘐𝘯𝘤𝘦𝘯𝘵𝘪𝘷𝘦𝘴: Manufacturing of building materials such as iron, steel, and domestic appliances qualifies for specific tax exemption under the economic development incentive scheme for up to 10 years.
𝘙𝘦𝘥𝘶𝘤𝘦𝘥 𝘊𝘰𝘳𝘱𝘰𝘳𝘢𝘵𝘦 𝘛𝘢𝘹 𝘙𝘢𝘵𝘦 (𝘚.56): Scope for the reduction of companies income tax rate for large businesses from 30% to 25%.
4. 𝑷𝒓𝒐𝒕𝒆𝒄𝒕𝒊𝒐𝒏 𝒇𝒐𝒓 𝑾𝒐𝒓𝒌𝒆𝒓𝒔 𝒂𝒏𝒅 𝑺𝒎𝒂𝒍𝒍 𝑩𝒖𝒔𝒊𝒏𝒆𝒔𝒔𝒆𝒔
• 𝘊𝘢𝘱 𝘰𝘯 𝘏𝘰𝘶𝘴𝘪𝘯𝘨 𝘉𝘦𝘯𝘦𝘧𝘪𝘵 𝘛𝘢𝘹 (𝘚.14(6)): The taxable value of employer-provided accommodation is limited to the annual rental value, subject to a maximum of 20% of the employee's annual gross employment income, excluding the rental value.
• 𝘚𝘮𝘢𝘭𝘭 𝘊𝘰𝘮𝘱𝘢𝘯𝘺 𝘙𝘦𝘭𝘪𝘦𝘧: Suppliers and contractors who qualify as small companies benefit from 0% Companies Income Tax (CIT), exemption from charging VAT and no deduction of Withholding Tax (WHT) from their invoices and payments.
5. 𝑾𝒉𝒂𝒕 𝒊𝒔 𝑵𝑶𝑻 𝒊𝒏 𝒕𝒉𝒆 𝑻𝒂𝒙 𝑳𝒂𝒘
The Act does not:
• Tax money in bank accounts or bank balances.
• Tax transfers for buying building materials.
• Introduce a 25% construction or business cost tax.
• Delay implementation until 2027.
𝐂𝐨𝐧𝐜𝐥𝐮𝐬𝐢𝐨𝐧:
Claims suggesting a new tax on building materials or bank funds are false and misrepresent the law. Rather, the new tax law specifically introduced measures to make housing more affordable, promote real estate development, incentivise manufacturing of building materials, and grant rent reliefs to tenants to enhance their disposable income.
𝐅𝐈𝐍𝐀𝐋 𝐖𝐎𝐑𝐃:
“Fact Not Fear”, evidence beats emotion. If anyone makes an alarming claim or tries to misinform you, ask them “Where is it in the law?”
With the new tax laws, housing should become more affordable and rent should go down NOT up!
— 𝘗𝘳𝘦𝘴𝘪𝘥𝘦𝘯𝘵𝘪𝘢𝘭 𝘍𝘪𝘴𝘤𝘢𝘭 𝘗𝘰𝘭𝘪𝘤𝘺 𝘢𝘯𝘥 𝘛𝘢𝘹 𝘙𝘦𝘧𝘰𝘳𝘮𝘴 𝘊𝘰𝘮𝘮𝘪𝘵𝘵𝘦𝘦
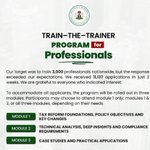
𝐓𝐚𝐱 𝐑𝐞𝐟𝐨𝐫𝐦 𝐓𝐫𝐚𝐢𝐧𝐢𝐧𝐠 𝐟𝐨𝐫 𝐏𝐫𝐨𝐟𝐞𝐬𝐬𝐢𝐨𝐧𝐚𝐥𝐬
We are pleased to announce that over 11,000 professionals registered for our Train-The-Trainer Programme, and we have successfully completed Module 1 of the training.
Participants are now invited to join the next sessions under Module 2:
Date: Wednesday, 11 February 2026
Time: 5:00 PM – 7:30 PM
This training is designed to equip participants with the knowledge and practical tools required for effective implementation, efficient compliance, and optimisation of the benefits of the new tax reforms.
Who Should Attend:
Tax professionals, accountants, lawyers, economists, academics, finance managers, compliance officers, revenue administrators, legal advisers, policy analysts, and consultants involved in tax compliance, analysis, and advisory services.
Link for Registration & Other Details:
drive.google.com/drive/folde…
We look forward to your participation.
- 𝑷𝒓𝒆𝒔𝒊𝒅𝒆𝒏𝒕𝒊𝒂𝒍 𝑭𝒊𝒔𝒄𝒂𝒍 𝑷𝒐𝒍𝒊𝒄𝒚 𝒂𝒏𝒅 𝑻𝒂𝒙 𝑹𝒆𝒇𝒐𝒓𝒎𝒔 𝑪𝒐𝒎𝒎𝒊𝒕𝒕𝒆𝒆

Fiscal Reforms Nigeria retweeted
𝐓𝐚𝐱 𝐑𝐞𝐟𝐨𝐫𝐦 𝐈𝐦𝐩𝐥𝐞𝐦𝐞𝐧𝐭𝐚𝐭𝐢𝐨𝐧 𝐄𝐧𝐠𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐰𝐢𝐭𝐡 𝐇𝐑 𝐚𝐧𝐝 𝐏𝐚𝐲𝐫𝐨𝐥𝐥 𝐏𝐫𝐨𝐟𝐞𝐬𝐬𝐢𝐨𝐧𝐚𝐥𝐬
We recently hosted an engagement sesion on the implementation of the Tax Reform Acts for HR, Payroll, CFOs and Tax Managers, in collaboration with the Joint Revenue Board (JRB).
We thank the nearly 15,000 people that registered for the session. For those who could not join us live due to the virtual webinar capacity limitation, we have provided the full session recording below.
𝐊𝐞𝐲 𝐒𝐞𝐬𝐬𝐢𝐨𝐧 𝐇𝐢𝐠𝐡𝐥𝐢𝐠𝐡𝐭𝐬
𝘌𝘹𝘦𝘮𝘱𝘵𝘪𝘰𝘯 𝘧𝘰𝘳 𝘮𝘢𝘯𝘺 𝘸𝘰𝘳𝘬𝘦𝘳𝘴: The new laws protect low-income earners with automatic exemption for anyone earning the national minimum wage or less. Where deductible contributions and rent relief are taken into account, employees earning up to ₦100,000 per month may also see their tax liability drop to zero.
𝘍𝘪𝘴𝘤𝘢𝘭 𝘧𝘦𝘥𝘦𝘳𝘢𝘭𝘪𝘴𝘮: Personal Income Tax remains payable to the relevant State Internal Revenue Services (SIRS), not the NRS. All revenue agencies will work together under the Joint Revenue Board to ensure a harmonised and seamless experience for taxpayers.
𝘗𝘢𝘳𝘵𝘯𝘦𝘳𝘴𝘩𝘪𝘱 𝘐𝘯𝘤𝘰𝘮𝘦: Taxes for individuals in a partnership are payable to each partner’s state of residence.
𝘊𝘰𝘮𝘱𝘦𝘵𝘪𝘵𝘪𝘷𝘦 𝘳𝘦𝘮𝘰𝘵𝘦 𝘸𝘰𝘳𝘬 𝘵𝘢𝘹 𝘳𝘦𝘨𝘪𝘮𝘦: Nigeria is now more competitive for global talent. Foreign employers are no longer deemed taxable in Nigeria solely because they have employees working remotely in the country.
𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐨𝐧𝐚𝐥𝐢𝐬𝐢𝐧𝐠 𝐭𝐡𝐞 𝐍𝐞𝐰 𝐏𝐀𝐘𝐄 𝐂𝐨𝐦𝐩𝐮𝐭𝐚𝐭𝐢𝐨𝐧
To ensure that individuals benefit from the pro-workers provisions of the new tax laws, payroll managers are encouraged to follow the process below:
Step 1 - Start with gross income
Step 2 - Add benefits-in-kind (if applicable)
Step 3 - Grant reliefs for pension, NHIS, NHF etc
Step 4 - Apply rent relief (20% of actual rent paid capped at ₦500,000)
Step 5 - Exempt the first ₦800,000 (taxed at 0%) and apply progressive rates thereafter.
While the top marginal rate is 25%, the effective rate is much lower due to these deductions.
𝐈𝐦𝐩𝐨𝐫𝐭𝐚𝐧𝐭 𝐟𝐢𝐥𝐢𝐧𝐠 𝐝𝐞𝐚𝐝𝐥𝐢𝐧𝐞𝐬:
- Employer annual returns: Due by 31 January each year, covering employees’ emoluments and tax deductions.
- Individual self-assessment return: To be filed by every taxable individuals including employees not later than 31 March covering all income sources.
- Tax incentives return: A new requirement for beneficiaries of specific tax incentives.
Watch the full recording here: youtu.be/gqviRp1k2VQ
#TaxReformNG #PayrollManagement #TaxReliefs

Fiscal Reforms Nigeria retweeted
𝐅𝐀𝐐𝐬 𝐨𝐧 𝐏𝐨𝐰𝐞𝐫 𝐨𝐟 𝐒𝐮𝐛𝐬𝐭𝐢𝐭𝐮𝐭𝐢𝐨𝐧 𝐢𝐧 𝐓𝐚𝐱 𝐀𝐝𝐦𝐢𝐧𝐢𝐬𝐭𝐫𝐚𝐭𝐢𝐨𝐧
𝑸1: 𝑾𝒉𝒂𝒕 𝒊𝒔 "𝒑𝒐𝒘𝒆𝒓 𝒐𝒇 𝒔𝒖𝒃𝒔𝒕𝒊𝒕𝒖𝒕𝒊𝒐𝒏"?
The power of substitution is a tax recovery mechanism that permits the tax authority to issue a directive to a third party (a 'substitute') to remit funds belonging to a defaulting taxpayer to settle a final, established, and unpaid tax liability. This power is only exercised after all legal and administrative processes, including appeals to the courts, have been exhausted.
𝑸2: 𝑰𝒔 𝒕𝒉𝒆𝒓𝒆 𝒂 𝒓𝒊𝒔𝒌 𝒐𝒇 𝒂𝒓𝒃𝒊𝒕𝒓𝒂𝒓𝒚 𝒖𝒔𝒆 𝒐𝒇 𝒕𝒉𝒊𝒔 𝒑𝒐𝒘𝒆𝒓?
No. The power of substitution is neither arbitrary nor discretionary. Its use is strictly governed by due process and can only be invoked after all established processes involving enquiries, assessments, objections, final notice, and appeals to the courts have been concluded, and the tax liability has become final and conclusive. It serves as a rigorously controlled, last-resort, not a routine administrative action.
𝑸3: 𝑫𝒐𝒆𝒔 𝒕𝒉𝒊𝒔 𝒂𝒇𝒇𝒆𝒄𝒕 𝒍𝒐𝒘-𝒊𝒏𝒄𝒐𝒎𝒆 𝒆𝒂𝒓𝒏𝒆𝒓𝒔 𝒐𝒓 𝒔𝒎𝒂𝒍𝒍 𝒃𝒖𝒔𝒊𝒏𝒆𝒔𝒔𝒆𝒔?
Individuals earning the national minimum wage or small businesses operating below applicable taxable thresholds are outside the scope of this measure. The power of substitution is only worthwhile where there is a substantial tax liability, which these groups generally do not have under the new tax laws.
𝑸4: 𝑰𝒔 𝒕𝒉𝒆 𝒑𝒐𝒘𝒆𝒓 𝒐𝒇 𝒔𝒖𝒃𝒔𝒕𝒊𝒕𝒖𝒕𝒊𝒐𝒏 𝒂 𝒏𝒆𝒘 𝒑𝒓𝒐𝒗𝒊𝒔𝒊𝒐𝒏 𝒊𝒏 𝑵𝒊𝒈𝒆𝒓𝒊𝒂𝒏 𝒕𝒂𝒙 𝒍𝒂𝒘𝒔?
No. This power is not new. It has been an existing provision of Nigeria’s tax legislation, including section 50 of the repealed Personal Income Tax Act (PITA) and various other tax statutes.
𝑸5: 𝑰𝒔 𝒕𝒉𝒊𝒔 𝒂 𝒈𝒍𝒐𝒃𝒂𝒍𝒍𝒚 𝒂𝒄𝒄𝒆𝒑𝒕𝒆𝒅 𝒑𝒓𝒂𝒄𝒕𝒊𝒄𝒆?
Yes. The use of third-party collection mechanisms is consistent with global best practices in tax administration. Similar powers, such as issuing garnishment or third-party payment notices, are common in tax jurisdictions worldwide to recover confirmed tax debts.
𝑸6: 𝑾𝒉𝒚 𝒊𝒔 𝒕𝒉𝒊𝒔 𝒑𝒐𝒘𝒆𝒓 𝒏𝒆𝒄𝒆𝒔𝒔𝒂𝒓𝒚?
This power is essential for maintaining fairness within the tax system. Without effective enforcement tools, compliant taxpayers are unfairly burdened, tax evasion is inadvertently encouraged, and government finances face undue pressure, which can lead to higher tax rates for all.
𝑸7: 𝑼𝒏𝒅𝒆𝒓 𝒘𝒉𝒂𝒕 𝒄𝒐𝒏𝒅𝒊𝒕𝒊𝒐𝒏𝒔 𝒄𝒂𝒏 𝒕𝒉𝒆 𝒕𝒂𝒙 𝒂𝒖𝒕𝒉𝒐𝒓𝒊𝒕𝒚 𝒆𝒙𝒆𝒓𝒄𝒊𝒔𝒆 𝒕𝒉𝒊𝒔 𝒑𝒐𝒘𝒆𝒓?
The power of substitution is strictly a last-resort measure and requires the simultaneous fulfillment of the following three conditions:
Exhausted process - the entire process for establishing a tax liability (enquiries, assessment, objection, final notice, and appeal involving the court) has been concluded.
Final liability - the taxpayer has a confirmed, final tax liability that is legally due and payable.
Refusal to pay - the taxpayer has failed, neglected, or refused to pay the debt within the written period specified by the tax authority.
𝑸8: 𝑾𝒉𝒐 𝒄𝒂𝒏 𝒃𝒆 𝒂𝒑𝒑𝒐𝒊𝒏𝒕𝒆𝒅 𝒂𝒔 𝒂 '𝒔𝒖𝒃𝒔𝒕𝒊𝒕𝒖𝒕𝒆' 𝒐𝒇 𝒂 𝒅𝒆𝒇𝒂𝒖𝒍𝒕𝒊𝒏𝒈 𝒕𝒂𝒙𝒑𝒂𝒚𝒆𝒓?
The tax authority can issue a notice of substitution to any person who holds funds belonging to, or owes sums of money due to the defaulting taxpayer.
𝑸9: 𝑾𝒉𝒂𝒕 𝒂𝒓𝒆 𝒕𝒉𝒆 𝒐𝒃𝒍𝒊𝒈𝒂𝒕𝒊𝒐𝒏𝒔 𝒐𝒇 𝒂 𝒔𝒖𝒃𝒔𝒕𝒊𝒕𝒖𝒕𝒆, 𝒂𝒏𝒅 𝒄𝒂𝒏 𝒔𝒖𝒄𝒉 𝒂 𝒑𝒆𝒓𝒔𝒐𝒏 𝒅𝒆𝒄𝒍𝒊𝒏𝒆 𝒕𝒉𝒆 𝒂𝒑𝒑𝒐𝒊𝒏𝒕𝒎𝒆𝒏𝒕?
Upon receiving a notice of substitution, the appointed party is statutorily obligated to either comply or formally object in writing within 30 days. The objection must specify the grounds for refusal. The legal provisions for appealing tax assessments are also applicable to the substitution notice.
𝑸10: 𝑾𝒉𝒂𝒕 𝒂𝒓𝒆 𝒕𝒉𝒆 𝒔𝒑𝒆𝒄𝒊𝒇𝒊𝒄 𝒔𝒂𝒇𝒆𝒈𝒖𝒂𝒓𝒅𝒔 𝒕𝒐 𝒑𝒓𝒆𝒗𝒆𝒏𝒕 𝒕𝒉𝒆 𝒂𝒃𝒖𝒔𝒆 𝒐𝒇 𝒕𝒉𝒊𝒔 𝒑𝒐𝒘𝒆𝒓?
Various legal and administrative safeguards exist to ensure the power is controlled, subject to review, and accountable including:
Due process - a mandatory due process for establishing the final tax assessment.
Right to object - a statutory right for the substitute to object in writing within 30 days.
Appeal rights - comprehensive appeal rights under the established tax dispute resolution framework.
Taxpayer rights - protection for the taxpayer or appointed agent by the Office of the Tax Ombud.
𝐂𝐨𝐧𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐌𝐞𝐬𝐬𝐚𝐠𝐞
The power of substitution, including its framework under the new tax laws, is a carefully controlled mechanism designed to ensure equity in the tax system. It is not punitive, arbitrary, or intended for routine administration, which is why its use has been historically rare. It exists to ensure that confirmed and lawful tax debts are ultimately paid by those who may choose to ignore their statutory obligations.
-𝘗𝘳𝘦𝘴𝘪𝘥𝘦𝘯𝘵𝘪𝘢𝘭 𝘍𝘪𝘴𝘤𝘢𝘭 𝘗𝘰𝘭𝘪𝘤𝘺 & 𝘛𝘢𝘹 𝘙𝘦𝘧𝘰𝘳𝘮𝘴 𝘊𝘰𝘮𝘮𝘪𝘵𝘵𝘦𝘦
We are pleased to note the feedback from workers who have received their salaries for January 2026 and confirmed a reduction in their PAYE tax resulting in higher take home pay under the new tax laws.
To ensure that relevant individuals charged with the responsibility to implement these changes for the benefit of employees in their organisations are well informed, the Presidential Fiscal Policy and Tax Reforms Committee is hosting a session for the key stakeholders in collaboration with the Joint Revenue Board.
𝐓𝐚𝐱 𝐑𝐞𝐟𝐨𝐫𝐦 𝐈𝐦𝐩𝐥𝐞𝐦𝐞𝐧𝐭𝐚𝐭𝐢𝐨𝐧 𝐒𝐞𝐬𝐬𝐢𝐨𝐧 𝐟𝐨𝐫 𝐇𝐑, 𝐏𝐚𝐲𝐫𝐨𝐥𝐥 𝐚𝐧𝐝 𝐓𝐚𝐱 𝐌𝐚𝐧𝐚𝐠𝐞𝐫𝐬
You are invited to register for an engagement session with the Joint Revenue Board and the Presidential Fiscal Policy & Tax Reforms Committee.
𝐓𝐚𝐫𝐠𝐞𝐭 𝐚𝐮𝐝𝐢𝐞𝐧𝐜𝐞:
HR Directors, Payroll Managers, Chief Financial Officers, Tax Managers and Other Senior Executives responsible for the management of employee compensation and payroll tax compliance.
When: Wednesday Jan 28, 2026
Time: 3:00 PM Nigerian Time
Topic: Personal Income Tax Compliance Under the New Tax Reform Acts
Register in advance for this webinar:
us06web.zoom.us/webinar/regi…
After registering, you will receive a confirmation email containing information about joining the webinar.
#FiscalReforms #TaxBenefits #KnowledgeIsPower

Fiscal Reforms Nigeria retweeted
𝐄𝐧𝐠𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐒𝐞𝐬𝐬𝐢𝐨𝐧 𝐨𝐧 𝐈𝐦𝐩𝐥𝐞𝐦𝐞𝐧𝐭𝐚𝐭𝐢𝐨𝐧 𝐨𝐟 𝐍𝐞𝐰 𝐓𝐚𝐱 𝐀𝐜𝐭𝐬 𝐟𝐨𝐫 𝐅𝐢𝐧𝐚𝐧𝐜𝐢𝐚𝐥 𝐈𝐧𝐬𝐭𝐢𝐭𝐮𝐭𝐢𝐨𝐧𝐬
𝘋𝘪𝘥 𝘺𝘰𝘶 𝘬𝘯𝘰𝘸 𝘵𝘩𝘢𝘵 𝘵𝘩𝘦 𝘵𝘢𝘹 𝘳𝘦𝘧𝘰𝘳𝘮𝘴 𝘥𝘪𝘥 𝘯𝘰𝘵 𝘪𝘯𝘵𝘳𝘰𝘥𝘶𝘤𝘦 𝘢𝘯𝘺 𝘯𝘦𝘸 𝘵𝘢𝘹 𝘰𝘳 𝘭𝘦𝘷𝘺 𝘰𝘯 𝘦𝘭𝘦𝘤𝘵𝘳𝘰𝘯𝘪𝘤 𝘵𝘳𝘢𝘯𝘴𝘧𝘦𝘳𝘴 𝘰𝘳 𝘮𝘰𝘯𝘦𝘺 𝘪𝘯 𝘺𝘰𝘶𝘳 𝘣𝘢𝘯𝘬 𝘢𝘤𝘤𝘰𝘶𝘯𝘵𝘴? In fact, under the new laws, many businesses are now eligible to claim input VAT credits on bank charges.
To support smooth implementation and clear communication, a multi-stakeholder engagement session was recently held for financial institutions, involving the Nigeria Revenue Service, the Joint Revenue Board, the Central Bank of Nigeria, and the Presidential Fiscal Policy & Tax Reforms Committee.
Participants included Risk and Compliance Officers, Legal Advisers, Chief Financial Officers, and Regulatory Affairs Executives from fintechs, commercial banks, microfinance banks, pension funds, asset managers, investment and securities firms, and other financial institutions.
Key issues focused on:
• Ensuring customers are not wrongly charged
• Tax ID as a requirement for bank accounts operated for business or income purposes (introduced since 13 January 2020)
• Providing tailored information to support customers in filing their tax returns and claiming tax deductions
• Repeal of Tax Clearance Certificates (TCC) as a requirement for foreign exchange transactions to improve ease of doing business
• Clarifying the due process for the exercise of the power of substitution by tax authorities (which had always existed under previous laws)
• Additional taxpayer safeguards and protections under the Office of the Tax Ombud.
The tax reforms are designed to support formalisation, tax harmonisation, and financial inclusion, while improving trust and efficiency across the financial system.
#TaxReforms #EaseOfDoingBusiness #KnowledgeIsPower
Fiscal Reforms Nigeria retweeted
𝐌𝐚𝐧𝐮𝐟𝐚𝐜𝐭𝐮𝐫𝐞𝐫𝐬 𝐁𝐚𝐜𝐤 𝐓𝐚𝐱 𝐑𝐞𝐟𝐨𝐫𝐦𝐬, 𝐂𝐚𝐥𝐥 𝐟𝐨𝐫 𝐀𝐜𝐜𝐞𝐥𝐞𝐫𝐚𝐭𝐞𝐝 𝐓𝐚𝐱 𝐇𝐚𝐫𝐦𝐨𝐧𝐢𝐬𝐚𝐭𝐢𝐨𝐧 𝐀𝐜𝐫𝐨𝐬𝐬 𝐒𝐭𝐚𝐭𝐞𝐬
The Manufacturers Association of Nigeria (MAN) recently hosted a hybrid stakeholder engagement with the Presidential Committee on Fiscal Policy and Tax Reforms, focused on the implications of the new tax laws for the manufacturing sector.
The session highlighted key benefits of the reforms aimed at reducing the tax burden on manufacturers and simplifying compliance, including -
Key benefits for manufacturers:
• Harmonisation: Elimination of multiple taxes to streamline operations
• Incentives: Expanded input VAT credits and improved incentives for priority sectors
• Efficiency: Promotion of technology adoption and automation to simplify and modernise tax compliance processes and elimination of burdensome compliance requirements such as certificate of acceptance for fixed assets as a precondition for capital allowance.
• Equity & fairness: Rationalisation of distortionary incentives and higher tax exemption thresholds for small businesses.
• Business growth: Removal of withholding tax on manufacturers and turnover tax, helping conserve cash flow and avoid taxation of capital.
• Taxpayer protection: Establishment of the Office of Tax Ombud to protect taxpayer rights and curb harassment and exploitation.
Areas identified for clarification and further action include:
• High import tariffs on certain raw materials
• Tax treatment and exemptions for exports
• Accelerated adoption of tax harmonisation laws by all states to complement the national reforms and curb multiple taxation by state and non-state actors
The dialogue also featured a robust Q&A session with industry participants.
Watch the full session here: youtu.be/OtfLcppl1kM
#TaxReforms #Manufacturing #EaseOfDoingBusiness #FiscalPolicy #Nigeria

Fiscal Reforms Nigeria retweeted
𝐂𝐡𝐚𝐦𝐛𝐞𝐫𝐬 𝐨𝐟 𝐂𝐨𝐦𝐦𝐞𝐫𝐜𝐞 𝐋𝐚𝐮𝐝 𝐓𝐚𝐱 𝐑𝐞𝐟𝐨𝐫𝐦𝐬 𝐀𝐢𝐦𝐞𝐝 𝐀𝐭 𝐁𝐨𝐨𝐬𝐭𝐢𝐧𝐠 𝐂𝐨𝐦𝐩𝐞𝐭𝐢𝐭𝐢𝐯𝐞𝐧𝐞𝐬𝐬 𝐚𝐧𝐝 𝐁𝐮𝐬𝐢𝐧𝐞𝐬𝐬 𝐆𝐫𝐨𝐰𝐭𝐡
The Lagos Chamber of Commerce and Industry (LCCI) recently hosted its 2026 Economic Outlook, which featured a session on the implementation of the new tax system and its implications for business and investment by the Presidential Committee on Fiscal Policy and Tax Reforms.
Participants at the session commended the Federal Government for the bold reforms aimed at addressing long-standing fiscal and tax barriers to investment and business growth.
Key provisions of the new tax laws highlighted as enablers of competitiveness, poverty reduction, and sustainable development include:
• Tax exemption for low-income earners and small businesses
• Planned reduction of Company Income Tax from 30% to 25%
• Expanded VAT input credits for businesses
• Removal of VAT on basic consumption items
• Introduction of economic development incentives for priority sectors
The Chamber called for clearer transition rules and continued stakeholder engagement and enlightenment to address concerns and ensure smooth implementation of the reforms.
Watch the full session here:
youtube.com/live/sEgyL5IOL2M…
#TaxReforms #BusinessGrowth #Competitiveness #FiscalPolicy #Nigeria

Fiscal Reforms Nigeria retweeted
There is NO VAT on the money you transfer. VAT is only charged on the banking fee or commission which has been the case since VAT was introduced in 1993.


Fiscal Reforms Nigeria retweeted
𝐁𝐚𝐲𝐞𝐥𝐬𝐚 𝐒𝐭𝐚𝐭𝐞 𝐀𝐝𝐨𝐩𝐭𝐬 𝐍𝐞𝐰 𝐇𝐚𝐫𝐦𝐨𝐧𝐢𝐬𝐞𝐝 𝐓𝐚𝐱 𝐋𝐚𝐰
Bayelsa State has joined the growing number of states that have enacted the Harmonised Taxes Law as part of the ongoing tax reforms aimed at eliminating multiple taxation and illegal tax collection.
We commend Bayelsa State for this important step, alongside other states where similar laws have been enacted, including Anambra, Ekiti, Gombe, Kogi, Nasarawa, Plateau, and Zamfara. Many more states are currently in the final stages of passing and gazetting the law.
This momentum marks the beginning of a more coordinated, transparent, and investor-friendly fiscal framework across the federation.
A transformative fiscal era is underway.
𝐆𝐨𝐝 𝐛𝐥𝐞𝐬𝐬 𝐍𝐢𝐠𝐞𝐫𝐢𝐚.

Fiscal Reforms Nigeria retweeted
𝐑𝐞𝐬𝐩𝐨𝐧𝐬𝐞 𝐭𝐨 𝐊𝐏𝐌𝐆: 𝐎𝐛𝐬𝐞𝐫𝐯𝐚𝐭𝐢𝐨𝐧𝐬 𝐨𝐧 𝐍𝐢𝐠𝐞𝐫𝐢𝐚’𝐬 𝐍𝐞𝐰 𝐓𝐚𝐱 𝐋𝐚𝐰𝐬
---𝘉𝘺 𝘗𝘳𝘦𝘴𝘪𝘥𝘦𝘯𝘵𝘪𝘢𝘭 𝘍𝘪𝘴𝘤𝘢𝘭 𝘗𝘰𝘭𝘪𝘤𝘺 𝘢𝘯𝘥 𝘛𝘢𝘹 𝘙𝘦𝘧𝘰𝘳𝘮𝘴 𝘊𝘰𝘮𝘮𝘪𝘵𝘵𝘦𝘦
We welcome all perspectives that contribute to a shared understanding and successful implementation of the new tax laws. We acknowledge that a few points raised by KPMG are useful, particularly where they relate to implementation risks and clerical or cross-referencing issues. However, the majority of the publication reflected a misunderstanding of the policy intent, a mischaracterisation of deliberate policy choices, and, in several instances, repetitions and presentation of opinion and preferences as facts.
𝐆𝐞𝐧𝐞𝐫𝐚𝐥 𝐨𝐛𝐬𝐞𝐫𝐯𝐚𝐭𝐢𝐨𝐧𝐬
A significant proportion of the issues described as “errors,” “gaps,” or “omissions” by KPMG are either:
- the firm’s own errors and invalid conclusions,
- issues not properly understood by the firm,
- missed context on broader reforms objectives,
- areas where KPMG prefer different outcomes than the choices deliberately made in the new tax laws, and
- obvious clerical and editorial matters already identified internally.
While it is legitimate to disagree with policy direction, disagreements should not be framed as errors or gaps. KPMG would have been more effective if the firm adopted a similar approach like other professional firms who engaged directly providing the opportunity for clarifications and mutual-learning.
It is equally important to distinguish between policy choices designed to achieve the reform objectives and proposals that merely represent a firm's preference.
𝐏𝐨𝐥𝐢𝐜𝐲 𝐂𝐡𝐨𝐢𝐜𝐞𝐬 𝐚𝐧𝐝 𝐂𝐥𝐚𝐫𝐢𝐭𝐲 𝐨𝐧 𝐑𝐞𝐟𝐨𝐫𝐦𝐬
1. Taxation of Shares and the Stock Market
Contrary to the presumption that the new tax provisions on chargeable gains would trigger a sell-off on the stock market, the fact is that the applicable tax rate on share gains is not a flat 30%. The tax framework is structured from 0% to a maximum of 30%, which is set to reduce to 25%. Furthermore, a significant majority of investors (99%) are entitled to unconditional exemption, with others qualifying subject to reinvestment.
The market's performance, which is at an all-time high with increased investment flow, demonstrates investors understanding that the tax changes will enhance the fundamentals of firms both in terms of profitability and cash flows. The sell-off narrative is unsubstantiated as any disposals in December 2025 would have benefited from the re-investment exemption or enhanced deductions under the new law.
2. Commencement Date and Transition
The suggestion to set the commencement date as the start of an accounting period (e.g., 1 January 2026) takes a narrow view of the complex transition issues. A wholesale reform affects myriad issues beyond the accounting period, spanning multiple periods, different bases of assessment (preceding year, actual year), as well as issues related to audit, deductions, credits, and penalties. Limiting the commencement to a single date for accounting periods would fail to address the intricacies of continuous transactions and other transition matters. KPMG’s proposal is therefore not a “gold standard” to be applied to all new laws as suggested.
3. Indirect Transfer of Shares
The new provision to tax indirect transfer of shares is a policy choice aligned with global best practices and BEPS initiatives. Its objective is to block a long-exploited tax loophole by multinationals and other investors, not to affect competitiveness. This is a common provision in international tax, and the assertion that it may affect the country's economic stability is disingenuous.
4. VAT Exemption on Insurance Premium
KPMG's point regarding a specific VAT exemption on insurance premium is technically unnecessary, as an insurance premium is not a "taxable supply" defined under the Nigeria Tax Act. Insurance relates to risk transfer, not the supply of goods or services subject to VAT. As this has always been the administrative and legal position, a specific amendment for exemption is academic. If it is not broken, don’t fix it.
𝐈𝐬𝐬𝐮𝐞𝐬 𝐑𝐞𝐟𝐥𝐞𝐜𝐭𝐢𝐧𝐠 𝐌𝐢𝐬𝐮𝐧𝐝𝐞𝐫𝐬𝐭𝐚𝐧𝐝𝐢𝐧𝐠 𝐁𝐲 𝐊𝐏𝐌𝐆
5. Inclusion of 'Community' in Definition
The concern about the inclusion of “community” in the definition of a ‘person’ but its omission from the charging section does not constitute a gap or ambiguity. In statutory interpretation, definitions provided in the law apply wherever the defined term appears, unless the context requires otherwise. Hence, ‘person’ and ‘taxable person’ are used in the charging section, and both definitions include ‘community.’ This approach is consistent with modern legislative drafting principles, which use comprehensive definitions to streamline operative provisions and avoid redundancy. This is similar to the inclusion of partnerships and executors in the definition but not under the charging section. The use of the word “includes” further signifies that the list of taxable persons is not exhaustive.
6. Joint Revenue Board (JRB) Composition
The composition and mandate of the Joint Revenue Board (JRB) are intentional. Its policy advisory role is specifically to provide a subnational tax and revenue perspective that complements the fiscal policy mandate of the Ministry of Finance. Its membership is appropriately limited to revenue-focused agencies, which is why it is called the Joint Revenue Board. This is a similar composition under which the former JTB operated effectively, and its functions remain consistent with the need for inter-agency coordination.
7. Distinction in Dividend Treatment
KPMG's analysis appears to mix the distinction between a foreign-controlled company and a foreign operation of a Nigerian company. Dividends distributed by a foreign company cannot be "franked" since no Nigerian Withholding Tax (WHT) would have been deducted. Section 162(1)(s) confers exemption on dividend, interest, rent, or royalty derived from outside Nigeria and brought into Nigeria through approved channels. The choice to treat dividends distributed by Nigerian companies differently from foreign companies is a deliberate policy choice, as they are fundamentally different for tax purposes.
8. Non-Resident Registration and Final Tax
The view that a payment subject to deduction as final tax should automatically exempt the non-resident recipient from tax registration misses a critical distinction. While the law conditionally exempts passive income from registration, the deduction of tax on non-passive income is not synonymous with an exemption from registration or filing of returns. The same way that residents are required to file returns on income such as interest (in the case of individuals) and dividend where WHT is final. Returns serve a broader purpose beyond solely generating tax revenue.
𝐊𝐏𝐌𝐆’𝐬 𝐏𝐫𝐨𝐩𝐨𝐬𝐚𝐥𝐬 𝐓𝐡𝐚𝐭 𝐖𝐨𝐮𝐥𝐝 𝐔𝐧𝐝𝐞𝐫𝐦𝐢𝐧𝐞 𝐊𝐞𝐲 𝐑𝐞𝐟𝐨𝐫𝐦 𝐎𝐛𝐣𝐞𝐜𝐭𝐢𝐯𝐞𝐬
9. Tax on Foreign Insurance Premiums
The proposal to exempt foreign insurance companies from tax on premiums from insurance written in Nigeria to deepen penetration, while local insurance companies continue to pay tax, would be detrimental to the domestic insurance sector. This would create an unfair and harmful competitive disadvantage for local firms in their own market. The current policy is designed to protect and promote local industry and ensure a level playing field.
10. Parallel Market Forex Deduction
The new law disallows tax deduction for the difference where a business buys foreign exchange in the parallel market at a premium over the official rate. This is a critical fiscal policy choice designed to complement monetary policy, strengthen, and stabilise the Naira. By removing the tax subsidy for patronage of the parallel market, the policy aims to reduce incentives for round-tripping and redirect legitimate FX demands to the official market. This is policy congruence, not an error.
11. VAT Compliance-Linked Deductibility
The non-tax deduction for taxable transactions on which VAT has not been charged is a necessary anti-avoidance measure. It removes the advantage that some taxpayers previously enjoyed by patronising suppliers who evade VAT. This is a matter of fairness and is squarely within the control of a business to manage, especially given the provision for the self-charge of VAT. It also ensures that responsible businesses play their part in promoting voluntary tax compliance across the ecosystem.
12. Progressive Personal Income Tax
While KPMG acknowledges the reform objective of fairness and progressivity, the firm disagrees with a top marginal tax rate of 25% for the highest earners. In reality, the effective tax rate can be as low as 22% for an individual earning billions a year simply by contributing 10% to pension. This rate is competitive when compared to many other countries, including Angola 25%, Egypt 27.5%, Ghana 35%, Kenya 35%, the U.S. (Federal) 37%, South Africa 45%, and the U.K. 45%. So, the rate is not “oppressive” or one that will negatively affect economic growth as claimed, rather it ensures progressivity without compromising competitiveness. From a broader policy objective perspective, the increase in top marginal rate for high income earners and the reduction in corporate tax rate is designed to address the existing higher tax burden associated with business formalisation.
𝐅𝐚𝐥𝐬𝐞 𝐈𝐧𝐜𝐥𝐮𝐬𝐢𝐨𝐧 𝐚𝐧𝐝 𝐅𝐚𝐜𝐭𝐮𝐚𝐥 𝐄𝐫𝐫𝐨𝐫 𝐛𝐲 𝐊𝐏𝐌𝐆
13. Police Trust Fund
The Police Trust Fund was signed into law on May 24, 2019, with a six-year lifespan under section 2(2) of the Act, which ended in June 2025. Therefore, KPMG's point that the new tax law should be amended to repeal the taxing section of the Police Trust Fund Act is needless, as the provision no longer exists.
14. Small Company Verification
The analysis concerning the tax exemptions for small companies affecting large companies' obligations is not a new issue or an inconsistency in the new law. The small business threshold was introduced via the Finance Act 2021. This issue pre-dates the current tax laws and should not be presented as an error or omission simply by virtue of a higher tax exemption threshold under the new law.
𝐖𝐡𝐚𝐭 𝐊𝐏𝐌𝐆 𝐋𝐞𝐟𝐭 𝐎𝐮𝐭
While acknowledging the objectives of the reform, KPMG could have highlighted the major structural improvements under the new laws, including:
- simplification and tax harmonisation,
- the scope for reduction in corporate tax rate from 30% to 25%,
- expanded input VAT credits for businesses,
- tax exemption for low-income earners and small businesses,
- elimination of minimum tax on turnover and capital, and
- improved investment incentives for priority sectors.
A balanced assessment would have recognised these transformative elements, among others.
𝐂𝐨𝐧𝐜𝐥𝐮𝐬𝐢𝐨𝐧 𝐚𝐧𝐝 𝐖𝐚𝐲 𝐅𝐨𝐫𝐰𝐚𝐫𝐝
The tax reform is the result of an extensive consultation with various stakeholder groups in addition to the legislative process that included widely publicised public hearings, avenues intended for all stakeholders including international firms to provide technical expertise at the formative stage.
In any comprehensive overhaul of a nation’s tax framework, clerical inconsistencies or cross-referencing gaps may occur, and these are already being identified within the government. The tax reform represents a bold step toward a self-sustaining and competitive Nigeria.
An effective review needs to connect identified gaps to clear policy intents and the reality of modern-day tax systems within the context of economic development and global competitiveness.
At this stage, the effectiveness of the tax law depends on administrative guidance, clarifications from the tax authority, and regulations to complement precise statutory provisions where necessary pending future amendments.
We urge all stakeholders to pivot from a static critique to a dynamic engagement model, which allows for clarifications and a productive partnership in the implementation of the new tax laws.
𝐂𝐨𝐥𝐥𝐚𝐛𝐨𝐫𝐚𝐭𝐢𝐧𝐠 𝐖𝐢𝐭𝐡 𝐓𝐡𝐞 𝐓𝐚𝐱 𝐎𝐦𝐛𝐮𝐝 𝐟𝐨𝐫 𝐅𝐚𝐢𝐫 𝐓𝐚𝐱 𝐀𝐝𝐦𝐢𝐧𝐢𝐬𝐭𝐫𝐚𝐭𝐢𝐨𝐧
Yesterday, the Presidential Fiscal Policy and Tax Reforms Committee (PFPTRC) held a constructive meeting with the Office of the Tax Ombud (OTO) as part of ongoing efforts to support effective implementation of the tax reforms.
The Office of the Tax Ombud is an independent and impartial body established under the new tax laws to protect taxpayer rights, resolve complaints quickly and fairly, and build trust in the tax system through mediation and advocacy.
Our engagement focused on collaboration with the Tax Ombud given his critical role in ensuring that the reforms deliver not just better tax systems, but a fairer and more responsive tax administration for taxpayers.
#TaxReformsNaija #FairTaxAdministration
#TaxpayerRightsMatter #TaxOmbudNigeria
#FiscalPolicyReforms


𝐄𝐧𝐠𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐰𝐢𝐭𝐡 𝐭𝐡𝐞 𝐍𝐚𝐭𝐢𝐨𝐧𝐚𝐥 𝐀𝐬𝐬𝐨𝐜𝐢𝐚𝐭𝐢𝐨𝐧 𝐨𝐟 𝐍𝐢𝐠𝐞𝐫𝐢𝐚𝐧 𝐒𝐭𝐮𝐝𝐞𝐧𝐭𝐬 (𝐍𝐀𝐍𝐒)
We had a productive engagement with the National Association of Nigerian Students (NANS) and its leadership from tertiary institutions across the country.
The discussion focused on the rationale for the reforms, their core objectives, and the benefits for students and all young Nigerians. We highlighted how the reforms reduce the tax burden on average Nigerians and remove tax-related barriers to opportunities such as business process outsourcing (BPO) and other emerging sectors for young people.
The students commended the thoughtfulness of the reforms and welcomed the clarity that the reforms are not designed to target the poor, but to provide relief and opportunity contrary to the widespread misinformation.
Following the engagement, the students resolved to call off their planned protest scheduled for 14 January 2026 and instead collaborate with the government to sensitise students and other citizens nationwide.
Constructive dialogue works. Collaboration not confrontation. Nigeria is winning.
-𝑷𝒓𝒆𝒔𝒊𝒅𝒆𝒏𝒕𝒊𝒂𝒍 𝑭𝒊𝒔𝒄𝒂𝒍 𝑷𝒐𝒍𝒊𝒄𝒚 𝒂𝒏𝒅 𝑻𝒂𝒙 𝑹𝒆𝒇𝒐𝒓𝒎𝒔 𝑪𝒐𝒎𝒎𝒊𝒕𝒕𝒆𝒆
