

A smart investment strategy is built with taxes in mind.
San Francisco, CA
Joined January 2022
- Tweets748
- Following41
- Followers1.1K
- Likes421





Happening TOMORROW! Join us: luma.com/74x2a2sv


Most of your wealth in one stock? Holding keeps you concentrated. Selling could mean a big tax bill.
Join Frec CEO @maladham and @DreNader of FAANG FIRE on Oct 28 at 12pm PT to learn how to diversify tax-efficiently, whether you’re still at the company or not.
Register: luma.com/74x2a2sv

Most of your wealth in one stock? Holding keeps you concentrated. Selling could mean a big tax bill.
Join Frec CEO @maladham and @DreNader of FAANG FIRE on Oct 28 at 12pm PT to learn how to diversify tax-efficiently, whether you’re still at the company or not.
Register: luma.com/74x2a2sv
Frec retweeted

I just came back from @money2020, and the energy in the room made it very clear: fintech is not dead. Not even close.
Ribbit Capital, one of fintech’s leading investment firms, put it this way: “Fintech, as we’ve known it for the past decade, is dead.” Its investor presentation featured a tombstone: “Fintech, 2012–2023.” I learned about this while listening to the recent Invest Like the Best episode featuring Nubank founder David Vélez.
Ribbit’s point was that the first wave of fintech has matured. That wave made banking, payments, and investing easier to access through better digital products. In their view, the leading companies now have the scale and brands to keep winning, leaving less room for new entrants.
From where I sit as a founder, there’s still plenty of room for new companies to serve customers whose needs aren’t being met. The next generation of winners is still being built.
History is a good reminder of how much opportunity can remain in markets that seem mature:
• 2004: Bessemer passed on Facebook. In the firm’s own telling: “Kid, haven't you heard of Friendster? Move on. It's over!”
• 2007: Paul Graham published “Microsoft is Dead.” Azure alone passed $75 billion in annual revenue in 2025.
• 2014: Fred Wilson wrote that “the social media phase of the Internet ended.” TikTok later reached a billion monthly users.
• 2015: Bill Gurley questioned Instacart’s economics. Today, it’s a publicly traded company worth roughly $12.5 billion.
Even the best investors can underestimate what teams will build and customers will adopt.
Particularly in consumer fintech, we are nowhere near done democratizing access.
At @frecfinance, we’re making sophisticated investment strategies accessible to more people. We started with direct indexing and borrowing. Now customers are asking for new strategies they've heard about but can't easily access.
Elsewhere, there are interesting companies working to make estate planning and tax preparation simpler and more accessible. There’s room for new approaches, too. Look at Silo Markets bringing rewards points to stock portfolios.
Even Thomas Peterffy , the founder of Interactive Brokers, recently led a $7 million seed round for @Aries, a new trading app.
AI could make personalized financial advice accessible to far more people. And I believe that will create entirely new apps where people manage their finances, not just new features inside today’s established platforms.
There’s still so much to do to make people’s financial lives better. Our job is to solve real problems and give people products they love.
Customers will decide who wins.
Frec retweeted
My sister messaged our family group: “Mo are you aware of this?? Frec is in a Netflix documentary!”
I had no idea.
Sure enough, our Market St. billboard—“Is your wealth concentrated in company stock? Meet Frec”—shows up in the first minute of Netflix's Instadocs: AI Gone Wild.
The documentary opens with the line: “There’s this saying, the future happens first in San Francisco.” The camera pans past a Waymo, then Frec’s billboard.
The billboard was part of our first experiment with outdoor advertising. The ROI is hard to measure, but I’m counting our unexpected cameo in a Netflix documentary as a win.
As for the episode’s narrative, I see things differently. I believe society will figure out the right guardrails to make AI work for us, helping individuals and organizations become more productive. I’m optimistic those benefits will reach every corner of the economy, creating more wealth and opportunity than we’ve ever seen before.
And as AI creates a new wave of wealth, Frec will be here to help people manage it effectively so they can focus on building the future.
We’re flattered to make the cut. Thanks, Netflix!

Frec retweeted
The Treasury and the IRS just put some ETF-conversion strategies involving Exchange Funds under scrutiny, as outlined in Notice 2026-62.
In the same notice, they acknowledged that traditional capital loss harvesting can reduce taxes in a manner “consistent with the intent of Congress.”
Frec Diversify is built around capital loss harvesting, not ETF conversions. It’s a scalable alternative to Exchange Funds, designed to gradually diversify concentrated stock through capital loss harvesting. Instead of contributing your shares to a pooled fund, you keep ownership of them in your own Frec account.
We build a long extension that fills in the rest of your chosen index. A short extension helps hedge some of the risk from your concentrated position.
With those extensions in place, capital losses are generated as we rebalance the portfolio. Those losses can offset gains as we gradually sell down your concentrated position, working toward its target weight in the index.
You choose your index and can customize your holdings. There’s no seven-year holding requirement and no waiting for a fund to assemble the right mix of other investors’ contributions. The portfolio is built around your preferences - not around what a pooled fund happens to need.

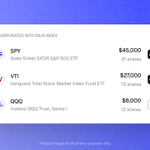
A few weeks ago we rolled out ETF funding for Frec Classic and Long short direct indices, so you can contribute ETFs you already own, like VOO, VTI, or SPY, instead of only cash. Since then we've gotten a lot of questions on exactly how it works.
We just published the full breakdown, covering which ETFs are supported, how it works, what happens to your ETF position once it's inside your index, and more.
Read it here: frec.com/resources/blog/usin…

Frec retweeted
What happens to ETF inflows when AI agents start managing our money?
This weekend, I read Apollo Global Management, Inc. Chief Economist Torsten Slok's note on a potential “agentic bank run.” Once people trust agents to move money, idle cash could shift from low-yield checking accounts into higher-yield alternatives.
Could a similar shift happen in investing from index ETFs toward direct indexing in taxable accounts?
Owning the underlying stocks opens up more opportunities to harvest capital losses, which can be used to offset capital gains, with unused losses carried forward. You can also customize holdings and vote your shares.
Switching from one index ETF to another in a taxable account means realizing any embedded gains in the shares you sell. With direct indexing, you can retain overlapping stocks and adjust the rest, potentially reducing the tax cost of switching indices.
The tax benefits can extend into retirement withdrawals, too: unused losses can offset gains as you sell investments to fund spending.
For many investors, ETFs are the default. A trusted agent could weigh the tradeoffs and put the next dollar into direct indexing.
Frec retweeted
Our $100k demo account gained about $19k in roughly a year, net of financing and management fees. It uses a value-tilted 140/40 direct indexing strategy based on the Russell 1000. For comparison, a $100k investment in a Russell 1000 ETF over the same period would’ve gained about ~$445 less. And here’s the kicker: it also harvested ~$27k in capital losses while appreciating in value. This is a real account, not a backtest - anyone can inspect every position and trade on our website (link in my comment). It’s worth noting that the long short direct index carries a different risk profile and can expect a tracking error of ~1.5%.
We chose a value tilt because many of our customers work in tech and already have significant exposure to growth stocks. We wanted to demonstrate how they could lean into value while maintaining broad market exposure.
Those $27k in harvested losses can offset capital gains elsewhere. Someone selling appreciated company stock, for example, could use $27k of harvested losses to offset that amount in gains. At a combined 30% tax rate, that could defer a ~$8k tax bill, leaving that money invested in the market instead.
We made 140/40 available starting at a $100k minimum, and customers can get started in a few minutes. We also offer 200/100 and 250/150 versions. The additional leverage allows for a stronger factor tilt and creates more opportunities to harvest losses.

Disclosures: Nasdaq®, Nasdaq-100®, are registered trademarks of Nasdaq, Inc. (which with its affiliates is referred to as the “Corporations”) and are licensed for use by Frec. The Product(s) have not been passed on by the Corporations as to their legality or suitability. The Product(s) are not issued, endorsed, sold, or promoted by the Corporations. THE CORPORATIONS MAKE NO WARRANTIES AND BEAR NO LIABILITY WITH RESPECT TO THE PRODUCT(S).
Frec retweeted
Most have heard of tax-loss harvesting. But a different version is attracting the Treasury's attention: ordinary-loss harvesting. It aims to offset ordinary income, like business earnings and, within limits, salary income. Meanwhile, gains can receive more favorable capital gains treatment.
This is different from traditional tax-loss harvesting which uses capital losses to offset capital gains, plus up to $3,000 of ordinary income each year. Frec’s Long short portfolios harvest capital losses too. One high-profile example of capital loss harvesting: The Wall Street Journal reported that President Trump’s investment accounts use direct indexing.
Ordinary-loss harvesting seeks to go much further. Treasury officials have described sales pitches advertising a $300,000 ordinary loss on a $1 million investment.
A new Tax Notes article by NYU law professor @DanielJHemel explains the distinction, using AQR’s TA Delphi Plus fund as an example of ordinary-loss harvesting.
Hemel traces the strategy to a “temporary” Treasury exception from 1988 - still in place 38 years later. It lets investors use ordinary losses from certain funds to offset income from businesses they actively run, even when they don’t help run the fund. His proposed fix is to remove that exception through Treasury’s rulemaking process.
At @frecfinance, our Long short and Diversify strategies harvest capital losses. They do not pursue ordinary-loss harvesting. We’ve worked with tax counsel in structuring these strategies, and we’ll continue monitoring developments.
These distinctions matter in how the topic is covered. CNBC's recent reporting on tax-aware Long short strategies included an “IRS crackdown” section, while noting that officials hadn’t named those long short tax-aware strategies specifically.
We’d love to see coverage make clearer which products and which types of losses are under scrutiny, especially in headlines. That helps investors understand which risks may apply to them.

Now out in @TaxNotes: How Treasury created "carried interest on steroids" -- a tax strategy that allows high-net-worth investors w/sufficient liquidity to transform potentially unlimited amounts of active business income into long-term capital gain ... 1/
Frec retweeted
“You guys found the perfect crowd. We’re all rich dads, and this is the ultimate rich dad joke.”
That was one attendee’s reaction to our “Long short” shirts at this year’s All-In Summit. 😂
@frecfinance was back as a sponsor this year. That’s Nolan Pecci in the photo: one long sleeve, one short sleeve. We took product marketing literally.
There’s a more serious reason we like this audience. We’re building Frec for people who want to stay involved in managing their wealth. They want access to sophisticated investment strategies without having to manage every trade themselves or hand their entire portfolio over to an advisor.
The team’s report from the booth: “The shirts are a hit.”
Thanks to @chamath, @Jason, @DavidSacks, and @friedberg for having us back. And to Nolan for committing to the outfit.

Spotted at #AllInSummit from @theallinpod: Nolan in a “long short” shirt, very excited to talk about direct indexing and, of course, long short direct indexing!
Come find the Frec booth in the Tech Frontier, check out our live demo, and get all your questions answered.
Can't make it? Schedule a call with our team here: calendly.com/frecdemo/frec-d…

LET’S GOOOOO

Frec has crossed $1.5 billion in customer assets. That’s another $500 million since we announced $1 billion just a few months ago 🚀🚀🚀
We’re marking the occasion with @Nasdaq . Thank you to the Nasdaq team for featuring @frecfinance on the tower in Times Square! We’ve also been working together on something new for Frec customers that we’re excited to share soon.
Thank you to our customers for trusting us with their money, and to the Frec team for getting us here!

Frec retweeted

Added a US small cap direct index to my plan in Dec of last year.
Very happy with the results. Gets a bit more in losses than my S&P500 direct index.
Up 18.58% YTD and it has $5,363 in losses harvested YTD.
I've posted about direct indexing a handful of times in the past and why I added it to my plan. If you're interested in learning more and whether or not it might be right for you, I did a past webinar discussing why I love it, who it might be great for, etc. Just comment below or DM me and I'll send you the webinar replay

Frec retweeted

when the investor starts looking like the founder ….
with the awesome @maladham @frecfinance hq in sf … of course on HOWARD street

Frec retweeted
Yesterday, Moderna rose roughly 177% in a single day after positive Phase 3 results for its cancer vaccine.
Anyone short Moderna took real losses. So our quant team immediately looked at Moderna exposure across Frec's Long short portfolios.
This is why risk controls matter.
When we construct a Long short portfolio, no individual short position is allowed to become a meaningful concentration. Positions are diversified and capped at 1-2% of the portfolio at construction, so even an extraordinary move in a single stock has a limited impact on the overall portfolio.
Long short direct indexing does introduce incremental risk versus a class direct index. A classic direct index targets roughly +/- 0.8% of tracking error, compared with roughly +/- 1.5% for our 140/40 strategy. The increase in tracking error risk is deliberate: accept a somewhat larger risk budget in exchange for factor exposure, the potential for excess returns, and substantially more opportunities to harvest tax losses.
The important part is that the additional risk is engineered and monitored rather than taken blindly.
This is what makes Long short direct indexing such an interesting financial product. We think most index investing will eventually move toward direct indexing over time, and a meaningful share of it will use Long short extensions.

Our latest update can help you meet strategy minimums with assets you already hold, create more chances to harvest losses as your portfolio grows, and consolidate positions more tax-efficiently.
Previously, if you wanted to fund or grow a direct index with existing ETFs, we'd sell them outright and use the proceeds. Now you can use eligible ETFs to fund or contribute to an existing direct index, while keeping as many of your original ETF shares as possible.
To start a new direct index, head to the Invest tab. To add to an existing one, select the direct index from the Overview page, click Transfer, then Move stocks.
Full announcement in the comments.


Frec retweeted

I disagree with this take.
Tax loss harvesting is most definitely a strategy.
Blindly harvesting a loss is overrated.
Understanding how to get the best after-tax benefit from something like TLH, especially as options have evolved via purposeful direct indexing is quite literally a strategy.
I see it implemented on a daily basis.

Frec retweeted
the talented @matt_levine mentions frec in his no spacex piece as well
bloomberg.com/opinion/newsle…
