

AI compute & power infrastructure analyst. Tracking data center expansion, energy demand, and high-performance computing developments.
Joined October 2024
- Tweets1.8K
- Following99
- Followers981
- Likes1.5K



Pinned Tweet
AI, HPC, and the bullish case for data centers:
I believe that the big narrative of 2025 and beyond will continue to be AI. I believe that an undervalued sector in the AI field is AI/HPC data centers. The market was caught off guard by the explosive growth of AI in 2024, and what the market doesn’t recognize is that the new demand for power and compute far outweighs the supply. At this point, to build a new datacenter, it would take multiple years to complete the project, from acquiring the land to obtaining the proper permits, securing the power and hardware, and building out the actual data center. So there's all this new demand for data centers, and the new supply can't be built out quickly enough to meet that demand. This leads to an opportunity in the market. There are a variety of Bitcoin miners that have the land, buildings, and power contracts that can be reallocated to AI/HPC hyperscalers. A company in this sector that is growing the fastest and at the highest rate of efficiency is IREN Limited $IREN.
There has already been one massive deal in the sector. CoreWeave has a 12-year, $8.7 billion deal with Core Scientific (CORZ) to gain access to 500 MW. That’s $750 million a year. This deal was also most likely not as good as it could have been, as Core Scientific signed this deal out of bankruptcy. Despite the nature of this deal, the other Bitcoin miners that have the same AI/HPC capacity that CORZ has have not really been effectively re-rated. My personal favorite in the sector, IREN Limited (IREN), currently has 510 MW, with 400 MW more coming by the end of H1 25, 1.4 GW coming by Q2 2026, and another gigawatt coming down the road. To put that into perspective, 2.4 gigawatts, which IREN is projected to have in the near future, is enough to power roughly 2 million homes. If they were to announce a similar deal to CoreWeave, I would expect it to clear $10 billion. The strong possibility of such a deal has not been priced into IREN’s stock. They are currently trading at $10.97 with a market cap of $2.36 billion as of 1/9’s close. This valuation comes from their Bitcoin mining and cloud services businesses, which brought in roughly $114.3 million in revenue ($85.5 million in profit) in Q4. Annualized, that’s $457.2 million ($341.7 million in profit). So using Q4’s numbers, the stock is trading at a trailing P/E of roughly 6.9x. Remember this valuation is not factoring in any value coming from AI/HPC. The average P/E of the tech sector is 35-40x, with some stocks trading as high as 50x. I believe with IREN’s expansion plans and their history of delivering on their estimates that they could easily reach $75-100 million in monthly profit in 2025 on their Bitcoin mining and cloud services business alone. Calculating $75 million a month and assigning a meager trailing P/E of 10, the stock would be valued at $9 billion (a 4x from current prices). Taking a more generous stance and calculating $100 million in monthly revenue and a hyperscaler deal similar to CORZ, this stock could be bringing in $2+ billion in profit a year. If we take this projection and factor in a more forward-looking P/E of 20, then this stock could reach a market cap of as high as $40 billion (a 17x from here).
In short, I believe that IREN is undervalued and is an incredible investment opportunity at these prices.
$BTC $HUT $WULF $CIFR
Kerdos Capital retweeted

We started shipping the Nvidia H100 in 2022.
A year ago it rented for $1.96/hour.
Today: $3.10.
+58%, on a chip that was supposed to be obsolete by now.
So much for GPU depreciation.

$WULF $CIFR Riot just reset the market for these names and I don't think it's priced in at all... Last week $RIOT leased all 910MW at Corsicana to Anthropic for 15 years at $130 per kW a month with 3% annual escalators.
$130 x 12 = $1.56M per MW per year
And Riot only has to put up about $6M per MW to get it, which they say is about half the capital of a typical full build. That's a 33% yield on cost. Back in August of last year WULF's Fluidstack deal worked out to about $1.36M per MW, so income per MW is up about 14% in 15 months and the capital needed to earn it just got cut in half.
So what does that make WULF and CIFR worth? Well... I took every unsigned site at both companies and valued it as if it was built and paying rent today on Riot's terms. Where they'll do more of the build themselves I raised both the cost and the rent (about 10% more income on every extra dollar they put in), and I have rent climbing a modest 3% a year until each site signs. Then I discounted each site back 10% a year for how long it realistically takes to reach full rent, added 3 to 6 months of delays, and weighted it by the odds it actually happens. 95% for Reveille and Ulysses since those can sign basically any time, 85% for Muskie phase one, 80% for Colchis, all the way down to 20% for Apollo which is still just an option on land. I also assumed both fund 10% of construction by selling stock (which at this point is likely), about 9% more shares for WULF and 12% for CIFR.
I get about $27 for WULF and about $30 for CIFR against $13.04 and $7.15.
The part I think people are missing with CIFR is Colchis. 1GW with a conditional base load classification already in hand, call it 700MW of critical IT...
700MW x $1.67M = $1.17B a year
From one site.
Even at 80% odds, with a delay, and waiting until 2029 for full rent I have that worth about $8.50 a share. More than the entire stock price. Only 13% of what I think CIFR is worth is signed today so yes it's the riskier of the two, but that's also exactly why it has the most room. WULF is the safer one with 31% already signed and Google standing behind the Anthropic lease in Kentucky.
Out of roughly 474GW asking to connect to the Texas grid only about 9.5GW has been cleared to energize. That's 2%. Power is the scarce thing here and these two are sitting on a lot of it. December 10th is the date to watch...


$CIFR clearly does things the right way.

The disconnect between $IREN and $NBIS today is likely whoever is still listening to Citrini covering their NBIS shorts and moving to shorting IREN. More fuel for the recovery.


JUST IN: Citrini Research advises clients to cover $NBIS short position and to go short $IREN instead.
"One quick swap we are making is $IREN for $NBIS on the short leg of the neocloud pair mostly to derisk on earnings (IREN announced and popped harder than the sector today, NBIS earnings is next week). IREN is also more stretched in balance sheet, which matters since financing reflexivity is a huge part of this."

I'm long $DFDV
The thesis: The next wave of AI is agentic. I think agents will be the biggest theme of 2027, and the rise of Muse and Instinct makes that obvious. Agents will need to transact and trade, and legacy rails won't work for that. They'll use crypto, and $SOL is the best chain for it.
Alpenglow went live Oct 21 and targets ~150ms finality, down from ~12.8 seconds. That's under a blink of an eye, which is what agent-to-agent payments need. Agents open crypto to a new market of millions of participants.
Tokenization of real-world assets and legacy markets keeps growing too. I expect all of this to land alongside a crypto bull market as funds rotate back in.
Why $DFDV: It's a Solana treasury company.
- Holds 2,609,829 SOL, worth ~$228.1M
- Market cap is $129.56M, or 0.57x the value of its SOL before debt
- Adds SOL every week, including 8,881 SOL this week
- The CHAD preferred hit par and has held it for 48 days since its debut, giving DFDV another way to grow the treasury
Model (SOL = $350, 1.5x NAV)
Assumptions:
- Starts with 2,609,829 SOL
- Adds 5,336 SOL a week from staking (the pace of the last two weeks)
- Plus SOL bought with CHAD preferred proceeds, about $310k a week in the base case
- SOL rises from $87 to $350
- Subtract SOL-denominated loans and CHAD preferred
- Convertible notes convert to shares (conversion price is $23.11)
- Value the company at 1.5x NAV
Results:
Without CHAD
SOL held: 2.89M
Value at $350: $1.01B
NAV: $801M
At 1.5x NAV: $1.20B
Per share: $34.05
Base CHAD
SOL held: 2.97M
Value at $350: $1.04B
NAV: $814M
At 1.5x NAV: $1.22B
Per share: $34.61
High CHAD (3x base)
SOL held: 3.14M
Value at $350: $1.10B
NAV: $841M
At 1.5x NAV: $1.26B
Per share: $35.73
DFDV trades around $3.38 today.
Not modeled: share dilution from the ATM. Cash isn't disclosed, so I used $0. Q3 earnings on Nov 12 will update the numbers. Not investment advice.
Model (SOL = $350 in 52 weeks, 1.5x NAV)
No CHADBase CHADHigh CHAD
SOL held2.887M2.971M3.139M
Gross value at $350$1,011M$1,040M$1,099M
Less SOL-denominated loans-$197M-$197M-$197M
Less CHAD notional-$13M-$29M-$61M
NAV$801M$814M$841M
1.5x NAV$1.20B$1.22B$1.26B
Per share$34.05$34.61$35.73
Today’s price is ~$4.18, so the base case is about 8x.
How I built it
Organic growth: 5,336 SOL a week, matching the last two weeks’ increases. It fits staking, as you guessed.
CHAD: The extra 3,545 SOL this week is about $310k a week at today’s price. I used that as the base case and 3x as the high case. I bought CHAD-funded SOL along a straight-line price path from $87 to $350. Those dollars buy fewer SOL as the price rises. This is one week of data, and I can’t confirm the CHAD source.
Net debt: The ~$126M of converts converts to shares at $23.11, and the stock would be well above that, so I treated them as equity (35.3M fully converted shares). Treating them as debt on 31.0M shares gives $33.31 in the base case.
SOL-denominated loans: The 562,000 SOL comes from a company deck (a pre-Oct 5 figure) and re-prices with SOL, so it grows from ~$49M today to $197M. The company says borrowings have been reduced since, so this is a bit heavy.
Cash: Not disclosed, so I used $0. Each $10M of cash adds about $0.43 a share.
Not modeled: Common-share dilution from the ATM that funds ~$27M a year of cash costs. Q3 results on Nov 12 will update debt, cash and shares, and I can rerun the model then.
For other SOL prices, per share at 1.5x NAV is about $14.50 at $150, $19.50 at $200, $24.60 at $250 and $44.60 at $45

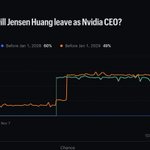
$NVDA these prediction markets accounts posting markets with less than $5,000 in volume as if they're actual market odds is criminal.


BREAKING: Nvidia CEO Jensen Huang admits to an extramarital relationship with a Chinese spy
75% chance he's out as $NVDA CEO before 2028


Readers added context they thought people might want to know
Huang admitted to an extramarital affair in a memo to Nvidia staff but did not say it was with a Chinese spy. Reports of her suspected spying come from US intelligence; the company board launched a separate investigation.
nvidianews.nvidia.com/news/statement… theverge.com/ai-artificial-… techcrunch.com/2026/11/08/nvi…


According to Polymarket for the "AI bubble" to "burst" 3 of the following have to happen:
- NVIDIA Corporation (NVDA) closing stock price is down 50% from its all-time high.
- iShares PHLX Semiconductor ETF (SOXX) closing stock price is down 40% from its all-time high.
- OpenAI, Inc. or Anthropic PBC declares bankruptcy.
- OpenAI, Inc. is acquired.
- H100 rental price falls to $1.00 or lower for five consecutive days, as shown on the SiliconData Silicon Index at: silicondata.com/products/sil….
- Major AI Hardware Supplier Collapse: Taiwan Semiconductor Manufacturing Company Limited (TSM), ASML Holding N.V. (ASML), Broadcom Inc. (AVGO), Arista Networks, Inc. (ANET), or Super Micro Computer, Inc. (SMCI), closing stock price is down 50% from its all-time high.
Have a hard time imagining any of these let alone three happen before June.
$NVDA $AMD $ANT $MU $META $MSFT $GOOG


$CIFR good insights from Tyler on how Cipher is already implementing Goverernor-elect Hinojosa’s policies.

1/ Congratulations to Governor-elect @GinaHinojosaTX on her historic win. Many of the priorities outlined during the campaign are ones @CipherInc has already built into how we operate in Texas. A few thoughts below.

Exactly. She wants them to pay their way but doesn’t want to lose the jobs and revenues. As long as the data center companies are willing to work with her I think they’ll actually have a very good relationship.
$IREN $CIFR $HUT

The governor-elect of Texas, Gina Hinojosa, has explicitly said that all currently permitted datacenters in Texas will be allowed to finish construction. This essentially covers all of the 2027 and likely well into 2028.
She is going to pass laws that ensure that all *newly* permitted datacenters going forward for delivery in 2028/2029 will pay taxes, commit to no increase in power prices for consumers, don’t impact water availability for people, be constructed with union labor and give “Texans a seat at the table.”
Sounds reasonable. She doesn’t want to lose a lot of good blue collar jobs and property taxes for small towns in rural Texas.
Datacenter commentary starts at 6:30 in this interview.
Also attaching her official campaign position from her website in the next post.
Sidenote: After watching a bunch of her speeches and interviews, I do think she is a political talent and probably has a future in national politics.
youtu.be/D-T6H3b8ZeE?is=mEWu…

9
687

$CIFR everyone seems to think it'll go to $5 after earnings tomorrow. I loaded up on $20 calls for March. Either the crowd is right or I'm about to make a killing.

8
581


$CIFR for those who have been in the name for a while they'll remember the pesky $8 level. It took almost 14 months to finally break through that resistance. It makes almost to much sense for that level to be finally retested after all this time.


$IREN this would be an ideal spot to form a local double bottom on descending volume. I'm targeting a bounce here and a run back towards the $49 resistence. $46.5 3DTE Calls are seeing some volume today which might be another indication of a local bottom.
