

Seeding some of the best emerging managers and fund innovators in venture. A more diversified & DPI-focused way to pursue venture-like returns.
Joined January 2024
- Tweets61
- Following12
- Followers20
- Likes39



Pinned Tweet
Founders of the top investment firms tend to absorb new ideas and react quickly. They care less about hierarchy or credentials and more about whether someone sees where the world is going before consensus forms. The best investors will listen to an intern, famous founder, or outsider alike if the insight is real.
Firms that follow the market often over-index on status, pedigree, and consensus validation, which can cause them to miss larger shifts underneath the surface. You can usually tell who the real players are within just a few interactions.
Wanted: Mavericks.
mav·er·ick /ˈmav(ə)rik/ noun
An independent-minded person who refuses to conform to conventional ideas, rules, or expectations.
Venture capital was built by mavericks. Here’s to the next generation.
Incredible time at the Bridge Asia Summit in Singapore meeting LPs and GPs from across Asia. Many great conversations on geopolitics, shifting capital allocations, and more!

Perpetual Dissatisfaction
We see it in the most enterprising investors, too. It’s what makes the AUM debate complicated: some of the best managers can keep landing new opportunities and expanding them without losing their original edge & hunger.

@gokulr describes two patterns he has seen in founders: persistent dissatisfaction and expanding ambition.
Reaching a milestone can redefine the next goal.
From Tech Fit Talks with Ethan Lockshin.
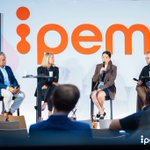
Great first @IpemMarket in the books! It was so much fun participating in the Venture & Growth Summit in Paris and joining a panel on backing emerging managers in venture capital globally.
Super interesting to hear so many of the same themes we’re thinking about in venture capital, from liquidity, secondaries, AI to better alignment between LPs & GPs, echoed across private markets.

Main Character Capital retweeted
The next decade belongs to the innovators
Are private markets becoming more idea constrained than capital constrained? We think so.
The best investors never seem to run out of ideas about the future. As competition crowds in, they reinvent themselves and, better yet, create what’s next.
🤖 Made with AI

The next decade belongs to the innovators
Are private markets becoming more idea constrained than capital constrained? We think so.
The best investors never seem to run out of ideas about the future. As competition crowds in, they reinvent themselves and, better yet, create what’s next.
🤖 Made with AI
The Illusion of Easy SPV Returns
Many investors overestimate their ability to pick winning co-investments and SPVs. If it were easy, every venture fund would be returning a 3–5x.
Remember, a unicorn valuation is not an exit. According to PitchBook, nearly 40% of U.S. unicorns have been held for at least nine years. And per Crunchbase, at the 2025 pace of exits, it would take 30 years for the current backlog of U.S. unicorns to go public or be acquired!
The following truism was drilled into our heads in finance class. It is more relevant than ever in venture capital today, especially when you account for survivorship bias.
Many fortunes were built when the industry had only a dozen serious players. Today, thousands of investors are competing for the same limited number of consequential deals each year.
At @MainCharacterHQ, we are looking for pioneers creating new games, not repeating old playbooks.
🤖 Made with AI

The game of venture capital and the game of backing venture capital funds are both power law games. If a 5x outcome seems out of reach, it may be worth asking whether you're playing the right game. A deal-by-deal SPV strategy may be a better fit than venture fund management.

Investor Tiers: True or false?
S-tier players want more S-tier players. They aren't threatened by excellence; they know it elevates everyone's game.
A-tier players track S-tier players closely. They study them, mirror them, and sometimes mistake proximity for mastery.
B-tier players regurgitate information, repackage it as "unique insight," and confuse curation with insight. They optimize for popularity & visibility.
C-tier players become flying monkeys. They amplify narratives, uphold the idea du jour, and attack others without ever stepping into the arena themselves.
To all the Main Characters whose best moves are still ahead. Here’s to making the next twenty years your highest scores yet. We can’t wait to see what you do next.
How do we move more people from market followers to category creators?
By changing incentives. By rewarding originality.
Originality is one of the rarest assets in investing. It takes the imagination to envision a different future, the judgment to distinguish possibility from probability, and the courage to commit while the evidence is still incomplete.
In this day and age, it can sometimes be hard to remember the purpose of venture capital.
At @MainCharacterHQ we believe the objective is simple:
1. Deliver superior returns to LPs.
2. Back important innovations before the rest of the market believes.
3. Repeat the process at scale without compromising either of the first two.
Everything else, the logos, the SPVs, the fees is a means to that end.
Access vs Selection
The last decade of VC was defined by access. The next decade (age of AI) will be defined by discernment and selection. All of us are drowning in access to SPVs & startups. What you pay an elite fund manager for is their superior filtering, due diligence and risk taking engine built up from years of trial and error & pattern recognition.
Risk taking is required: Not too much, not too little, just right!

Top quartile is table stakes. In venture capital, the real challenge is identifying managers capable of top 5% outcomes. The dispersion gap between top-decile and top-5% performance is often so substantial that it rivals the gap between average and top-decile managers.
Courtesy of @carta

Going from Fund to Franchise
Only ~1.7% of venture firms go from Fund I to franchise. The odds are comparable to a startup progressing from seed stage to IPO. That’s why anchor investors matter so much. LPs increasingly need to think more like investors themselves. From identifying the next generation of firms and domains early to helping firms institutionalize and improve in their formative years, it’s far from a passive role.
Courtesy of @KauffmanFDN Zero to Four report

Interesting study on the network advantage emerging GPs have over individual team members at larger firms.
While GPs spin up or spinout for a number of different reasons - it’s clear that running your own firm requires elite business development skills and network strength as that skill is put to the test on a daily basis.

Manager and Market Selection
We believe in taking a more anthropological approach to both market and manager selection.
We prioritize the market followed by the team. Markets can be niche, but they need to be growing. Expanding markets create the room for exceptional investors to build enduring firms and to back enduring companies.
We prefer to observe people in their natural habitats, paying close attention to how they treat people they think don’t matter, and understanding the incentives that drive their behavior. Venture is not linear and requires tremendous consistency and integrity over long periods of time.