








Pinned Tweet
$LQDA Courtesy of my friends Fable and Astra. I have tried to wrap my head around Andrews on-sale bar ruling for Claim 1 and I am strongly convinced he has got it wrong. Please refer to pages 41 to 50 of the Trial Opinion and decide for yourself.
$CBRS Has the benefit of both lower capex/MW and higher revenue/MW
Why?
They are vertically integrated so they pay the cost price of the chip and they sell a premium product ultrafast inference speed
This makes them the best neocloud to own

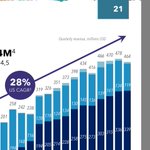
$LQDA We were doing +$40m a quarter and then in Q3 we did +$50m and October is tracking at 75% of that so ~$40m. Just going back to what it was
1
21
1,784

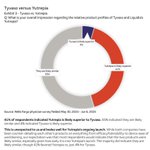
$LQDA If 60% of patients are PAH and you believe 50% of PH-ILD patients are PAH phenotype. Then 80% of $220m is PAH.

$LQDA Just came across another expert call. An academic PH centre thinks 50% of its PH-ILD patients can be reclassified as PAH. There are conversations ongoing with PH specialists across the country on how to do this. Their perspective on insurance is that it makes no difference to them as both drugs are priced the same. Longer term though ILD patients will be referred in already on Tyvaso and it may be easier to just remain on that.
$LQDA That was a great call. I do want to point out on L606 that just because mgmt believes it doesn’t infringe, doesn’t mean $UTHR won’t try to sue. The good news is we are now 505b1 so no 30 month automatic stay, instead we fight against a preliminary injunction which is a very high threshold to meet (4 tests). If it goes to trial I don’t know if there is the issue of preclusion, can we run the same arguments?, but can our lawyers be extra careful this time! We were only limited to 4 invalidity arguments we can find more. Anyways this is years away and it’s not something I want to think about. Let’s get this company bought out now pls 😎
$LQDA Just came across another expert call. An academic PH centre thinks 50% of its PH-ILD patients can be reclassified as PAH. There are conversations ongoing with PH specialists across the country on how to do this. Their perspective on insurance is that it makes no difference to them as both drugs are priced the same. Longer term though ILD patients will be referred in already on Tyvaso and it may be easier to just remain on that.
$LQDA Confirmed L606 will be a 505(b)(1)
Part of the settlement prevents them from using 505(b)(2)
2
24
2,551
$LQDA To add to this, almost every expert call transcript I have read has PH specialists saying patients seem to like Yutrepia better
You’re unable to view this Post because this account owner limits who can view their Posts. Learn more
McNulty Capital retweeted

Last week, a short seller, @CulperResearch, published a report arguing that @cerebras wafers wear out after about two years, and based on that premise the report suggested that the economics of our business are fundamentally challenged.
That number is wrong, and given that the basis of the entire report is built upon that assumption, all of the assertions that follow are also wrong.
We do agree that the question of how long our systems last is a fair question, so we want to address the topic plainly.
If you have a few minutes, I would encourage you to click on the link below, which will provide you with a better understanding of the pioneering work done by our engineering team over the past decade to ensure that the operating lifetime of our solutions is many, many years.
Link Here: cerebras.ai/blog/what-it-too…

$LQDA Recently published expert call with PH specialist on the potential for PH-ILD patients to be reclassified into PAH
Client: How many patients who have ILD that visit you have the WHO Group one phenotype, you would say?
Expert: “I would say probably at least 30%, maybe even more. The newer data that is showing or at least the pathways that we have been exploring over the past 30 years of the generation of the fibrosis in the lung, as compared to the site of lesion in the pulmonary hypertension, there has been always a debate and always a thought that somehow these processes are related. Currently, there has occurred a couple of trials that are actually looking at treprostinil and its effect upon the ILD patients, so the IPF patients. If that trial will show an improvement, it will probably skew a lot of us that did not really think about, which excludes me. In my mind, this process has always been related. I think a lot of these patients that have ILD and have ILD-related pulmonary hypertension, they probably will be reclassified more aggressively into the pure pulmonary arterial hypertension, mostly because again, if the process is the same, then the patients that are developing ILD, it’s not really an ILD-related PH, it’s more like an ILD and also PAH.”
Client: Really quickly, you’re saying that if treprostinil shows positive effect in broader IPF or that is the broader ILDs, then the PH-ILD patients are at higher odds of getting reclassified into WHO Group one instead of Group three?
Expert: “For sure. I think this is going to be a very strong argument towards that these are two separate related processes, but not a PAH that is a result of the ILD. I think a lot of these patients will get reclassified.”
$LQDA The thinking has always been that PH-ILD develops as a consequence of lung scarring, yet the severity of PH often doesn’t correlate with the severity of fibrosis. With treprostinil now showing benefits in both PAH and IPF, his argument is that some patients may actually have two related but distinct diseases, potentially driven by shared biological mechanisms, rather than ILD causing PH. One doctors opinion.
1
18
975
$CBRS Just so it’s clear for everyone and especially @HotAisle
$NVDA approached Cerebras for an acquisition first and they declined. They had to go with second best Groq. Cerebras also declined an acquisition from $ARM before the IPO. These guys want a hundred billion dollar valuation.
Former Global Head at Cerebras - Expert Call 27 Feb 2026
“Yeah. Now, model inference is where everyone is hyped about, to be honest. Cerebras is actually very well-placed to be the leader in model inference. That is the reason NVIDIA approached them and eventually, they bought Groq. The reason is Groq was their second choice because Cerebras not only can do model inference, but they can also do model training. On the other end, Groq is only for model inference. Their chips are not designed to do model training, so that's a limitation of Groq compared to Cerebras.”
Reuters - Exclusive Feb 2nd reuters.com/business/openai-…
As OpenAI made clear its reservations about Nvidia technology, Nvidia approached companies working on SRAM-heavy chips, including Cerebras and Groq, about a potential acquisition, the people said. Cerebras declined and struck a commercial deal with OpenAI announced last month. Cerebras declined to comment.
