
Private equity investor sharing real time learnings and offering advice where I can be helpful
Joined July 2022
- Tweets1.1K
- Following377
- Followers12.9K
- Likes1.7K



Pinned Tweet
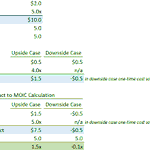
When evaluating deals, I like to have multiple ways to win. There are 4 main ways to generate a return. Organic growth, cash flow, buying m&a below your basis, and multiple expansion. You don’t need a fancy model to know how much value these impact your return by. See below

Privateequityguy retweeted
This post isn’t saying that ai will replace lawyers. It’s that the legal bills for PE firms are out of control and you have big law partners making $20M, which is not sustainable. AI is a catalyst that should drive down fees meaningfully in addition to good lawyers going to smaller firms that will take share. The shift of qofe providers leaving the big four to start their boutique is similar. AI expedites this trend with the barriers to start a law firm boutique going to be lower than ever. Spend won’t go to 0 but it should significantly decline. The big law firms know it too which is why they’re hoping to double or triple volume with AI with the same headcount while keeping revenue flat while lowering fees
Privateequityguy retweeted

There should be a word in English with the same meaning as schadenfreude. Taking pleasure in someone else's troubles is a common, natural, but still deeply troubling trait.
I used to have a strong case of it. I cared as much about my relative standing as my absolute position. Life was a race and if someone else stumbled I felt I was better off.
The field of trading is particularly susceptible to the trait. Markets are viewed as zero-sum. Performance is inherently relative. Still, it's possible to be ultra-competitive, to get joy out of your own success, and not get enjoyment out of other's pain. It took me a while to learn that.
The same instinct plays out far beyond markets. I think schadenfreude is at the root of much of today's political dysfunction. Too many people are more upset by someone else's success than they are happy about their own. Since there will always be someone more successful, living that way is a recipe for discontent. That gets reflected in the voter booth.
I eventually grew out of the emotion. Maybe self-awareness of my personal faults helped me overcome it. Maybe I just had enough professional success to where my confidence rose enough. I like to think it was the former.
Either way, I'm happier that I overcome it. When someone stumbles, I'm just bad for them. Spending emotional energy celebrating others' losses is a lousy way to live.
This is well said. Everyone who talks about buying for 4-5x don’t realize that a 4-5x multiple business is low quality. I’d rather pay 6-7x for a better quality business where platforms of scale trade for 15x to PE than a 4-5x business that PE doesn’t want (project based/other risks) or where PE platforms of scale trade for significantly lower multiples

Yesterday I announced to our investors that Slack Water Capital and our affiliates will no longer be allocating to new self-funded search opportunities.
This decision is based on my belief that the environment for self-funded searchers, and self-funded search investors particularly, has deteriorated significantly since I first came up with the idea to launch a fund 3 years ago.
While I still have a deep respect and admiration for the self-funded search model, having been a successful self-funded searcher myself, I believe the opportunity set today is no longer as attractive as it was even just 18-24 months ago for the self-funded search investor.
When I first started investing in this space, the opportunity set was very different. High-quality businesses with recurring revenue, low customer concentration, and $1 to $2 million of EBITDA could routinely be purchased for 3-5x. Competition for these deals was relatively limited. They were too big for the average buyer but too small for most private equity.
Today, there are far more buyers chasing these same types of SMBs. Private equity firms and their portfolio companies have come down market; family offices have proliferated and are looking for uncorrelated long-term holds with strong cash flow yields; and there is an exponentially growing number of aspiring ETA entrepreneurs looking to get in on the perceived gold rush.
The results are predictable.
Valuation multiples for quality businesses with $1 to $2 million of EBITDA have expanded materially. Deals that once traded at 3 to 5x, now routinely sell for 6 to 8x...and sometimes even higher! The 70-80% SBA loan, 10-20% seller financing, and 10-20% equity self-funded search model of the past simply doesn't work at these valuation levels.
Thus, the self-funded searchers, on average, are left picking through the scraps left behind by other more experienced and better capitalized buyers.
These scraps are typically the lower quality businesses with high customer concentration, greater economic sensitivity, more project-based revenues, greater key-person risk, and/or more operational complexity. And valuations for these businesses have moved up as well. These are primary types of businesses that are trading for 3-5x today.
I do think there are still some opportunities in the sub $1 million EBITDA range for self-funded searchers. However, it is really hard to deploy a meaningful amount of capital into these smaller deals due to a small total equity check and the SBA's 20% ownership threshold. While these can be good opportunities for searchers and individual investors, they don't really move the needle for a fund.
The typical self-funded searcher profile has also changed. The self-funded search model has been heavily marketed and romanticized on social media and podcasts. As a result, it now attracts a much wider pool of people than it did in the past. Many of the new crowd are not as well equipped to perform what is essentially a leveraged buyout of an incredibly fragile small business.
Many of these new buyers underestimate how hard it is to successfully operate a small business while also servicing a significant amount of debt. They underestimate just how savvy the current business owner is, how hard they work, and how many roles they fill on a daily basis. Many searchers think they are buying passive income and can operate from behind a spreadsheet.
Nothing could be further from the truth.
Finally, when I started building Slack Water, there were only small handful of funds or larger investor groups focused on investing in self-funded deals. At the time, I felt like I was filling a real gap in the market. However, I no longer believe that to be the case.
There are now dozens of funds and investor groups targeting the space. There was a period of time in 2025 where it seemed like there was a new fund focused on self-funded searchers being launched every week.
In my opinion, there are just not enough "large", high-quality, self-funded search deals for all these funds to deploy that much capital in this space unless everyone is going to write a lot of $50k-$100k equity checks. And how much due diligence can you perform, and impact can you have post-closing, across 100 portfolio companies?
This flood of new capital, and shortage of quality deals of size, is naturally causing these funds to compete for what limited deal flow there is. This competition is naturally pushing investor terms in an unfavorable direction. Less governance. Less downside protection. More aggressive structures. Higher entry multiples. Less equity participation.
In my opinion, the combination of these 3 changing dynamics is not a great recipe for future returns for the space as a whole...
Yes, there will still be exceptional operators who find those needles in the haystack, build great companies, invent innovative capital structures, and achieve extraordinary outcomes through self-funded search. I believe that strongly.
However, in my opinion, returns for the "asset class" as whole over the next 3-5 years will likely not be what they were over the past 3-5 years.
Rather than force capital into what I believe is a deteriorating environment, I believe the disciplined decision is to step aside.
Personally, I've also discovered that I actually enjoy operating more than I enjoy being a passive investor. I enjoy the messy process and challenge of building something. The daily battles that inevitably popup. And, selfishly, having the final say on strategic direction.
As a result, going forward Slack Water will focus on building our own platforms and explore new ETA models while remaining open to opportunistically investing across both private and public markets.


Privateequityguy retweeted

If you run a home service company (or aspire to someday), you need to read this.
Here is why I am launching a newsletter on June 1 (subscribe in comments):
Countless entrepreneurs are wanting to dive deeper into what it takes to scale beyond $100M… without raising capital.
- how to blend “high performance” with a purpose driven culture
- how to lead the way in technology + artificial intelligence - where to invest… and what to avoid
- how we design systems & processes to drive improvements in targeted KPIs
- how we approach acquisitions + our post-closing integration work
- how I think about competing - and WINNING - in the face of intensifying competition from large consolidators
- how we leverage our long term orientation to outperform our peers
- how I think about working with family members to include my dad and brother
- how we finance our business & investing activities
… and many more tactical + strategic insights.
Grateful for my founding sponsors… really excited to share exclusive content in collaboration with category leaders across software, AI, financing, and more.

Looking to partner (acquire a 51% stake) with other bookkeeping / fractional CFO firms. Would appreciate any intros. We have a unique approach to m&a / partnerships and would be excited to explain it to anyone who might be interested and aligns well culturally
Really great thread re independent sponsors

We closed our first deal as an independent sponsor a few weeks ago. It’s a nice service business with good margins in a niche corner of the market. We’re in at a fair price with reasonable incentives for everyone involved. If we execute, we’ll do well. You might think that I’d write a thread espousing all the tips and tricks that we used to execute this acquisition.
That’s not this thread.
We’ve been at this for 3.5 years and just closed our first deal. Here are all the things I wish I’d known as a non-PE guy co-founding an IS firm. I have a small audience on X, but hopefully this is valuable to a handful of folks. If not, writing this was a good exercise for me to reflect through.
Sorry in advance. No sunshine and rainbows here.
1
9
5,440
Privateequityguy retweeted
Having acquired over 30 businesses as a PE investor and advised on over 70 deals to PE, I often get asked what makes a good PE or independent sponsor buyer and how can you differentiate yourself from the pack
⊛There are obvious factors that you can’t always control such as:
☑Access to capital
☑Ability / tolerance for paying higher valuations
⊛But we’ve seen several deals “won” well before someone sees an offer and knows how much you can pay. Factors that make a big difference, especially in proprietary situations, include
☑ Speed: If you have a call with the seller, send your financial request right after the call with an already executed NDA. Once you receive the below data, you should submit an LOI within 24 hours of receiving the data or at least give a verbal offer. People want to work with buyers that they believe will be easy to work with in diligence. So many firms take forever with diligence or submitting offers and sweat the small stuff. While sweating the small stuff they often lose out on opportunities all together
☑ Ease of diligence: In your diligence request list, include a step-by-step overview of how to pull everything. For example, if you ask for the P&L, provide the click-by-click way of how to pull this through quickbooks
o Have your diligence request list be as little as possible. In order to size up an opportunity you really don’t need more than high level service mix (can even be verbal to start), last 2 years monthly P&L, addbacks / current owner compensation, understand if rent is in the P&L already, and latest balance sheet. All of this besides the addbacks should take 5 minutes to pull in quickbooks and the rest you can get verbally. The addbacks can also be estimated – you don’t need the backup at this stage
☑Fit: Don’t come off as your stereotypical PE professional. Show a personality, this should be self explanatory
☑ Certainty of closing: Give some stats about how many deals you have done and how you are not in the business of retrading.
Having acquired over 30 businesses as a PE investor and advised on over 70 deals to PE, I often get asked what makes a good PE or independent sponsor buyer and how can you differentiate yourself from the pack
⊛There are obvious factors that you can’t always control such as:
☑Access to capital
☑Ability / tolerance for paying higher valuations
⊛But we’ve seen several deals “won” well before someone sees an offer and knows how much you can pay. Factors that make a big difference, especially in proprietary situations, include
☑ Speed: If you have a call with the seller, send your financial request right after the call with an already executed NDA. Once you receive the below data, you should submit an LOI within 24 hours of receiving the data or at least give a verbal offer. People want to work with buyers that they believe will be easy to work with in diligence. So many firms take forever with diligence or submitting offers and sweat the small stuff. While sweating the small stuff they often lose out on opportunities all together
☑ Ease of diligence: In your diligence request list, include a step-by-step overview of how to pull everything. For example, if you ask for the P&L, provide the click-by-click way of how to pull this through quickbooks
o Have your diligence request list be as little as possible. In order to size up an opportunity you really don’t need more than high level service mix (can even be verbal to start), last 2 years monthly P&L, addbacks / current owner compensation, understand if rent is in the P&L already, and latest balance sheet. All of this besides the addbacks should take 5 minutes to pull in quickbooks and the rest you can get verbally. The addbacks can also be estimated – you don’t need the backup at this stage
☑Fit: Don’t come off as your stereotypical PE professional. Show a personality, this should be self explanatory
☑ Certainty of closing: Give some stats about how many deals you have done and how you are not in the business of retrading.
interesting tactic from one of our PE clients: buyer offers to pay for half of seller's legal counsel if they use one of the buyer's recommended attorneys. When you factor in how many deals are lost to a seller using unqualified counsel and compare this to how much value is created from an accretive deal, it's a no brainer
Very excited to announce that I'm starting an offshore recruiting firm! I know there's been a lot of competition in this market, but I plan to undercut pricing meaningfully. No more paying $6K recruitment fees for someone costing $10k per year.
Delivery model: Go on upwork, do a short term contract with a few people and hire someone off here full time. These are people that you can sort by reviews and are self selecting in that they are hungry.
Compliance: Use gusto/rippling/deel.
Price: $0!
Conclusion: Any offshore recruiting firm charging $6k per placement is screwed. If you follow the staffing industry, permanent placements command the lowest EBITDA multiple (due to cyclicality/not recurring) and fees are typically 10-30% of total comp. Why are firms that are placing much easier to fill roles charging 60% of total comp fees?
Incumbent counterargument - but we're switching to a managed service model where we will charge $3k/month for an $850/month role. If anyone thinks an SMB owner is naive enough to perpetually pay a 350% markup for a managed service model for "compliance" that you can do through gusto for a few bucks a month than you don't understand that SMB owners are scrappy.
P.S. the placement fees are highly negotiable for anyone about to sign up to pay $6k for a fee since it drops through to these recruiting firms at like 90%+ margins. You shouldn't be paying more than $1-2k per placement
I have 9 offshore employees. We used a recruiter for our first hire and the candidates were subpar. I've had a ton more success through the following methods:
1. DM'ing people from reputable firms who I know are prevetted
2. Hiring after my first contract off upwork
3. Getting referrals from existing offshore employees and giving them a small bonus
4. indeed/linkedin job postings

I seriously have used this company 30+ times to hire employees across my companies.
$5 an hour for excellent talent.
I'm also an investor in the business:
supportshepherd.com

5
14
14,360
The cost of offshore recruiting firms are really high for the low value they provide. Offshore recruiting firms charge anywhere from $5-8k per role (most on the higher end), which can equate to almost as much as a year's salary for some offshore employees.
Additionally, these recruiting firms are run off almost entirely offshore labor (you're not getting what you pay for), and the quality of candidates shown are not nearly as good as what your current offshore employees can find or you leveraging upwork to network/find people and linkedin DM's or linkedin job postings
1
2
3,899
There's currently several offshore recruiting upstarts out there and their fees are typically highly negotiable. The barrier to opening an offshore recruiting firm is very low and I think in a few years we will see pricing meaningfully lower. It will be interesting to see how this all plays out and how these firms either get disintermediated or are forced to lower pricing/improve the quality of their offering
Bottom line: instead of wasting several hours corresponding with a recruiting firm to find the hire, invest the time to find someone yourself and you will likely find a much higher quality candidate
1
3,200
Privateequityguy retweeted
Just depends on scale. A small tuckin is going to be very accretive regardless so 1-2mm ebitda businesses aren’t moving meaningfully, prob down half to a full turn. Scaled businesses that were trading for 15-18x could be down 2-3x from the high end of the range vs 21/22 peak
Privateequityguy retweeted
Contratrian opinion but I believe the valuation gap between resi and commercial will meaningfully tighten or flip. Resi had a huge run up, several consolidators coming to market this year we’ll see how that goes. Personally pretty bearish on resi multiples and the owner of a large resi consolidator (50+ ebitda) and separately commercial consolidator (60+ ebitda) shares this sentiment with me
Thank you to the several people who reached out about this role. We have filled this position THROUGH TWITTER. So cool the power of this network/platform. When I started posting, it was to educate SMB searchers by providing a lens of someone who spent their career in private equity. There's a lot of people on this platform selling their brand or services, which is one of the reasons I've chosen to stay anonymous (don't want to sell)... Today it's largely for the same purpose, but in return I've been able to find, through this community, both partners and talented individuals willing to bet on my ventures for which I'm extraordinarily grateful

Looking to bring on a 22-24 year old based in NYC area or Toronto interested in business that would serve in a business development / sourcing role. This would include lots of cold calling, hustle and resilience with the opportunity to source deals for private equity buyers. Please reach out if you are interested in learning more
Looking to bring on a 22-24 year old based in NYC area or Toronto interested in business that would serve in a business development / sourcing role. This would include lots of cold calling, hustle and resilience with the opportunity to source deals for private equity buyers. Please reach out if you are interested in learning more
if you're looking to or know anyone who might be open to sell all or a portion of a hockey rink, karate dojo (insert mr. miyagi joke), summer cap, swim school, band camp etc. please reach out!!
Privateequityguy retweeted
💪Very excited to announce the overdue launch of our fractional CFO firm offering everything from bookkeeping to being thought partners by helping SMB's implement KPIs, budgeting/forecasting, and thinking thru sell-side preparations/various what if planning... more color in the below tweet thread of why we are doing this and why I think there's a huge need in the market for it (scarcity of talent servicing SMB vs PE)
You can’t manage what you can’t see - investing in better financial controls and gaining access to real-time operating metrics can (i) help operators better manage their business and (ii) lead to a higher EBITDA multiple in a sale.
⚠️Below are two recent examples of the problem with not having clean books