

Civil engineer reading the AI buildout like a site plan. 🇺🇸 US Stocks | ETFs | Bitcoin Picks & shovels over hype. Data Centers | Physical AI | Quantum
Joined February 2018
- Tweets4.4K
- Following237
- Followers3.4K
- Likes2.2K




Pinned Tweet
Who i am and what i own.
Civil engineer. co founder of a construction company. i run building sites for a living.
That matters here. i look at a data center company like one of my sites. how much power, how much land, cooling, and is the schedule real or just a slide.
Investing is not my day job. i follow a few and i post about those only.
The book:
Ai infrastructure
$IREN
$NBIS
Physical ai and sensors
$OUST
$ONDS
Space
$RKLB
$ASTS
Photonics and chips
$MRVL
$COHR
Crypto exposure sits in $BLOX.
How i pick:
✅ i look at what the company has built first. numbers come after
✅ i like companies that built something real but are not earning from it yet
✅ i buy only on red days. i sell only on green days
✅ after i finish reading, i wait weeks before i buy
What you will not get here:
❌ price targets
❌ buy or sell calls
❌ opinions on stocks i do not own
❌ paid promos, ever
Positions change. when they do i update this post.
my own money, my own research. not advice.
Last updated 18 aug 2026
3
1,026
$IREN ceo on demand:
"any GPU you can bring online, you have got multiple people all wanting it"
✅ 2026 sold out
✅ 2027 conversations cover multiples of the capacity they can bring online
✅ 2028 already coming into focus
And customers aren't just buying, they're helping fund the build:
✅ ~$22m per MW on the new 5yr deal with 90% of gpu capex prepaid
✅ $40m per MW on the new short term deal
Pricing isn't going down. the CEO says the evidence suggests it's going up
Demand is there. now customers are paying to help build it
$IREN carries $6bn of data center assets on its balance sheet, and management has previously described its data center portfolio as unencumbered.
Owning infrastructure creates another potential funding route as the cloud business scales.
That flexibility matters when capital gets expensive. Additional financing still needs to be secured.

Anthropic made $33bn of revenue in 9 months. its IPO filing shows $895bn of compute already signed, much of it take-or-pay
$70bn of that is due in the next 12 months
Every dollar ends up as GPUs, power and data centre rent. who gets paid first?

1
1
135
Bitcoin's hashrate grew every year from 2016 to 2025. this november it's flat to down 4% on a year ago
Mining pays less, and miners are moving their power to AI racks
Fewer machines chasing the same $BTC. relief for the miners left, or a security worry?

148
One chart: in Q4 2024, 91% of $CORZ revenue came from bitcoin mining. last quarter it was 7%
AI colocation filled the gap, growing from $15m to $215m a quarter in a year. management says mining ends by year end
Power was the asset all along. which miner flips next?

189

Imagine paying 10x more for the exact same thing. that's zcash ETFs right now
What's an ETF? a way to own a coin through your normal stock account. no wallet, no keys, no crypto app
So what's the deal? grayscale's zcash fund is the only one you can buy in the US today. it charges 2.5% a year. the winklevoss twins just applied to launch one that charges 0.25%
What does that mean in real money? put $10,000 in. grayscale takes $250 a year. winklevoss would take $25. same coin. 0.25% is what the biggest $BTC fund charges
Can you buy the cheap one yet? not yet. it still needs a green light from the SEC
Here's the catch though. the whole point of $ZEC is privacy. you can send money without the world seeing who paid whom or how much. buy it through an ETF and you skip that part. the winklevoss fund says its coins will sit in addresses anyone can check on the blockchain
And you don't get a vote either. zcash holders vote on big decisions, like how its development money gets spent. but only with coins in their own private wallet. ETF owners can't vote
My read: the cheaper fund is great news for buyers. but through an ETF you own the price, not the privacy
Would you buy zcash through an ETF, or hold it yourself?

2
3
249
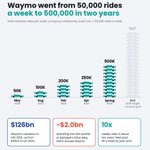
$GOOGL's waymo did 50,000 paid rides a week in may 2024. by spring 2026: 500,000. 10x in two years
Still burning cash: the alphabet unit that houses it lost $2.0bn last quarter on $372m of revenue
Every robotaxi is a GPU customer, on the road and in the cloud. 1m by year-end?

179
$IREN signed a 5 year deal with customer prepayments covering 90% of the associated gpu capex.
My bullish takeaway: customers are helping finance expansion. If repeatable, that could reduce the new shareholder capital needed to grow.

2
47
1,444
$IREN said it contracted H100 capacity at double the price of its previous H100 contract at Prince George.
That is encouraging evidence that older gpus can retain commercial value as newer chips arrive.
One contract cannot prove lifetime returns, but it strengthens the case for useful revenue beyond the first deal.

$WULF booked a $710m profit on $76m of revenue. the business itself lost $88m
The gap is a $728m paper gain on warrants. diluted EPS was minus 3 cents
The real progress is rent: AI leases are 83% of revenue now. MW online or headline profit, which do you watch?

2
2
236
Zcash is in a fight right now over a $120m grants fund, and it comes down to one question. who should get the new coins?
Where do new $ZEC go today? 80% of every block reward goes to miners, 8% to the zcash community grants committee and 12% to a fund coinholders vote on. on $BTC, miners get all of it
How much is 8%? about 144 ZEC a day, roughly $190k. the committee also holds about 91,500 ZEC in its treasury, near $120m
What did the committee offer? on oct 29 it proposed moving 36,200 ZEC into the new miner reserve from this week's upgrade, and taking less in future. about 98,000 ZEC in total. critics like helius ceo mert mumtaz called it "nowhere near good enough". it pulled the plan this week
What's on the table now? co-founders sean bowe and zooko wilcox back a draft that ends the 8% stream, parks it in a dev and legal defense lockbox, and has the committee send 50,000 ZEC to the miner reserve
When does it get decided? any change likely needs a network upgrade and there's no date. the current funding ends at the 2028 halving anyway unless a new ZIP extends it
My read: every proof-of-work chain ends up arguing about this. once the subsidy shrinks, every coin sent somewhere other than miners is security you aren't buying
Should a coin fund its own developers from block rewards, or should miners get everything like bitcoin?
229
$ZEC just got 3x faster. the NU7 upgrade went live today at block 3,543,405, and blocks now land every 25 seconds instead of 75
Does that mean 3x more new coins? no. the reward per block was cut by the same 3x, so issuance stays the same. halvings are now spaced 3x more blocks apart, so the 21m cap and the schedule don't move
Is it actually faster? since the switch the chain has averaged about 27 seconds a block. three confirmations now take about a minute and a quarter, down from almost four
What changed with fees? 60% of every block's fees now go into a public reserve. miners keep 40%. the reserve starts paying back out through block rewards around 2031
Why do that? same problem $BTC has. rewards keep halving, so one day fees have to pay for security. this smooths the fee side out before that day comes
Anything lost? yes. sprout, the oldest privacy pool from 2016, is now shut. about 12,200 ZEC never moved out and can't be spent, around $16m. a recovery idea is on the table but nothing is approved
My read: the fee reserve is the part to watch. every proof-of-work chain, bitcoin included, hits the same security budget question once the subsidy shrinks
Would you want something like this on bitcoin, or is that a line you don't cross?
3
256
A UK power station with 4GW of grid access wants 1GW+ of it for AI. drax is teaming up with brookfield
Phase 1 is 100MW from early 2028, and it still needs a tenant and planning
Owning the grid hookup is the moat, same play as miners turned AI clouds. which plant is next?

123
$IREN dropped a site video with the Q1 print. went through it frame by frame as a civil engineer. here's what the build tables actually show
Fully handed over:
✅ Prince George data halls 1-4
✅ Childress Horizon 1
Substations are complete on every row of the 0.8GW table except canal flats. power goes in first, that's the right build order
The rows in final stages:
✅ Horizon 2 and 3: structure and electricals done, cooling and gpu install in progress
✅ Mackenzie and childress air cooled halls 1-3: electricals, cooling and gpus all running in parallel
✅ Horizon 4: substation, foundations and structure done, electricals underway
Next phase is already moving:
✅ Sweetwater 1 phase 2: high voltage substation complete
✅ Prince George data hall 4 liquid cooled: civils and both substations complete
✅ Badajoz, bundey and sweetwater 2: design done, procurement underway
The hard part of a data center is the power and the substation
IREN has that done across the 0.8GW and is already building it for what comes after
Most of the remaining work on the 0.8GW is fit out, and that's the part that moves fastest
A year ago bitcoin mining was 97% of $IREN revenue. this quarter AI cloud is 88%, $200m of $228m
Revenue barely moved, $240m to $228m. the business underneath is new, with $20.3bn of backlog

1
2
376
$IREN as a civil engineer this is the slide i'd frame
14 months from starting civil works to an NVIDIA Exemplar tested 19k GB300 cluster at Horizon 1
Industry benchmark: 18 months for the data center alone, no GPUs
✅ That 14 months includes gpu deployment. the 18 month benchmark doesn't
✅ My read: speed comes from building on land and power they already own. the hard part is done before the first pour
✅ Operating capacity now 0.1GW IT, +127% QoQ (company says)
Next stop 0.3GW by january, then 0.8GW targeted by end of 2027
And the land bank behind it:
✅ >30,000 acres secured
✅ >5GW secured power
Every new GW still has to go through the same civils, the same grid connection, the same build
$IREN has shown it can do that faster than the benchmark
Speed of delivery is the moat money can't rush

Q1 FY27 at a glance: Explore IREN's quarter-on-quarter growth in operating capacity, revenue, and customer commitments from our latest investor presentation.
View the presentation: iren.com/api/media/file/Q1-F…
Read more: iren.gcs-web.com/static-file…

$IREN is carrying $2.5bn of deferred revenue
Sep 30: $2,544m
June 30: $1,842m
That's customers paying ahead of delivery
With AI infra names getting sold on debt worries, this matters:
✅ Q1 operating cash flow $529m. Deferred revenue inflow alone was $645m
✅ Post quarter 5yr deal: company says the customer prepays 90% of the GPU capex
✅ My read: customers only pay ahead like this when they can't get the capacity anywhere else. That's the power moat showing up in the cash flow statement
❌ Take the deferred revenue inflow out and operating cash flow was roughly -$116m
❌ Net debt went from $216m to $4.43bn in one quarter
❌ FY27 capex still to spend: $15bn. $9bn covered, $6bn is still a target "subject to market conditions"
❌ ARR target of >$4bn slipped from year end to jan 31, may run to end of feb
Deferred revenue is a liability. IREN pays it back by delivering
Every month of delay it sits there as a liability instead of turning into revenue
Delivery is the whole trade now
$IREN

290
$ZEC NU7 activates at block 3,543,405 🔐
• Blocks: 75s → 25s (3x faster confirmations)
• Same daily issuance, 21M cap intact
• Sprout pool closed for good
• V4 transactions retired
Not a new pool. That’s Tachyon, still in development.

171