

AP @WU_econ, Bayesian econometrics and empirical macroeconomics (monetary, business cycles, now/forecasting)
Vienna, Austria
Joined June 2010
- Tweets162
- Following162
- Followers364
- Likes673


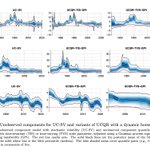


New working paper "A Bayesian Gaussian Process Dynamic Factor Model" with T. Chernis (BMA), N. Hauzenberger (Uni Strathclyde), and H. Mumtaz (QMUL): arxiv.org/abs/2509.04928
Proposes a DFM where the latent factors are linked to observed variables with unknown nonlinear functions

Michael Pfarrhofer retweeted

#SUERFpolicybrief “Monetary policy under economic uncertainty: Evidence from the Euro Area" by Niko Hauzenberger (@UniStrathclyde), @mpfarrho (@wu_vienna), and Anna Stelzer (@oenb)
📄tinyurl.com/37re78uh

Michael Pfarrhofer retweeted

New CEPR Discussion Paper - DP20442
Nonparametric Mixed Frequency Monitoring Macro-at-Risk
Massimiliano Marcellino @Unibocconi, @mpfarrho @wu_vienna @WU_econ
ow.ly/q6GB50WmRMW
#CEPR_MEF #EconTwitter

Michael Pfarrhofer retweeted
New CEPR Discussion Paper - DP19965
Bayesian Nowcasting with Mixed Frequency Data Using Gaussian Processes
@NHauzenberger @Strath_Econ, Massimiliano Marcellino @Unibocconi, @mpfarrho @WU_econ, Anna Stelzer @oenb
ow.ly/uO8S50V6S1v
#CEPR_MEF #EconTwitter

"Scenario analysis with multivariate Bayesian machine learning models"
▶️ Conditional forecasts, generalized IRFs in dynamic nonparametric models
▶️ Macroeconomic stress testing; macroeconomic risk and financial conditions; financial shock transmission
arxiv.org/abs/2502.08440

“Interpretable Bayesian machine learning for assessing the effects of climate news shocks on firm-level returns”:
▶️ Bayesian asset pricing framework & machine learning
▶️ text-based climate risk indicators
▶️ asymmetric impacts across firms
ssrn.com/abstract=5133162
Michael Pfarrhofer retweeted

#Econ Job Vacancy — Post Doc, 2 years at WU Vienna
Are you interested in collaborating with us (@WFrimmel , @HO2604 ) on research papers focused on intergenerational mobility in Austria?
- Vienna University of Economics & Business (@wu_vienna)
- Fulltime research position at the Department of Econ (@WU_econ)
- Starting date in spring 2025
- Application Deadline: March 4, 2025
- More info: sites.google.com/view/alps-i…
- Pls share/RT

Michael Pfarrhofer retweeted
You want to do your #PhD in #Economics at one of Europe’s largest and most modern business & economics universities. Join us @wu_vienna, @WU_econ. Click her econjobmarket.org/positions/…
#Vienna 🇦🇹

Michael Pfarrhofer retweeted

WE ARE HIRING!
Want to do a PhD in economics? Stop searching and click here: econjobmarket.org/positions/…
In this new (significantly revised) WP, @annstelzer and I (@WU_econ) discuss how to extract multiple structural shocks (monetary policy and central bank information) from multiple external instruments across multiple economies (US, EA and a few more) arxiv.org/abs/1912.03158
"Bayesian nonparametric methods for macroeconomic forecasting" (chapter 5), co-authored by Massimiliano Marcellino (@Unibocconi) and me (@WU_econ) #econometrics #forecasting
doi.org/10.4337/978103531005…

📣 NEW: Handbook of Research Methods and Applications in Macroeconomic Forecasting by Michael P. Clements & Ana Beatriz Galvão
Chapter 14 is #OpenAccess at: doi.org/10.4337/978103531005…
More info: e-elgar.com/shop/isbn/978103…
#MacroeconomicForecasting #Econometrics @AndrewBMartinez

ALT Handbook of Research Methods and Applications in Macroeconomic Forecasting advert, including the following quote: ‘This Handbook is a must-read for academics and practitioners alike. It surveys the most recent developments in the theory and practice of macroeconomic forecasting. All chapters are written by eminent and experienced scholars, and contain up-to-date methods and applications. This is a highly commendable book!’ – Philip Hans Franses, Erasmus University Rotterdam, the Netherlands.
Final few days left (deadline on November 20) to apply for the non-tenure track Assistant Professor position (post-doc) in Macroeconomics at @WU_econ at @wu_vienna #EconJobMarket econjobmarket.org/positions/…

See also on @EconJobMarket, for the macro AP position (deadline on Nov 20, 2024) @wu_vienna: econjobmarket.org/positions/…
See also on @EconJobMarket, for the macro AP position (deadline on Nov 20, 2024) @wu_vienna: econjobmarket.org/positions/…

WE ARE HIRING! We offer three positions as Assistant Professor, non-tenure track: IO, macroeconomics, and public economics. Details at
wu.ac.at/karriere/jobportal/…

Michael Pfarrhofer retweeted
Welcome to our new colleagues: Jonathan Fitter, Nicolas Göller, Maximilian Heinze, Sannah Tijani (PhD program) & Kentaro Asai, Federica Braccioli (@fede_braccioli), Davide Cerruti (@dcerruti), Shahroo Malik, Bernhard Schmidpeter (@BernhardEcon), Nina Xue (Assistant Professors)!


“Sparse time-varying parameter VECMs with an application to modeling electricity prices” by N. Hauzenberger (@UniStrathclyde), L. Rossini (@LaStatale) and me (@wu_vienna, @WU_econ) published in the International Journal of Forecasting (IJF, @IIForecasters)
sciencedirect.com/science/ar…
Michael Pfarrhofer retweeted
New research by @mpfarrho (@wu_vienna) and co-authors develops Bayesian machine learning tools, harnessing macroeconomic big data to accurately monitor the current state of the economy. arxiv.org/abs/2402.10574
"Nowcasting with Mixed Frequency Data Using Gaussian Processes" by N Hauzenberger (@UniStrathclyde), M Marcellino (@Unibocconi), A Stelzer (@oenb) and me (@WU_econ).
We develop Bayesian machine learning methods for mixed data sampling (MIDAS) regressions.
arxiv.org/abs/2402.10574
We evaluate predictions in short-horizon now- and forecasting exercises with both simulated data and data on quarterly US output growth and inflation in the GDP deflator.