

Silicon Valley Operator + Wall St Investor. Open to work on interesting opportunities. Tweets are just personal notes.
Dallas, TX
Joined January 2019
- Tweets8.9K
- Following1.8K
- Followers9.8K
- Likes17.5K


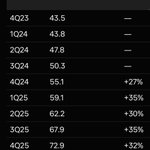


It's kinda wild that Uber One membership is growing 50% YOY.
For city dwellers the value proposition must slap them on the face for this kind of growth to be true.
$UBER – at Coppell, TX

3
13
3,585
Uber Eats growing ~25%. Advertising, grocery, international and Delivery Hero provide ample runway. Uber's Mobility + Delivery ecosystem offers cross-selling advantages. Look at Uber One membership growth for value prop evidence. – at Bensenville, IL
1
384
Uber is probably over earning rn and new competition might chip away at take rate slowly. This is a legitimate risk to watch out for. – at Rosemont, IL

Why I'm not an $UBER bull:
At its core, Uber is a franchise business. Just like McDonald's or Subway, the concept is the same. Uber allows "carefully" chosen people (anyone with a pulse and the proper license) to represent the brand. Folks sign up because they already own the big thing you need to get into business. The barriers to entry are much lower than a traditional franchise business, which should be good for both Uber and consumers. More drivers = lower prices.
The best franchises offer a good deal for both the parent and the franchisee. McDonald's does this. So does A&W (in Canada, anyway). If both the parent and the franchisee make good returns on their investment, then it's a model that will likely stand the test of time.
(An easy way to tell the strength of a franchise concept is to see how many owners own or want to own multiple locations. Existing franchisees voting with their wallet is super bullish.)
Subway did this for a while; locations were cheaper to open than other concepts, and sales were brisk. That went away as too many Subways flooded the market. We all know what's happening with Subway these days. It's an example of a franchise where the scale started tipping much more in favour of the parent.
Uber is one of the most one-sided franchise concepts out there. Numbers vary depending on the market, but I'm going to assume Uber takes a third of all revenue, while the driver keeps two-thirds. I've seen analysis that suggests Uber's take is closer to 50%, but we'll be a little generous here.
The driver keeps 66%, but has almost 100% of the expenses. The driver has to pay for gas, insurance, car upkeep, phone data, and they're making nothing while they wait for more rides. Meanwhile, Uber pays for the expense of maintaining the app and onboarding new drivers. Uber makes a terrific return on its investment; drivers barely make minimum wage, and they provide the only thing that takes up front capital -- the car. Drivers make a *terrible* return on their investment.
This is why I can't be an Uber bull. Incentives aren't properly aligned.
1
339
Ngl, $EFX is very interesting here.
In a cyclical trough for mortgage and employment. Has a differentiated asset in TWN with meaningful cross sell synergies with Bureau business. OB3 2027 employment verification mandates is on the horizon.
HSD revenue grower at 14x NTM P/E.

Shout out to @chitchatstocks and @irbezek for introducing $INTR.
Very interesting bank, hopefully becomes a fintwit darling without the associated curse.
open.spotify.com/episode/63l… – at Coppell, TX


The operating leverage is expected come from improving matgins by 3% to 15%.
For some context $ODFL has close to 30% operating margins. – at Coppell, TX

1
1
365

$CPNG
Assuming 5% EBITDA margins 5 years out with 6% sales CAGR over that period, both of which are atleast half of management's expectations.
2031
* sales : $40B
* EBITDA : $2B
That's 14x 2031 EBITDA multiple.
This assumes Far-fetch and Taiwan are a zero.

Common stock dilution is the very slide after disclaimers. Not sure if this is a good sign or a yellow flag.
$CPNG – at Coppell, TX

1
2
1,160

Tonight I'll be convincing myself that selling ungodly amount of $TTD puts at $10 strike price is a good idea.
Wish me luck. – at Coppell, TX
6
12
4,602

Interesting that $DSP Viant is taking the stance that they won't make proprietary supply side deals but will certainly continue buying proprietary data that enables better targeting.
Makes sense to me. TTD's Ventura OS bet makes very little sense in this context. – at Coppell, TX

So VenturaOS is pivoting their strategy from being a full fledged OS to the underlying streaming engine that powers OEM's proprietary OSs.
youtu.be/DDy0GfPFGhQ?is=03P1… – at Coppell, TX

572