

India’s Leading Stock Market Advisory & Research Platform 35M+ users | 150+ SEBI Regd. analysts | AI-powered by Stoxo Daily trade ideas with entry, exit & stop
Bangalore
Joined June 2020
- Tweets6.8K
- Following2
- Followers362K
- Likes356




Pinned Tweet
For decades, Engineers India Limited has designed refineries. Now, it’s expanding into data centres, defence, nuclear and critical minerals- using its engineering expertise across new industries.
The latest numbers show an interesting shift: less construction, more high-margin planning work.
Here’s what’s happening:
Revenue: Down around 6%
Profit: Up 141% to ₹158 crore
Order book: ₹14,424 crore, up 19% in a year
New order target: ₹8,000 crore this year
Orders secured so far: ₹3,565 crore
Major win: ₹286 crore contract to manage a new fertiliser plant in Ethiopia
Joint ventures: ₹42.5 crore profit this quarter, versus a ₹7.4 crore loss a year ago
Why does the shift matter?
Planning work earns 20–25% margins, compared with just 5–7% for construction. That helps explain how profit can rise even when revenue falls.
But there are risks to watch:
- New orders in Q1 were just ₹514 crore, slow against the annual target.
- Construction revenue fell 33% as major projects wrapped up.
- Some large projects in the Middle East are on hold.
- EIL’s story is moving beyond refineries. Its planning-led strategy is showing results, but the next challenge is securing enough new orders to sustain the momentum.
Follow StockGro for more interesting business and stock market stories.
Disclaimer: This content is for educational and informational purposes only. Please do your own research before making investment decisions.
#datacenters #defence #stockmarket

From designer homes to modern offices, decorative walls are becoming a bigger part of India’s interior design story.
Euro Pratik Sales is tapping into this trend through its decorative wall panels and laminates business.
Here’s what stands out:
-Record quarter: Revenue reached ₹103 crore, up 60% year-on-year.
-Profit growth: Net profit hit ₹20 crore, more than double last year.
-Growing reach: Presence across 148 cities, 25 states and 205 distributors.
-Asset-light model: Manufacturing partners in countries including South Korea and China.
-Strong balance sheet: No net debt and return on equity of 26.6%.
-Promoter confidence: Promoter stake increased to 72.72%.
But there are risks to watch. Operating margins have declined to 27.5% from 35.3% in FY26. Dependence on overseas manufacturing partners also exposes the business to raw material costs and global supply-chain disruptions.
Despite strong growth, the stock touched an all-time low of ₹168.95 this month.
Can Euro Pratik turn India's growing demand for designer interiors into sustainable growth?
Follow StockGro for more business stories and stock market insights.
Disclaimer: This content is for educational purposes only and is not investment advice. Do your own research before making investment decisions.
#designerhomes #stockmarket

Coca-Cola's India Bottler Files $1B IPO This Week: What's the Story?
Every time you open a Coca-Cola, Thums Up or Sprite, you're buying from a company most people have never heard of. That company is now gearing up to go public.
Here's what happened:
- DRHP filing: Hindustan Coca-Cola Holdings is expected to file its draft prospectus with the regulator this week.
- IPO size: Around $1 billion, roughly ₹9,500 crore.
- Target valuation: About $10 billion.
- Listing timeline: Planned for 2027, on BSE and NSE.
- Ownership: Coca-Cola Company holds 60%, Jubilant Bhartia Group holds the remaining 40%, acquired in July 2025.
- Offer structure: Largely an offer-for-sale most proceeds go to selling shareholders, not fresh capital for the company.
HCCB has been running since 1997, with 14 bottling plants across 10 states, 2,000+ distributors and 1.7 million+ retail outlets - a scale that could make this one of the biggest consumer IPOs of the year, if it goes through as planned.
Would you be interested in this IPO once it lists, or is the valuation already pricing in too much optimism?
Follow StockGro for more stock market and IPO updates.
Disclaimer: This content is for educational purposes only. Do your own research before making investment decisions.
#upcomingipo #cocacola
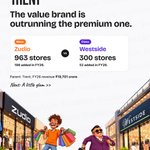
Same parent company. Two different price tags. 💸
From Maruti’s Arena and Nexa to Titan’s Tanishq and Zoya, India’s biggest brands don’t pick between mass and class. They build both. 🚗
Why businesses do it?
- A bigger customer base. The value buyer of today can become the premium buyer of tomorrow, and the parent keeps both.
- Shared backbone. Sourcing, distribution and brand trust get reused, so a second brand costs less than a new company.
- A built-in cushion. When one segment slows, the other can steady the ship.
What investors should watch?
Look past the headline revenue and check the mix. Nexa is now almost 30% of Maruti’s domestic sales. Zudio has 963 stores to Westside’s 300, and it’s growing faster. Ginger earns a 41% EBITDAR margin. Mass can mean volume and margin, not just volume.
One caution: a dual-brand model isn’t a guarantee. Air India and Air India Express both lost money in FY26. Execution still decides who wins.
Swipe through and see who’s doing it right.
Not investment advice.
Source: company FY26 results.
#MassVsClass #IndianBrands #Investing #StockMarket #Business #Marketing


India’s jewellery market is worth $85 billion. But which companies are turning this opportunity into growth?
India’s gems and jewellery market is projected to reach $130 billion by 2030, according to IBEF.
And the opportunity goes beyond domestic demand:
📊 The sector contributes around 7% to India’s GDP.
🌍 India recorded approximately ₹2.45 lakh crore in gems and jewellery exports in FY26.
💍 The industry employs nearly 5 million people.
But a growing industry doesn’t guarantee that every company will deliver strong stock returns.
For investors, the real opportunity lies in identifying businesses that can grow revenue, protect profit margins and justify their valuations.
Because investing isn’t just about finding a growing industry. It’s about finding companies that can turn that growth into shareholder value.
📌 Save this for your next stock research session.
Follow StockGro for more insights into India’s markets and the businesses shaping them.
#StockMarketIndia #JewelleryStocks #MarketInsights #FundamentalAnalysis

Silver Prices Crash 53% From Record High: Buy the Dip or Wait?
Silver’s rally looked unstoppable in January 2026. Now, prices have plunged from their record highs, leaving investors wondering what comes next.
Here’s what happened:
- Global silver: Hit $117/oz on January 28, then fell to just above $54 by October 23.
- MCX spot silver: Rose to ₹3,79,983/kg on January 29 before dropping to ₹1,94,170/kg on October 23.
- Silver futures: Traded at ₹1,95,500/kg on October 26.
- Why the fall? Rising bond yields and a hawkish Federal Reserve outlook put pressure on speculative demand.
What could move silver next? The Fed’s October 27–28 meeting, PCE inflation data, ETF flows and geopolitical tensions are key factors to watch.
While industrial demand from solar and electronics could support silver’s long-term outlook, silver remains more volatile than gold. The correction is a reminder to reassess exposure rather than assume prices have bottomed.
Would you buy silver after this correction or wait for more clarity?
Follow StockGro for more stock market and commodity updates. Do your own research before making investment decisions.
Disclaimer: This content is for educational and informational purposes only. Do your own research before making investment decisions.
#silver #stockmarket #investing
WeWork India up ~2% after Q2 FY27 Results: Net Profit Jumps 67.4%
WeWork India’s Q2 FY27 results are out, and the numbers are grabbing attention. Revenue rose 31.6% to ₹768.7 crore, while net profit surged 67.4% to ₹65.8 crore. But the bigger story is how the coworking giant is turning growing demand into stronger profitability.
Here’s what stands out:
-Profit growing faster than revenue: Net profit rose 67.4% year-on-year, outpacing revenue growth.
-Members outpace desks: Membership increased 32.5%, compared with 26.9% growth in operational desk capacity.
-Centres filling up: Mature-centre occupancy reached 87.7%.
-Debt turnaround: WeWork India moved from ₹310.5 crore in net debt a year ago to ₹23.1 crore in net cash.
-Cash generation strengthens: Operating free cash flow rose 149.2% to ₹237.7 crore.
-GCCs drive demand: Global Capability Centres contributed 40.8% of core revenue.
The catch? WeWork India is expanding capacity rapidly, and the real test will be sustaining occupancy, margins and cash generation as more desks come online.
Can India’s growing GCC market keep powering WeWork India’s next growth phase?
Follow StockGro for more business news, stock market updates and quarterly results analysis. Track WeWork India share price on the StockGro app.
Disclaimer: This content is for educational and informational purposes only. Do your own research before making investment decisions.
#weworkindia #coworking #investing
Founded in 1937 by Ganga Bishan Agarwal, popularly known as Haldiram, the business grew from a small bhujia shop in Bikaner into one of India’s most recognisable food brands.
Here’s why its business model is worth studying:
-A massive market: India’s snacks market was estimated at ₹50,590 crore in 2025, with projections suggesting it could exceed ₹1 lakh crore by 2034.
-Distribution is a competitive advantage: A great product means little if customers can’t find it. Expanding across local shops, supermarkets, restaurants and online platforms helps brands become part of everyday buying habits.
-Familiarity drives repeat purchases: Snacks are a high-frequency category. Once consumers trust a brand’s taste and quality, that familiarity can encourage repeat purchases.
-One brand, multiple revenue streams: Packaged snacks, sweets, restaurants and gifting allow Haldiram’s to serve different occasions, from everyday cravings to festive celebrations.
The biggest business lesson?
Don’t just build a product people love. Build a business that makes it easy for people to buy it again and again.
💬 Which Indian consumer brand should we analyse next?
#Haldirams #BusinessStrategy #IndianBrands #FMCG #StockMarket

WeWork India Q2 FY27 results, explained in 5 flags.
WeWork India rents ready offices to companies, seat by seat. It’s one of India’s biggest coworking and flexible office companies. Here’s how July to September 2026 went.
-Members up 32.5% in a year
-₹3,843 Cr in future payments already signed by clients
-₹23 Cr more cash than loans. A year ago, it was ₹310 Cr short.
-Broker costs up 63% to ₹29 Cr, nearly twice as fast as revenue
-Higher minimum wages (Karnataka up nearly 60%) and a revised electricity bill. Management says margin would have been 22–23% without them, against 21.2%.
Comment “WeWork” and we’ll send you the full results.
#WeWorkIndia #Q2Results #CoworkingIndia #StockMarketIndia #StockGro


India’s green energy boom has a problem: the power is ready, but the grid isn’t. ⚡
IREDA’s loans grew 31%, but profit rose just 1%. Grid bottlenecks could mean lost revenue for renewable energy companies and repayment risks for lenders.
Can ₹1.86 lakh crore fix the gap?
#IREDA #GreenEnergy


$7+ Bn. Nearly 100 million shoppers. 350 million+ orders. All in about 10 days. 🛒
Flipkart and Amazon went head to head this festive season, and India’s cart was the real winner. 😅
Here’s the plot twist: a 10% bank discount on something you didn’t plan to buy isn’t saving 10%. It’s spending 90% on something you didn’t need.
Before you hit “Buy Now”, ask yourself:
✅ Was it on my list before the sale?
✅ Would I buy it at this price without the countdown timer?
✅ Will I still be paying its EMI in March?
Real savings is money that never leaves your account, or money you put to work: an emergency fund, a SIP, a cleared credit card bill.
Gen Z made up about a third of opening-day shoppers. It’s the same generation asking “how do I start investing?” Maybe the cart and the portfolio should talk to each other. 😉
In this battle between the e-commerce giants check out who is the real winner? Or more importantly are you the real loser? 🤔
Sales end. Discipline compounds.
Source: Redseer
For more such fun insights on money, follow @StockGro 🚀
#BigBillionDays #GreatIndianFestival #SmartSpending #PersonalFinance

India and the US are upgrading their power grids. This Vadodara company wants to be part of that story.
Meet Yash Highvoltage - a maker of critical components that help transformers handle high voltage safely.
-Revenue: ₹235 crore, up 57%
-Profit: ₹37 crore, up 75%
-Order book: Over ₹400 crore, up from ₹150 crore
-Expansion: A new factory planned to add around 6,000 units of annual capacity
-US opportunity: A new deal provides sales coverage across 19 states
The growth story looks promising. But there’s a catch. 👀
The stock is already up 110% this year and trades at around 15× sales, based on the figures in this story. Factory delays, valuation and thinner trading liquidity in SME stocks are risks to watch.
Can Yash Highvoltage turn the power-grid opportunity into sustained growth?
What do you think - a promising grid-upgrade story, or are expectations already too high?
Disclaimer: This post is for educational and informational purposes only. Please do your own research before making investment decisions.
#YashHighvoltage #IndianStocks #PowerSector

Bernstein has lowered its December Nifty target from 26,000 to 25,000, citing three key concerns:
-Weak earnings upgrades: FY27 earnings estimates have risen just 0.2% in three months.
-Global uncertainty: Geopolitical tensions, elevated crude oil prices and weak monsoon concerns could weigh on growth and corporate earnings.
-Rich valuations: Bernstein’s new target assumes 18x FY28 earnings, with another 4–5% market rally potentially pushing valuations beyond its comfort zone.
The key takeaway? A market rebound doesn’t automatically mean a sustained rally. Stronger corporate earnings will be crucial to supporting further gains.
What do you think about Bernstein’s revised Nifty target?
Follow StockGro for more business and stock market insights.
Disclaimer: This content is for educational and informational purposes only and is not investment advice. Do your own research before making investment decisions.
#nifty #stockmarket
🤖 Made with AI
Diamonds have always symbolised luxury. 💎
But lab-grown diamonds are changing the price equation, making these gemstones more accessible to consumers.
As the industry grows, could it also create opportunities for investors?
Here’s what you need to know before researching the space. 👇
#Investing #StockMarket


Cancer drug pricing is under the spotlight. 👀
India has approved a 30% trade margin cap for a wider range of cancer medicines, following concerns over high markups.
What could this mean for patients and pharma stocks like Sun Pharma, Dr. Reddy’s and Zydus Lifesciences?
The real impact depends on which medicines are covered and how the rules are implemented.
Should price caps extend to other essential medicines too?
#PharmaStocks #stockmarketsindia
