

Which crypto card costs what it says. 177 tracked, 31 closed to new users, fees read in the card terms and checked at a real terminal. Founder of Sweepbase.
Europe
Joined December 2010
- Tweets1.1K
- Following295
- Followers222
- Likes9.9K
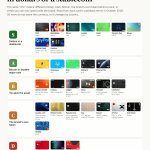





73 crypto cards pay cashback. 18 pay it in dollars or a stablecoin.
Dollars or stablecoin: @MetaMask in mUSD, @wirexapp in USD, @JupiterExchange in USDC
Bitcoin: @fold_app, @shakepay
The brand's own token: @cryptocom in CRO, @ether_fi in ETHFI with a 7-day lock, @plasma in XPL
Credit you can only spend with them: @redotpay USDs that expire in 30 days, @KASTxyz
Is 3% in a locked token still 3%?

I opened five earn-and-spend apps on 27 August and wrote down the rate inside each
Three disagreed with their own published numbers, in both directions:
- Hyperbeat: 4.42% in the app, "up to 8%" on its pages
- Tria: 9.41% in the app, on a vault advertised at 22.17% earlier in the summer
- MetaMask: 7.1% in the app, where its published figure had been 4%
One measured round trip on top: 1,000.25 AUSD into Tria's pool on 24 January, 1,015.54 back out on 21 May. About 4.8% a year. In July the same Earn tile showed up to 22.17%.
Rates move. Dated screenshots are the only yield numbers I trust.
What does your app show today?

30 crypto cards print 0% FX. Today I re-read 12 of them on the issuers' own pages.
Only 2 pay cashback with nothing in the fine print: @Venmo's credit card (3% on dining) and @gemini's (4% on gas and rides). Both US only.
With a footnote:
@fold_app: its rewards terms say USD purchases only
@minipay and @BleapApp: network fees "may apply"
0% in some currencies only: @ether_fi, @coca_card, @DeblockApp (Standard starts charging FX on 11 Nov)
@decaf_so dropped out: its card terms charge 1% abroad.
What did I miss?


What do you do with money sitting on your card: leave it in an earn product, or keep it plain?
Genuinely curious. I can't find anyone who agrees on this.
9 crypto card apps send your trade to the same Hyperliquid order book. Same price, but each adds its own markup on top of Hyperliquid's 0.045%:
+0.025%: @BasedOneX, @hyperbeat
+0.04 to 0.05%: @coin98_wallet, @BitgetWallet, @useTria
about 0.055%: @BloFinWallet
+0.10%, the most Hyperliquid allows: @MetaMask
On $10,000 opened and closed, that's $5 extra with Based and $20 with MetaMask.
@xPortalApp and @Ledger publish nothing. @JupiterExchange, @Revolut and @Bitpanda run their own venue.
Did your app show you its cut before you traded?

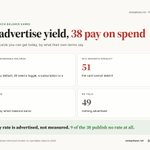
Crypto card yield: 94 cards advertise it, 38 pay it on the money you spend
Of the cards you can get today, 94 mention yield somewhere. Where it actually lands:
- 38 pay it on the balance the card spends from
- 51 pay it inside a separate product the card can't touch
- 5 never say which balance earns
Of those 38, only 9 pay by default. The other 29 need a toggle, a subscription or a transfer first.
Every rate here is advertised, not measured, and 9 of the 38 don't publish a rate at all.
Does yours pay on the spending balance?

Coinbase has two cards, and neither pays rewards outside the US
- Coinbase Card, a Visa debit: US through Pathward, UK and EEA through Paysafe. The US page says rewards are for US card users only, and the UK and EEA card terms don't mention rewards at all
- Coinbase One Card, an Amex, US only: 2% to 4% back in bitcoin, tiered by what you hold on Coinbase, with the boosted rate on the first $10,000 a month and 2% after
The debit card's cost moved too. The 2.49% conversion fee went in April 2022. What's left is a spread in Coinbase's own rate, and Coinbase doesn't publish it.
UK or EEA holders: did you expect rewards?

Brazil: the SPSAV filing deadline is today
Crypto platforms that were already serving Brazilian residents on 2 February 2026 have until today, 30 October, to file for Banco Central authorization as an SPSAV (Sociedade Prestadora de Serviços de Ativos Virtuais).
For card users, two numbers matter more day to day:
- IOF of 3.5% applies to cards issued in Brazil when you pay abroad, and to cash taken out abroad. A card issued outside Brazil has no Brazilian issuer to collect it, but charges its own FX on every purchase in reais: 1% to 2.2% on the cards I rank
- crypto sales of up to R$35,000 in total in a calendar month carry no capital gains tax. The attempt to replace that with a flat 17.5% lapsed on 8 October 2025
Brazilian readers: has your card's app said anything about SPSAV?

Which do you actually do: sell crypto to spend it, or borrow against it?
Trying to find out how many people use credit mode at all.
MetaMask Card's 1% fee depends on where the shop is, not the currency
The fee table defines it as using the card "with merchant located outside of cardholder country". Worked through:
- a Canadian paying from USDC at a Canadian shop: no cross-border fee, but 0.5%, because the stablecoin is in neither the buyer's currency nor the shop's
- the same Canadian at a US shop: 1% cross-border, no 0.5%
- an American at home: nothing, though new US sign-ups are paused
The Metal tier that waived the 1% hasn't taken orders since 2 June 2026, and it was US-only anyway.
Know any other card that prices by the shop's location?

Lately my feed is full of ads for big yields on Pendle's RWA loops. I wanted to see what that looks like in practice. Here's what I found.
PendleLoop shows about 7% a year on Tesla. All of it is USDC rewards, and most of them end in the next 10 days.
At 2x, the 7% is:
> a 3% reward for supplying the Tesla token, counted twice. Ends 29 Oct
> borrowing USDC costs 3.6%, rewards cover it for now. @pendle_fi's 3% ends 6 Nov
Nothing comes from Tesla. And you're 2x long: a 10% drop costs you 20%.
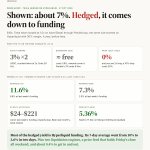
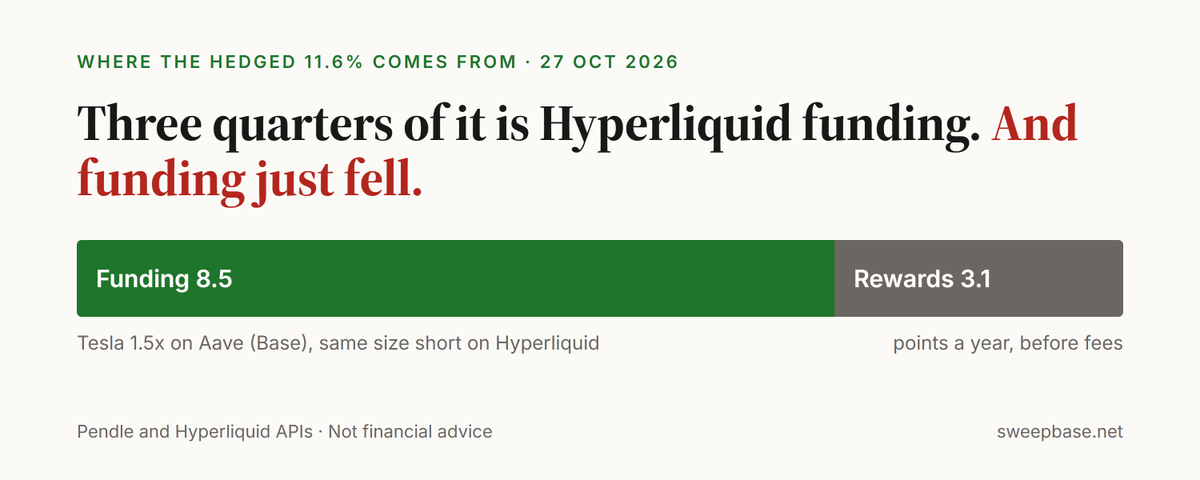
So I priced the hedged version. $10k, 1.5x long on @aave (@base), same size short on @HyperliquidX (the @tradexyz market).
> funding like last month (8.2%): 11.6% a year now, 7.3% once rewards end
> funding like last week (3.6%): 6.8% now, 2.5% once rewards end
A plain Pendle PT on @monad pays 5.36% fixed, with nothing to liquidate.
Before you loop, find the end date on every reward line.

Breakdown and sources: nitter.cf/sweepbaseHQ/status/211…
Rates from Pendle's loop API and Hyperliquid's API, 27 Oct 11:20 UTC. Funding is xyz:TSLA paid to shorts: 8.2% over 30 days, 3.6% over the last 7. Short margin 30%. Getting in and out costs about 0.4% of size, my guess, not measured. Modelled, not a live trade.
Weekend risk: the @chainlink feed holds Friday's price until Monday, while Hyperliquid keeps trading.

Who actually issues your crypto card? Of the 142 you can get today:
83 name the bank or e-money firm themselves
19 leave it to be inferred
40 name it nowhere I could find, @redotpay and @solcard among them
Why it matters: 21 card programmes stopped in 9 events since 2023, and only 4 came back.
Is yours in the D row?

@lindyhan Rechecked. You're right on Singapore: StraitsX is the Visa BIN sponsor for RedotPay's Singapore program, both companies said so in Feb 2025. RedotPay's own card terms still don't name it, and nobody names the issuer of the Hong Kong program. Moving RedotPay to the B row. Thanks for the catch.