

Research for the RWA stack. Private credit, fixed-rate lending, treasuries, stablecoins.
Onchain
Joined April 2025
- Tweets199
- Following22
- Followers32
- Likes201





NEW ARTICLE IS LIVE: Who actually owns onchain private credit?
(link in second tweet)
$180M of STAC sits on Solana with just 4 holders, and one wallet holds almost all of it.
I went through the holder pages of 23 private credit tokens, $5.18B in total. Here’s what I found:
1/ Most have tens of holders, not thousands
13 of 23 tokens, worth $2.06B, have fewer than 100 holders on their main chain. VRPCQ has 5. vUSD and gAUSD have 7 each. Only 5 tokens have more than 1,000.
2/ The biggest holder is usually a contract
For 19 of 23, the top holder is a contract, not a wallet. For 11, it’s a lending market: Morpho, Kamino, Aave, Euler or Fluid. Pendle holds 82.9% of reUSD and 70.3% of USD3.
3/ Outside the lending market, almost no one holds it
Morpho holds 96.8% of mGLO on Base, and $85.7M is borrowed against it. Only 7.3% of AUTO sits outside Kamino. The real owners are the depositors behind the market, and most of what they deposit is borrowed against.
4/ Thousands of holders doesn’t mean spread out
ONyc has 9,347 holders on Solana. Kamino still holds 57.3%, and the top 10 hold 87.6%. Even for the 5 tokens with over 1,000 holders, the top 5 own 81% to 93%.
5/ Open tokens move, whitelisted ones barely do
The typical token anyone can hold had about 12,300 transfers in 30 days. The typical whitelisted one had about 16. vUSD and gAUSD had none.
6/ Supply is moving chains
79.5% of syrupUSDG and 69% of PST have been bridged off the chain they were issued on. That’s one more step between the collateral and the issuer.
7/ More holders, same concentration
mGLO’s holders are up 41% in a month. Morpho still holds 96.8% of it on Base.
Few holders isn’t a red flag. Many of these funds are built for a small group of approved investors. But if you lend against one, the exit runs less through a market and more through the issuer. Knowing who holds it is the first check.

1
1
39
NEW ARTICLE IS LIVE: How to tell whether a private credit APY is real | Risk, Part 1
(link in second tweet)
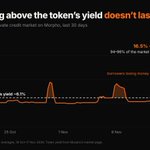
On 16 Nov, lenders in the PRIME market on Morpho earned 12.5%. A day later: 4.95%. Nothing broke. The market was just 94% borrowed.
Before you deposit into a private credit market, run these checks:
1/ Today vs the 30-day average
That market’s lend rate was 4.95% against a 5.68% one-month average. The PT-reUSD market paid 8.44% against 9.30%: close, so steady. Far above the average means a spike.
2/ How full the market is
Morpho’s rate climbs steeply past 90% borrowed, to about 15.6% at 95%. Kamino caps its curve: 5.44% at 95%, 7.15% max. A full market pays more, but leaves less cash to withdraw.
3/ Interest vs rewards
Gauntlet USDG Premium shows 7.21%: 2.71% interest plus 4.50% in ARB. Sentora PRIME Main: 6.33%, of which 2.22% is PYUSD rewards. Across 18 private credit vaults ($573M), about a third of the 30-day return was rewards.
4/ Does the collateral earn more than the loan costs?
PRIME earns about 6.15%. In the last month, the borrow rate went above that 3 times, up to 16.5% on 15 Nov. Each time borrowers repaid, and the rate fell back within days. It’s 5.94% now.
5/ For PTs, what’s inside the fixed rate
A PT’s fixed rate is the token’s own yield plus what traders pay for points. PT-reUSD lenders on Morpho earn 8.44%, but the next Pendle PT may price very differently.
6/ Same token, different APY
Morpho paid PRIME lenders about 12.5% on 16 Nov. Kamino paid about 4–4.5%. Same collateral, different rate rules. And on Fluid’s Ethereum markets, private credit backs about 52% of all stablecoin borrowing.
7/ Fixed rates are coming
Morpho Midnight and Tenor Finance offer fixed-rate, fixed-term lending, so a spike doesn’t change what you earn. Neither had a public PRIME market yet.
A high APY isn’t a red flag. Often it means borrowers want the market. These checks help you tell a rate that lasts from one that passes.


3
5
153
In private credit, the collateral token’s own yield is the real ceiling on what lenders can earn.
Most borrowing against private credit is looping: borrowers post a token like PRIME, borrow stablecoins, buy more PRIME and repeat. That only works while PRIME earns more than the loan costs. So borrowers can’t pay much more than the token yields for long.
PRIME showed this yesterday. The market hit 94% borrowed, past Morpho’s 90% target where rates climb fast. Borrowers were paying 13.8% to hold a token earning about 6%, and lenders saw about 12.5%.
Within a day, loans fell from $162M to $152M, about $9M of new deposits came in, and the borrow rate dropped to 5.9%, right under PRIME’s 6.1%. Lenders are back to about 5%, close to their 30-day average of 5.7%.
That’s the difference from lending against ETH or BTC. There, rates follow demand for leverage, and nothing caps them. Here, the token’s yield caps them.
So before trusting a private credit APY, compare it with what the collateral earns. If lenders are getting more than the token pays, borrowers are losing money, and the rate will come down.


I’ve been spending a lot of time on risk in onchain private credit lately, on both the lending and the borrowing side.
There’s a lot to cover. But if you’re here for the yield, one risk comes first:
The APY you see might not be the APY you get.
Yesterday, lenders in the PRIME market on @Morpho were earning about 12.5%. Today it’s about 5%. Nothing changed in the loans behind it. The market just got too full, and then it didn’t.
Why an APY can look higher than it is
→ It’s a short-term jump. When almost all the money in a market is borrowed, the rate shoots up. It falls back once borrowers repay or new lenders come in.
→ Part of it is rewards. A token incentive sits on top of the interest, and it lasts only as long as the program does. Gauntlet’s USDG Premium vault on Morpho, which lends against Maple’s syrupUSDG, shows 7.2%, and 4.5 points of that is rewards.
→ Borrowers are losing money at this rate. Your yield comes from borrowers. If the token they borrow against earns less than their loan costs, they’ll repay and leave, and the rate comes down with them. Yesterday PRIME borrowers were paying 13.8% against a token earning about 6%. Today the borrow rate is 5.9%, back below what PRIME earns.
→ With fixed-rate PTs, the rate is locked, but part of it comes from traders paying up for points, not from the loans. The next PT may not price the same way.
Most of this isn’t in the headline number. You have to dig for it.
What’s coming tonight
I’m publishing an article tonight that goes deep into this one risk: how to tell whether a private credit APY is real.
It’s the first in a series. In the next articles, I’ll cover the other risks lenders and borrowers face in onchain private credit.

1
79
Private credit is now bigger than Ether as collateral on @Morpho. Much of it is looped: the price barely moves, so markets allow bigger loans and run almost full. It rests mostly on issuer NAVs and a handful of vaults.

1
5
173
Sneak peek from upcoming State of Private Credit report: inside @Morpho’s private credit lending vaults
1/ Private credit is the #3 collateral on Morpho.
$1.06B is lent against it, 18% of all stablecoin lending on Morpho.
Only BTC ($2.87B) and stablecoins ($1.16B) are bigger. ETH is behind at $470M.
2/ It’s the busiest market
91% of the money lent is borrowed, the highest of any collateral type.
3/ Borrowers take bigger loans against it
For every $1 of private credit tokens posted, borrowers take $0.80. Against Bitcoin it’s $0.58, and against Ether $0.51.
4/ PYUSD and USDG lean hardest on private credit
56% of all PYUSD lent on Morpho goes to private credit borrowers. For USDG it’s 43%, and for USDC just 11%.
5/ Five issuers make up 86% of the collateral
@maplefinance, @hastra_fi, @MidasRWA, @re and @humafinance. Two tokens alone, PRIME and syrupUSDG, are 38%.
6/About a fifth of the collateral (19%) is fixed-yield tokens (PTs).
Most of Re’s collateral on Morpho is PT-reUSD (93%), not reUSD itself, and 3Jane is the same with 84% in PT-USD3. Borrowers lock in a fixed yield first, then borrow against it.
dropping something next monday: the State of Private Credit Onchain report. been spending a lot of time on it, and really excited to finally put it out.
→ it starts with the market, from both the lender and borrower lens: how big it is, types, and how private credit became the most used RWA in DeFi, especially for looping
→ private credit pays as high as 11%+. so who are the actual borrowers, and where is that yield coming from?
→ why people loop private credit tokens, and which ones make “good” collateral
→ why most lending protocols are launching fixed rates
→ and all of it rests on one thing: can you get out, and who takes the hit when something breaks?
and a lot more.....
covering:
private credit platform: @maplefinance @3janexyz @AccountableData @re @HastraFi @humafinance @MidasRWA @centrifuge @paretocredit @USDai_Official @KAIO_xyz
lending: @Morpho @kamino @aave @TenorFinance @eulerfinance @Loopscale
curators: @SteakhouseFi @gauntlet_xyz @SentoraHQ @Re7Labs @kpk_io @ClearstarLabs
looping, exit and liquidity: @symbioticfi @FissionXYZ @KeyringNetwork @3f_xyz
and many more than tagged.
I’m also building a private credit analytics site and talking with teams about it. if you’re building in private credit or RWAs, my DMs are open.
see you monday with the report.

1
5
96
NEW ARTICLE IS LIVE: The Maths Behind Private Credit Yields Onchain
(link in second tweet)
Private credit is one of the fastest-growing parts of onchain lending, and one of the hardest to read.
Where does the yield actually come from? How much of it is real interest and how much is rewards? What happens if borrowers don’t pay back? And can you get your money out whenever you want?
It all comes down to a few simple formulas.
I took $10,000 through @kamino, @Morpho and @pendle_fi, screen by screen, and explained every number you’ll see:
1/ APY vs what you actually earn
2/ Share price and NAV
3/ Utilization, and why rates jump past 90%
4/ LTV, and how much room you really have
5/ Looping, and why it’s just one spread repeated
6/ Fixed rates and PT prices
7/ Exits, and how getting your money back works
8/ Expected loss, the number no app shows
Every formula comes with a real screenshot and checks out against the live numbers.
The examples are ONyc by @onrefinance, syrupUSDC by @maplefinance and sUSDai by @USDai_Official.
If you lend, borrow or loop private credit, this one’s for you 🧡
2
3
89
NEW ARTICLE IS LIVE: The State of Private Credit on Kamino
(link in second tweet)
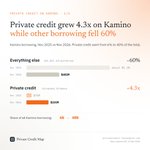
Private credit is now 40% of everything borrowed on @kamino. A year ago it was 6%.
1/ The size
$325M is now borrowed against private credit tokens on Kamino, up 4.3x from $76M a year ago. That debt is backed by $466M of private credit collateral.
2/ The growth came in two waves
Wave 1: PRIME by @HastraFi
PRIME launched on Kamino in December and reached $263M of borrowing by April. Today it’s $70M.
Wave 2: ONyc and AUTO, still growing
• ONyc by OnRe: $3M a year ago, $97M today
• AUTO by @HastraFi: launched in July, $71M today
3/ It’s concentrated
Five tokens hold 92% of it:
• ONyc by OnRe (incl. its PT): $97M
• AUTO by @HastraFi: $71M
• PRIME by @HastraFi: $70M
• syrupUSDC by @maplefinance: $39M
• PST by @humafinance: $24M
4/ It’s a looping market
Two-thirds of the collateral, $312M, sits in Multiply loops. For AUTO, PRIME and syrupUSDC it’s 80% or more.
Looping is how AUTO’s 11.7% yield becomes about 31% at max leverage, even at the rate most loans actually pay.
5/ Kamino Fixed Rates: $81M of private credit borrowing is now fixed
Kamino opened its first fixed-rate market in September and officially launched Fixed Rates in October. In that short time it has grown to $81M, a quarter of all private credit borrowing on Kamino.
Most of it is AUTO by @HastraFi. Borrowers take wYLDS at 5.30–6.25% on 30-day terms that renew automatically, against a token yielding about 11.7%. 89% of AUTO borrowing is now fixed, and every fixed pool is fully lent.
6/ Vaults fund half of it
Earn vaults supply about $170M of the $349M supplied. Three curators, @SentoraHQ, @kamino and @RockawayX, handle 77% of the vault money that goes into private credit.
It pays: vaults with half or more in private credit show 7.0%, against 3.7% for vaults with none (Kamino’s vault APY, incl. rewards).
8/ Kamino vs Morpho
Private credit is 40% of borrowing on Kamino, against about 16% on @Morpho. Kamino also runs fixed-rate pools inside the same markets, which is where a quarter of its private credit borrowing already sits.


Kamino stablecoin vaults with half or more in private credit earned about 7.0% over the last 30 days, versus 3.1% for vaults with none and 4.24% on 13-week T-bills.
Our next deep dive, The State of Private Credit on @kamino, is coming soon. A look at the Earn vaults ↓
1/ Two of every three dollars deposited in Kamino's vaults end up lending to private credit.
That's $221M of the $329M in the 34 vaults shown in the app (67%). Among stablecoin vaults alone, it's 70%.
2/ Three vaults carry most of it:
• @SentoraHQ PYUSD ($72M)
• Kamino Institutional Commodity Yield ($50M)
• @RockawayX RWA USDC ($49M)
Together they supply 78%. Add @SteakhouseFi USDG High Yield ($26M) and it's 89%.
3/ Four tokens take most of the vault money.
Of the $170.5M the vaults lend against private credit tokens:
• ONyc (reinsurance) $46.0M
• @maplefinance syrupUSDC $41.9M
• @humafinance PST $25.8M
• @HastraFi PRIME $20.5M
That's 79%. The rest goes to reUSD ($10.4M), nOPAL ($9.2M), AUTO ($5.7M), oTFY ($4.7M), mF-ONE ($4.5M) and sUSDai ($1.8M).
4/ Most tokens have one main lender.
For 7 of 10 private credit tokens, one curator supplies over 90% of the vault lending:
• Sentora for syrupUSDC and PRIME
• Steakhouse for reUSD and mF-ONE
• @Re7Capital for nOPAL
• RockawayX for oTFY
• Allez Labs for sUSDai
5/ There are two routes into private credit:
• $170.5M is lent against private credit tokens, with onchain collateral behind every loan
• About $50M funds commodity trade loans through Kamino Institutional, where repayment depends on those offchain borrowers
And AUTO's $63M of fixed-rate loans are funded by a vault outside the app, the wYLDS Allocator.
The extra yield comes with private credit risk, so it's worth knowing what your vault lends against.
The full article is coming TODAY.


4
104
Thanks for the share @HastraFi
One more number since the article: we looked past Morpho too.
Add @kamino and PRIME has ~$243M borrowed against it. That's the most of any single private credit token across the big lenders
Full ranking coming tomorrow.

PRIME has become one of the most utilized private credit assets on Ethereum, via @Morpho.
According to new research from @therawbyte:
→ $173M borrowed against PRIME, the second-largest private credit collateral asset on Morpho.
→ @SentoraHQ's PRIME Main vault allocates 98% of its lending to PRIME-backed markets.
→ PRIME's largest lending market has reached $190M.
The significance goes beyond tokenization. Real-world home equity credit is becoming productive collateral, supporting stablecoin borrowing and institutional-scale capital deployment.
Onchain credit markets are maturing at a rapid rate.
2
4
115
NEW ARTICLE IS LIVE
(link in second tweet)Private credit is now about one in every six dollars borrowed on @Morpho.We went through every Morpho market to find out who’s borrowing, who’s lending, and where it could break.
1/ The size
$965M is borrowed against private credit tokens on Morpho. A year ago it was $124M, so that’s about 8x.
It peaked at $993M on 30 Oct and has been flat since.
2/ It’s concentrated
Five tokens hold 80% of it:
• syrupUSDG by @maplefinance: $206M
• PRIME by @HastraFi: $173M
• reUSD by @re: $159M (mostly through its Pendle PT)
• mGLO by @midasrwa × Fasanara: $137M
• PST by @humafinance: $96M
3/ The lenders are vaults
93% of the money comes through curated vaults, not people picking markets.
Some go all in: @SteakhouseFi’s USDG Pro is 100% syrupUSDG, and @SentoraHQ’s PRIME Main is 98% PRIME.
The big ones keep it to about a fifth.
4/ A few big lenders carry each market
The largest PRIME market ($190M) is funded by one vault, @SentoraHQ’s PRIME Main. The biggest PST and syrupUSDC markets work the same way, also through Sentora-curated vaults.
That keeps things simple, but it also means one lender’s move can shift the rate for everyone.
5/ Locking in yield with PTs
20% of the borrowing is against @pendle_fi PTs: fixed-yield versions of reUSD (@re) and USD3 (@3janexyz).
Since October, the PT’s fixed yield has sat above the cost to borrow against it: about 12% vs 10% for PT-reUSD.
6/ Fixed rates are the next unlock
@TenorFinance has offered fixed-rate markets for reUSD and USD3 since September.
@Morpho Midnight has already originated $100M+ in fixed-rate loans, mostly against crypto.
Private credit is next in line: today it’s about $50K fixed vs $965M variable. That’s a lot of room to grow.
7/ April shows how it breaks
Borrowing fell from $373M to $157M in under a week, almost all of it syrupUSDC.
The token price never moved. Lenders pulled out first, rates spiked to 14–16%, and borrowers repaid.


Read the full article, with every token, vault and chart:
therawbyte.substack.com/p/th…
1
41
NEW ARTICLE IS LIVE!
(link in second tweet)
I checked ~120 lending markets on @Morpho, @kamino, @aave and @eulerfinance to see where RWAs actually sit.
10 things I found:
1. $2.4B of RWAs are used as collateral in DeFi lending. $1.8B is borrowed against them.
2. Morpho holds most of it: 59%. Kamino has 21%, Aave 20%, Euler under 1%.
3. 87% is private credit. Tokenized Treasuries are under 1%.
4. Six issuers make up most of the big markets: @maplefinance, @HastraFi, @onrefinance, @re, @MidasRWA, @humafinance.
5. The largest single market is PRIME from @HastraFi on @Morpho: $234M deposited, $168M borrowed.
6. People borrow 75 cents for every $1 they deposit. With private credit, they borrow and loop. With stocks and gold, they mostly just hold.
7. Fixed-rate borrowing only really happens on @kamino. 43% of its RWA loans are fixed.
8. Morpho has 28 fixed-rate RWA markets on Midnight. Almost nothing is borrowed in them yet.
9. Lenders are running out of room. Morpho's biggest RWA markets are 84–91% lent out, mostly through @SteakhouseFi and @gauntlet_xyz vaults.
10. 1 in 5 dollars in Morpho's biggest RWA markets is priced by the issuer itself (@MidasRWA, @paretocredit), not an independent oracle like @chainlink.
1
2
95
Full article. Subscribe it, pretend you'll read it later, then actually read it ↓
therawbyte.substack.com/p/wh…
1
36
NEW ARTICLE IS LIVE!
(link in second tweet)
This is one of the pieces I've loved working on most, and spent a lot of time getting right.
The big idea: DeFi lending has never had demand of its own. It rented it from the crypto cycle. When prices fall, borrowing dries up. Aave's USDT lenders went from 13% to 2%.
Private credit is the first asset that breaks that loop. It pays for its own loan, so people borrow against it whether crypto is up or down.
> 21% of tokenized RWAs
> 90% of RWA collateral on @Morpho, @kamino and @aave
> borrowing against it up 9x in a year
And the constraint has flipped: the pools are nearly full, so now borrowers are waiting on lenders.
This is part one. Follow-ups are coming on the risks, and what has to get better for this to scale.
With data and work from:
@RWA_xyz @DefiLlama @Dune @chainlink @JupiterExchange @SkyEcosystem
@SteakhouseFi @gauntlet_xyz @paretocredit
@maplefinance @HastraFi @re @onrefinance @MidasRWA @humafinance
@TenorFinance @term_labs @pendle_fi
@FissionXYZ @symbioticfi @multiliquid_xyz @redstone_defi
1
6
209
Here's a glimpse of what's inside.
There's $39.4B of tokenized RWAs today. Treasuries are the biggest slice at $14B. Credit is only 21%.
So you'd expect DeFi lenders to love Treasuries.
They don't.
On Morpho, Kamino and Aave, $14B of tokenized Treasuries puts just $5.5M to work as collateral. Credit puts $2.05B. That's 90% of all RWA collateral on those three lenders.
Why?
Every asset has to pass two tests to work as DeFi collateral:
> Does it pay for its own loan?
> Can a lender price it and sell it at any hour?
Most RWAs fail one of them.
Treasuries: easy to price, but they pay 3–4%. Borrowing against them costs about the same. Nothing left to loop.
Gold: earns 0% while it sits as collateral. Every loan against it starts in the red.
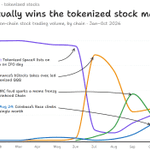
Stocks: the price feed goes dark from Friday night to Sunday night. A stock can sit frozen for 48+ hours while its token keeps trading. Lenders cut leverage hard to survive it. Kamino caps MSTRx at 30% LTV. So traders skip loans and use perps instead: $8.6B of open interest.
Credit: passes both. It's priced off the loans behind it, so it has a price on Saturday too. And it earns more than it costs to borrow against.
That gap is the whole trade. AUTO, a token backed by US auto loans, earns 10.3% on Kamino. Borrow against it at a fixed 5.3%, loop it 3x, and you're at ~20%.
That's why loans backed by credit on Morpho and Kamino went from $137M to $1.2B in a year.
And the biggest credit tokens now borrow cheaper than BTC on Morpho.
The catch? Lenders are running out of room. Credit lending pools are 89–100% lent out.
The article also covers:
> How a private loan actually becomes DeFi collateral
> Who's funding these markets and why they're capped
> Why fixed-rate money is the missing piece
> What can still break: hidden losses, slow exits, and two issuers holding 58% of all credit collateral
Full piece drops later today.
I've been sitting on this article for a while.
It's finally going out later today. (Fair warning: it's data-heavy.)
I pulled every major RWA category into one place to answer a single question:
Why is credit the only RWA that consistently wins as DeFi collateral?
Inside:
> Why Treasuries don’t pay enough to borrow against
> Why gold generates nothing as collateral
> Why stocks go “dark” every weekend (and why traders park $8.6B in perps instead)
> Why credit is 21% of RWAs, but ~90% of collateral on Morpho, Kamino, and Aave
> The backstory: from Maker’s Black Thursday to the rate cycle
> What could still break
Data & sources: @Morpho @kamino @aave @tokenterminal @DefiLlama @chainlink @RWA_xyz
Dropping later today on @therawbyte substack.