




Pinned Tweet
Bring in the gold or silver coin you've never been sure about. Our new Salt Lake City shop tests it while you watch and shows you the live spot price behind our offer. We buy and sell, and sellers are paid the same visit.
3650 W 2100 S, Mon to Fri 9 to 5
slc.summitmetals.com

Credit's been quietly getting nervous while everyone watched oil.
Junk-bond spreads went from 2.60 points in late August to 3.40 on Oct 22, the widest since March. They closed Oct 29 at 3.26, still above their 3.02 median of the last three years, per the ICE BofA high-yield index on FRED.
Nothing has broken yet. But wider spreads mean riskier companies are paying more to borrow, and if that keeps up, I'd say it makes a December hike harder for the Fed, which is the part gold and silver holders care about. The Fed's loan officer survey lands at noon Mountain and will show whether banks are tightening too.

Crude is trading the Doha talks this morning, not the tankers still getting hit in the Gulf.
Brent fell more than 4% after Iranian negotiators left the Qatar-mediated talks with a draft proposal circulating, per Reuters. Overnight, UKMTO reported another tanker struck by two projectiles off Saudi Arabia, so the shipping risk hasn't gone anywhere. The market is choosing to price the diplomacy first.
I think oil reaches gold and silver mostly through inflation. A crude risk premium feeds inflation expectations and puts pressure on yields, and that's been a headwind for metals. Silver is up about 2% this morning and gold is slightly higher. If the talks stall, that premium can come back into oil quickly.
The release I care about most this week isn't Friday's jobs report. It's Wednesday morning, when Treasury says how much long-term debt it plans to sell.
Treasury has held its quarterly 3-, 10- and 30-year auctions at $125 billion since May 2024 and leaned on short-term bills for the rest. If Wednesday's statement bumps those sizes or drops the "at least the next several quarters" line, private buyers have to absorb more long bonds, and that pressure can run through yields to gold.
The other date is Tuesday. Trump said no new strikes on Iran before the midterms. He hasn't ruled them out after.
Tuesday night into Wednesday I'm watching Iran headlines once the vote is counted. Talks in Doha are still going, and oil is one fast route from that story to gold and silver.
Wednesday at 6:30 AM MT it's coupon sizes and that one guidance line in the refunding statement.
Friday at 6:30 AM MT is October jobs. September payrolls were +29K, and another soft print would test the Street's December hike call.
Investors pulled money out of GLD in October, the biggest monthly outflow since June in State Street's daily fund file.
I'd go by the share count, since it takes the gold price out. It slipped only a little, so most of the drop in the fund's assets came from gold falling. Of the shares GLD added during last year's record dollar inflows, about seven in every eight are still there.
So last year's buyers have mostly held on through a rough month. The next few State Street prints will show whether October was a trim or the start of a bigger exit.

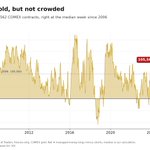
Funds are net long 105,562 gold contracts. The median week since 2006 is 105,564.
In August they held 144,747. In silver they're down to a net 3,321, the smallest since February 2024. That's CFTC data as of Tuesday, before Friday's drop under $3,900.
If you own gold or silver, the funds were not crowded in going into Friday's drop.

If you're in the Salt Lake area, we are near the SLC airport. Our online presence at summitmetals.com continues to thrive as well.

On your first visit, mention slc.summitmetals.com before we write up your order and you get a first-time discount. We speak English and Spanish at the counter.

Tech and gold are going out the door together this morning.
The Nasdaq is down more than 2% after Amazon's and Intel's results added to the worries about AI spending, and gold and silver are lower with it. That's not how most people picture a safe haven. In a fast selloff, funds can sell whatever is easiest to turn into cash, and gold trades in deep, liquid markets. I'd watch whether gold steadies once the stock selling slows down. If it does, that would fit funds raising cash.
Silver has fallen about three times as hard as gold since Oct 20.
COMEX silver is down about 13% in eight sessions and gold about 4%, so an ounce of gold now buys 79 ounces of silver, up from 71. That's the highest gold/silver ratio since late November 2025, though still below the 83 of a year ago. Silver swings harder than gold in both directions, and holders of both are seeing that side of it this week.

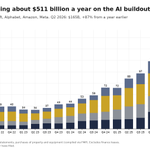
Alphabet fell about 12% today after reporting negative free cash flow, and the company says capex will rise significantly in 2027.
Capex was $51.4 billion last quarter against $42.3 billion of operating cash flow, so free cash flow came in $9.1 billion negative, the second straight negative quarter. A $5.2 billion payment on an EU fine and a build in TPU system inventory added to it. Most of that money goes into servers, networking gear and data centers, which use copper, silver and power. Silver and copper are both lower today, which I'm not pinning on Alphabet. Numbers are from Alphabet's Q3 release and call.
I don't expect Washington to cut its way out of the debt. No politician wants to tell people the benefit they paid into is going away. Without cuts, the bill can get paid in dollars that buy less. That's my case for gold and silver.
This is from my Oct 24 video on how the debt ends: youtube.com/watch?v=7yBTsmE-…
Big debts have often been worked down through inflation over time, and savers in cash and bonds carry that cost when their interest doesn't keep up.
Metal pays no interest, but it isn't anyone's promise to repay. Its price swings a lot, and it is well below this year's high, so it carries its own risk.
None of this has a date on it. To me that makes it a reason to hold some metal for years.
Prices rose 0.5% in September. After taxes and inflation, income fell 0.3%.
BEA's PCE report put inflation at 3.6% from a year ago and core at 3.1%, both in line with forecasts. The saving rate was 3.8%, and Q3 GDP grew at a 3.4% pace. My read is that falling real income with inflation at 3.6% helps the long-run case for holding metal, even on a morning when gold and silver trade lower.

Warsh said the Fed will cut back on rate votes, with one meeting in 2027 set aside for strategy and no vote on policy.
My read is that with fewer rate votes on the calendar, each one that remains may matter more to bonds and metal.
Gold dipped a little when the statement hit and won part of it back going into the press conference. Silver moved with it.

The Fed held today, and both dissents wanted a hike, not a cut.
Lisa Cook and Beth Hammack voted for another quarter point. The statement still says inflation remains elevated, upgraded growth from solid to strong, and swapped September's promise of a timelier return to 2 percent for waiting on "the accumulation of more information."
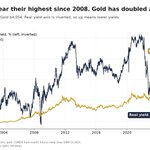
To me that reads like a pause. With the 10-year still near 5 percent, holding metal instead of bonds costs more, and nothing in today's text changes that.
Correction on my Fed post: I said the statement swapped September's promise of a timelier return to 2 percent for waiting on more information. That made it sound like the goal was dropped. It wasn't. The new statement still states a timely return of inflation to 2 percent. What went away is September's line that the policy action "will support a timelier return to the Committee's 2 percent goal."
Fed Decision is out for today. The fed has left rates unchanged in a 10-2 vote. Today is not about today, it is about December and beyond. In particular, where to the fed governors stand. That is what the market is fully focused on.