

Economist, paid for doing what I love by Moody's Analytics as senior euro zone economist. Views my own. @crisisstudent.bsky.social
Prague
Joined March 2013
- Tweets6.5K
- Following371
- Followers2.8K
- Likes4.2K




Pinned Tweet
So what does this mean for the recent past and the future tariffs?
Broadly, my thesis is that individual tariffs have a different mix of motivations belonging to different categories, which implies different durability, but overall, tariffs are not going away anytime soon.
1/


Kamil Kovar retweeted

🇪🇺 These are the best policy profiles of Klaas Knot and Pablo Hernández de Cos you'll ever read, by Tim Jones on substack.
Knot: 242econ.substack.com/p/a-haw…
De Cos: 242econ.substack.com/p/el-in…


Kamil Kovar retweeted

Germany October CPI (EU-Harmonized):
m/m -0.1% (est +0.1%, last +0.6%)
y/y +2.8%(est +3.1%, last +3.3%)
Germany National CPI:
m/m -0.2% (est +0.1%, last +0.6%)
y/y +2.8% (est +3.0%, last +3.3%)
Lower than Consensus, as suggested by regional data. PPI still points to higher CPI


Kamil Kovar retweeted
🇪🇺 Three observations on the ECB's Survey of Professional Forecasters, if you believe inflation "expectations" matter.
1/ Medium-term SPF expectations remain very much anchored, all things considered.

Nice chart and note by @jasonfurman . Aligns a lot with my thinking. The fact that this is very synchronized across globe has to mean global factors are at play. And that I think points to Iran in the near-term, and higher neutral rate in the medium to long term.


G7 interest rates rose this year largely on one global force: a common factor added about 80 to 100 basis points. Japan, as usual, is the exception. Country-specific factors pushed rates up a lot in France and Japan and down in Canada and Germany.
econvitals.org

Adding a link to my analysis from back in September, since Jason has reposted this:
nitter.cf/CrisisStudent/status/2…

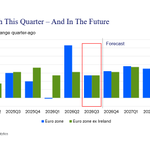
Euro zone GDP continued to do what it does best: grow at a modest pace.
Ex Ireland, GDP growth came in at 0.22%, down from 0.32% in Q2 (0.42% vs 0.64% with Ireland).
Country composition was almost identical to last time: strong 🇪🇸 and 🇳🇱, solid 🇩🇪, weak 🇮🇹 and esp. 🇫🇷.
1/

The outlook remains more of the same.
High energy prices will continue to hold consumption back, but a high savings rate will allow us to avoid a decline in consumption.
Fixed investment will remain weak in France and Italy, but strong in Germany and Spain.
4/


Kamil Kovar retweeted

‼️ Sharp hawkish spike in our #ECBToneMeter following Lagarde's press conference.
Her repeated assertion that the direction of rates is "clear" barring "major developments" suggests another hike is now the baseline expectation.
Her more hawkish tone lifted both indices:
🔹 Governing Council: +0.81 → +1.27
🔹 Executive Board: +0.60 → +1.70

I mean, if you are using eurozone including Ireland, you should not call yourself eurozone macroeconomist...


Man, is it just me, or was this timing partly about moving the attention of the press conference away from France debt questions? 😀
Either way, we will get a lot of pointless back-and-forth, and I am not looking forward to it.

Full story: Christine Lagarde steps down as European Central Bank president.
Departure set for 7 February.
euronews.com/2026/10/29/ecb-…

Nice piece by @RobinWigg on the vibecession, confirming what most of us already knew:
It is all about money illusion, people disliking nominal increases even if they are not real.
The catch? People feel according to nominal prices, but clearly spend according to real incomes.

I know this old piece by Twitter (never X!) standards, but I missed it back than, partly because it did not get the reach it should have (though if you are like me you might want to skip to the middle, technical part).
The best thing about it: It is balanced!
1/

An accompanying piece to my Odd Lots episode.
It's not just about the technicalities of comparing living standards: the obsession with relative decline and 'competitiveness' is a form of declinism: "the unwitting last refuge of great power delusions."
🧵 phenomenalworld.org/analysis…

